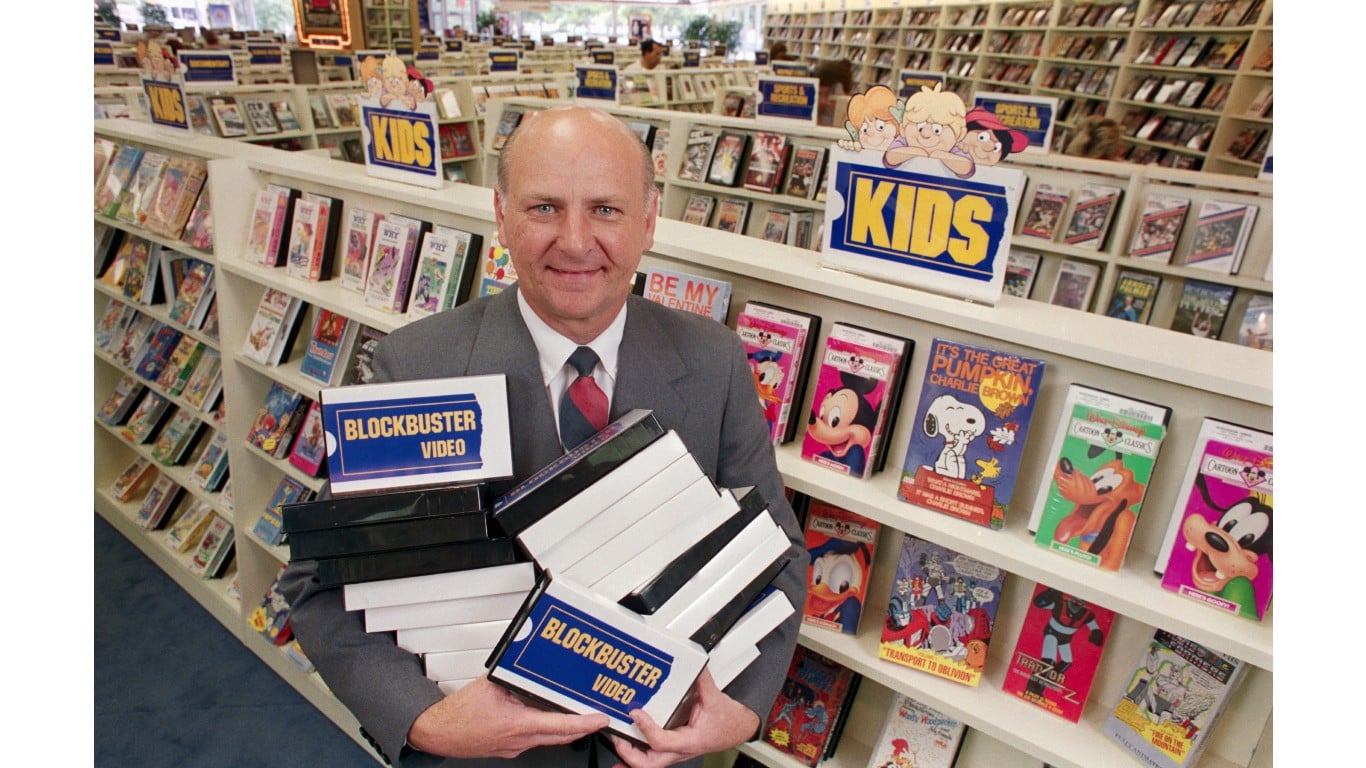
In the mid-1980s, Wayne Huizenga walked into a Dallas video store and saw something the industry itself had not yet named. The shelves, the customers, the local ownership were incidental. The point was structure. Thousands of independent operators, no dominant brand, no purchasing leverage, no consistent experience. It was a fragmented industry, and fragmented industries were what Huizenga did. He had been running that same recognition through the waste-hauling business he began dominating in 1968, rolling up small operators into a national footprint. Video rental was structurally identical. The movies were incidental.
Buying the Platform
Huizenga bought 60% of Blockbuster for $18.5 million, took the chairman and chief executive roles, and moved immediately. The company he acquired was a going concern with a superstore concept already proven in a handful of markets. What it lacked was the one thing he knew how to supply: velocity. A detailed profile of his career and this transaction is catalogued in his Britannica biography.
Velocity as Strategy
The numbers from the buildout are the spine of the story. By the end of 1987, there were 133 Blockbuster stores. By the end of 1989, there were 1,089. At peak, a new Blockbuster was opening every 17 hours. That was the pace of a company that had decided the market would belong to whoever got there first at scale.
How the Ground War Was Fought
The tactics were deliberate and specific. Blockbuster opened massive superstores stocked with 40 copies of a new release, at a time when local competitors carried 4. Customers who walked in looking for the movie everyone was talking about actually found it, and they stopped bothering with the shop down the street. Huizenga hired away rival chains’ top executives, importing operational knowledge along with the org chart. And he surrounded regional players geographically, opening stores around them until a sale to Blockbuster was the only rational exit left. The East Coast chain Erol’s, once a serious force, eventually capitulated. This was a method, applied with discipline.
Consolidate First, Then Price
Then came the turn, and the turn is where the waste-hauling parallel earned its keep. Once Huizenga had a lock on the market, he did what he had done with landfills. He raised prices. A rental that cost $3 for three nights in the early days became, by 1994, a one-night rental at the same $3, with punishing late fees attached to any customer who missed the return window. That is the entire roll-up logic compressed into a single line item: consolidate first, then price. Fragmentation had kept prices in check. Consolidation removed the constraint.
What Market Share Did Not Measure
Huizenga genuinely built a near-unassailable position. Speed and scale delivered exactly what the playbook promised. The blind spot was the playbook itself. Waste hauling rests on a distribution reality that does not change: garbage has to be picked up, driven somewhere, and put in the ground. Video rental rested on a distribution reality that could change, and would. As early as 1991, at the moment the chain looked most invincible, a USA Today columnist warned that video stores were headed for extinction. The warning proved correct. Blockbuster no longer exists as a major chain.
The lesson is hard. Companies that move fast enough to dominate can still be blindsided when they mistake market control for permanence. Huizenga won the industry. The industry was the problem.