Where we heard itThoughtful Money with Adam Taggart, “Value Stocks Set To Outperform Tech Into The End Of Year?” Released Oct. 10, 2026. Speaker: Lance Roberts, chief investment strategist at RIA Advisors. Listen to the episode
Portfolio manager Lance Roberts is making two kinds of moves right now. Some are trades he has already placed. The others make up a bond plan that only kicks in if stocks correct. Speaking with host Adam Taggart on Thoughtful Money, Lance Roberts described trimming tech names like AMD and Nvidia after big runs, doing year-end tax loss harvesting in the bond portfolio, and adding to value-oriented positions including Berkshire Hathaway and utilities, which he said are “really beaten up.” All figures below are settled closes from Friday, Oct. 9, because markets were closed over the weekend.
Checking His Chip Trims Against the Numbers
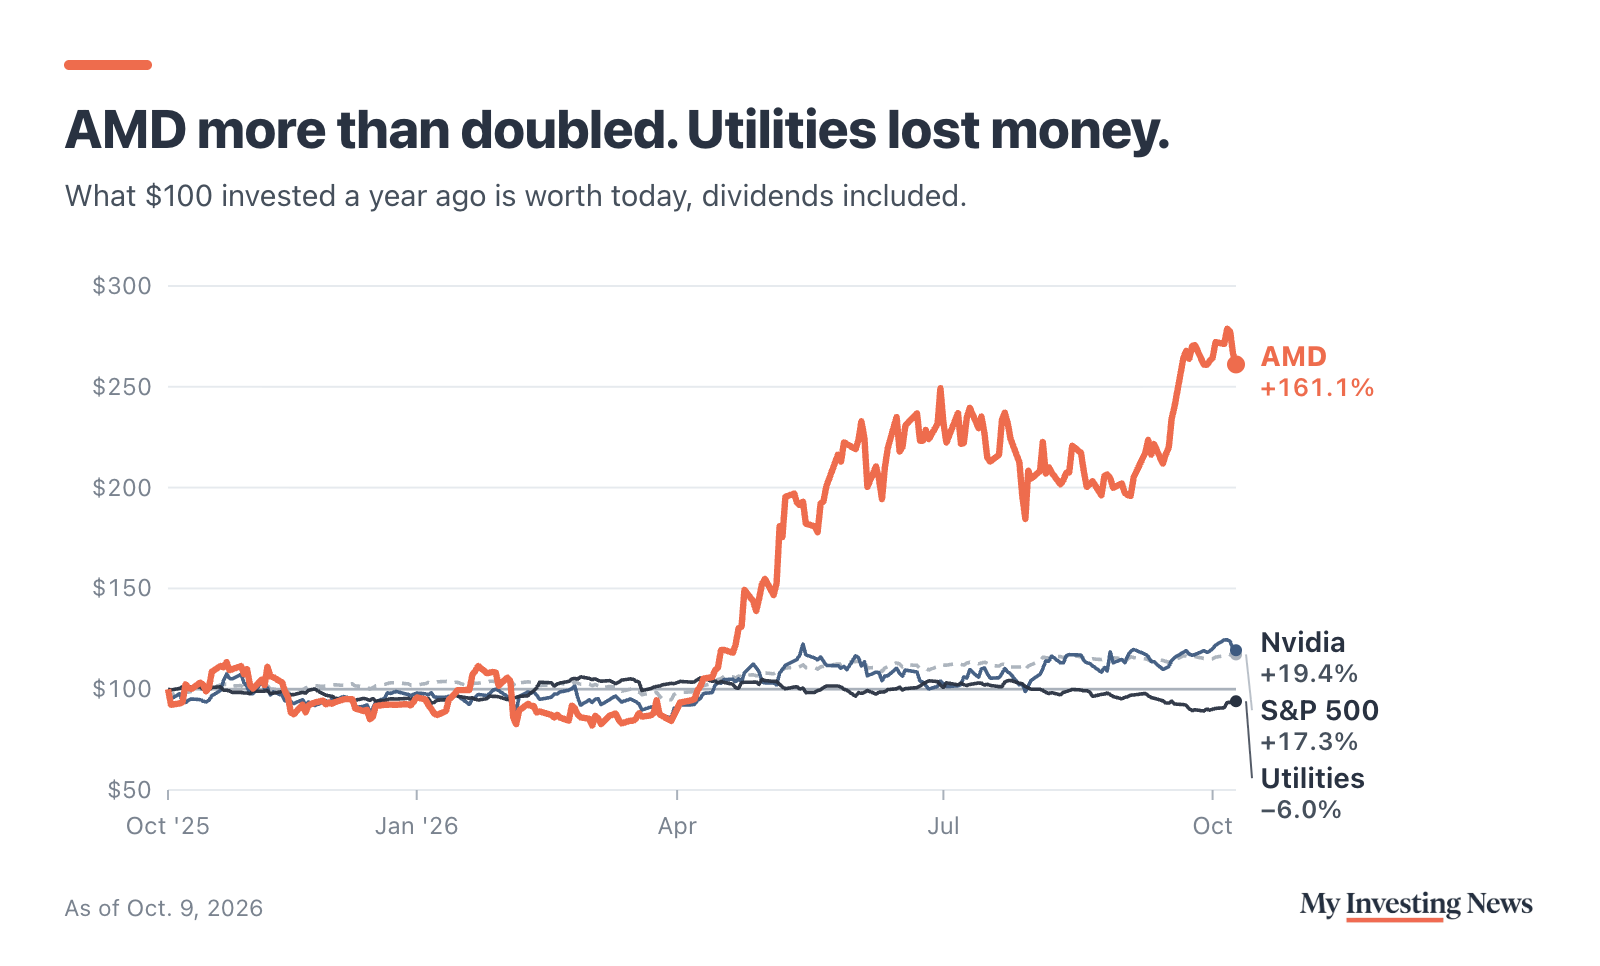
Advanced Micro DevicesAMD is up 183.95% year to date and 161.11% over one year. Meanwhile, NVIDIANVDA is up 23.23% year to date and 19.35% over one year, including dividends. “Big runs” describes both stocks, but the two moves differ enormously in size, and grouping them together hides that difference.
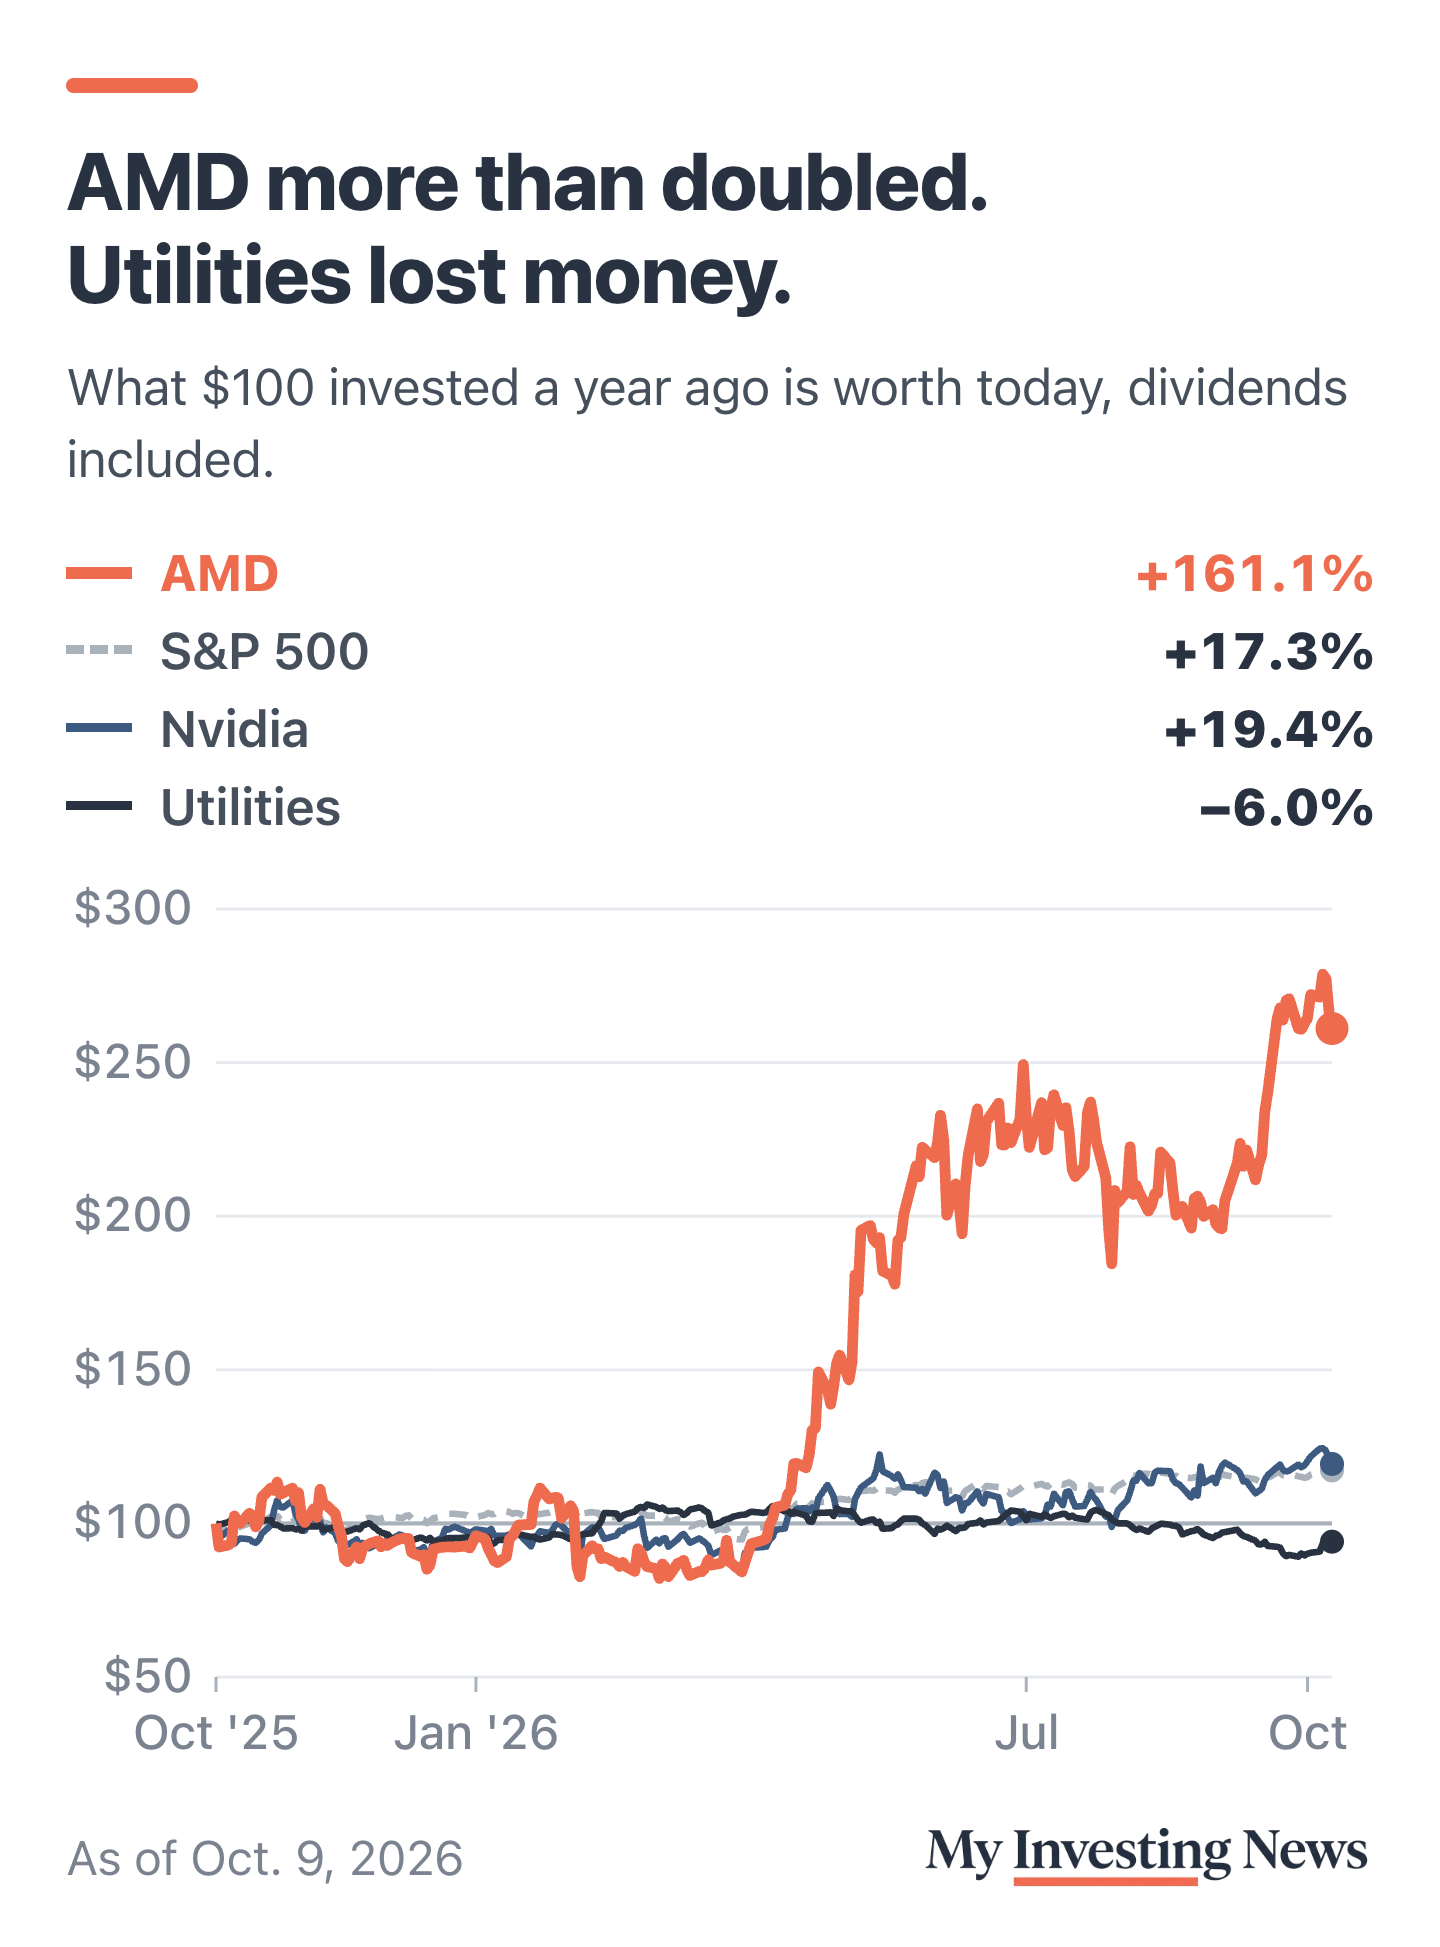
AMD’s run has fundamentals behind it. Second-quarter revenue reached $11.54B (+50.1% YoY), and Data Center revenue more than doubled to $6.72B, according to the company’s earnings release filed with the SEC. Management guided third-quarter revenue to ~$13B. Expectations are high, though. The stock trades at about 155 times trailing earnings, with a beta of 2.454.
Utilities Have Lagged the Broader Market
The Utilities Select Sector SPDR ETFXLU returned -5.95% over one year, including dividends. The SPDR S&P 500 ETFSPY returned 17.26% over the same stretch. That supports the direction of his claim. Year to date, though, XLU is down only 0.97% including dividends (3.0% on price alone). That looks like underperformance, and Roberts’ “really beaten up” goes further than the numbers do.
His other value pick, Berkshire HathawayBRK-B, trades near 13 times trailing earnings with a beta of 0.595. In the second quarter it became a net buyer of stocks for the first time in more than three years.
Last week, AMD fell 4.07% and NVIDIA fell 2%, while XLU rose 3.97%. That is the rotation he describes, showing up over five trading days. One week does not make a trend, and we did not confirm a cause for any of these moves.
The week before the episode, Oct. 2 to Oct. 9
His Bond Plan Depends on a Downturn
Lance Roberts described the sequence like this: “When that occurs, money’s going to go into Treasuries for safety. All those other yields are going to blow out, which means those prices go down.” Bond prices and yields move in opposite directions, so when yields jump, existing bonds lose value. The 10-year Treasury yield had already closed at its highest level in a year on Oct. 5.
Lance Roberts plans to sell Treasuries after collecting their yield, then rotate into discounted munis and corporate bonds. He used 2008 as his example. Lance Roberts said, “You’re going to see an ExxonMobil bond that’s trading at 80 cents on the dollar like we saw back in 2008, that’s a gift that you very rarely get.” That price is his memory of the period, and we could not verify it. When you buy a bond below face value and hold it to maturity, you collect the coupons and then the full face value at the end, as long as the issuer keeps paying. Schwab’s Liz Ann Sonders has said she favors investment-grade corporate debt over high-yield.
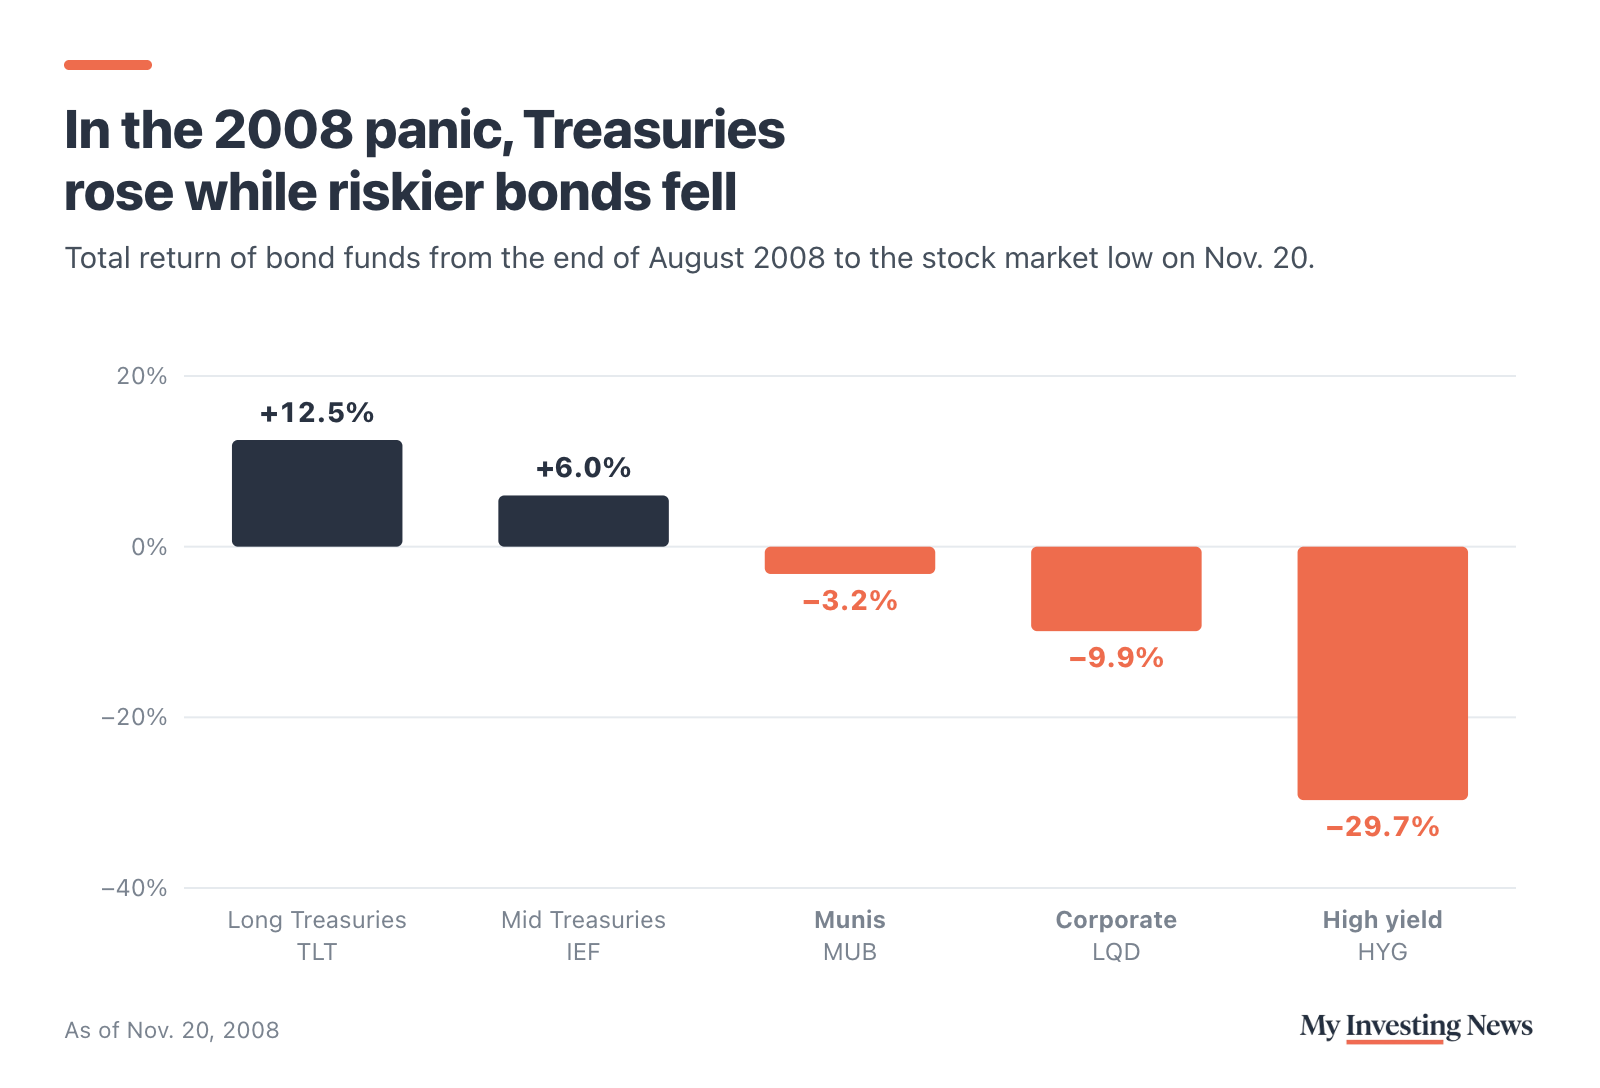
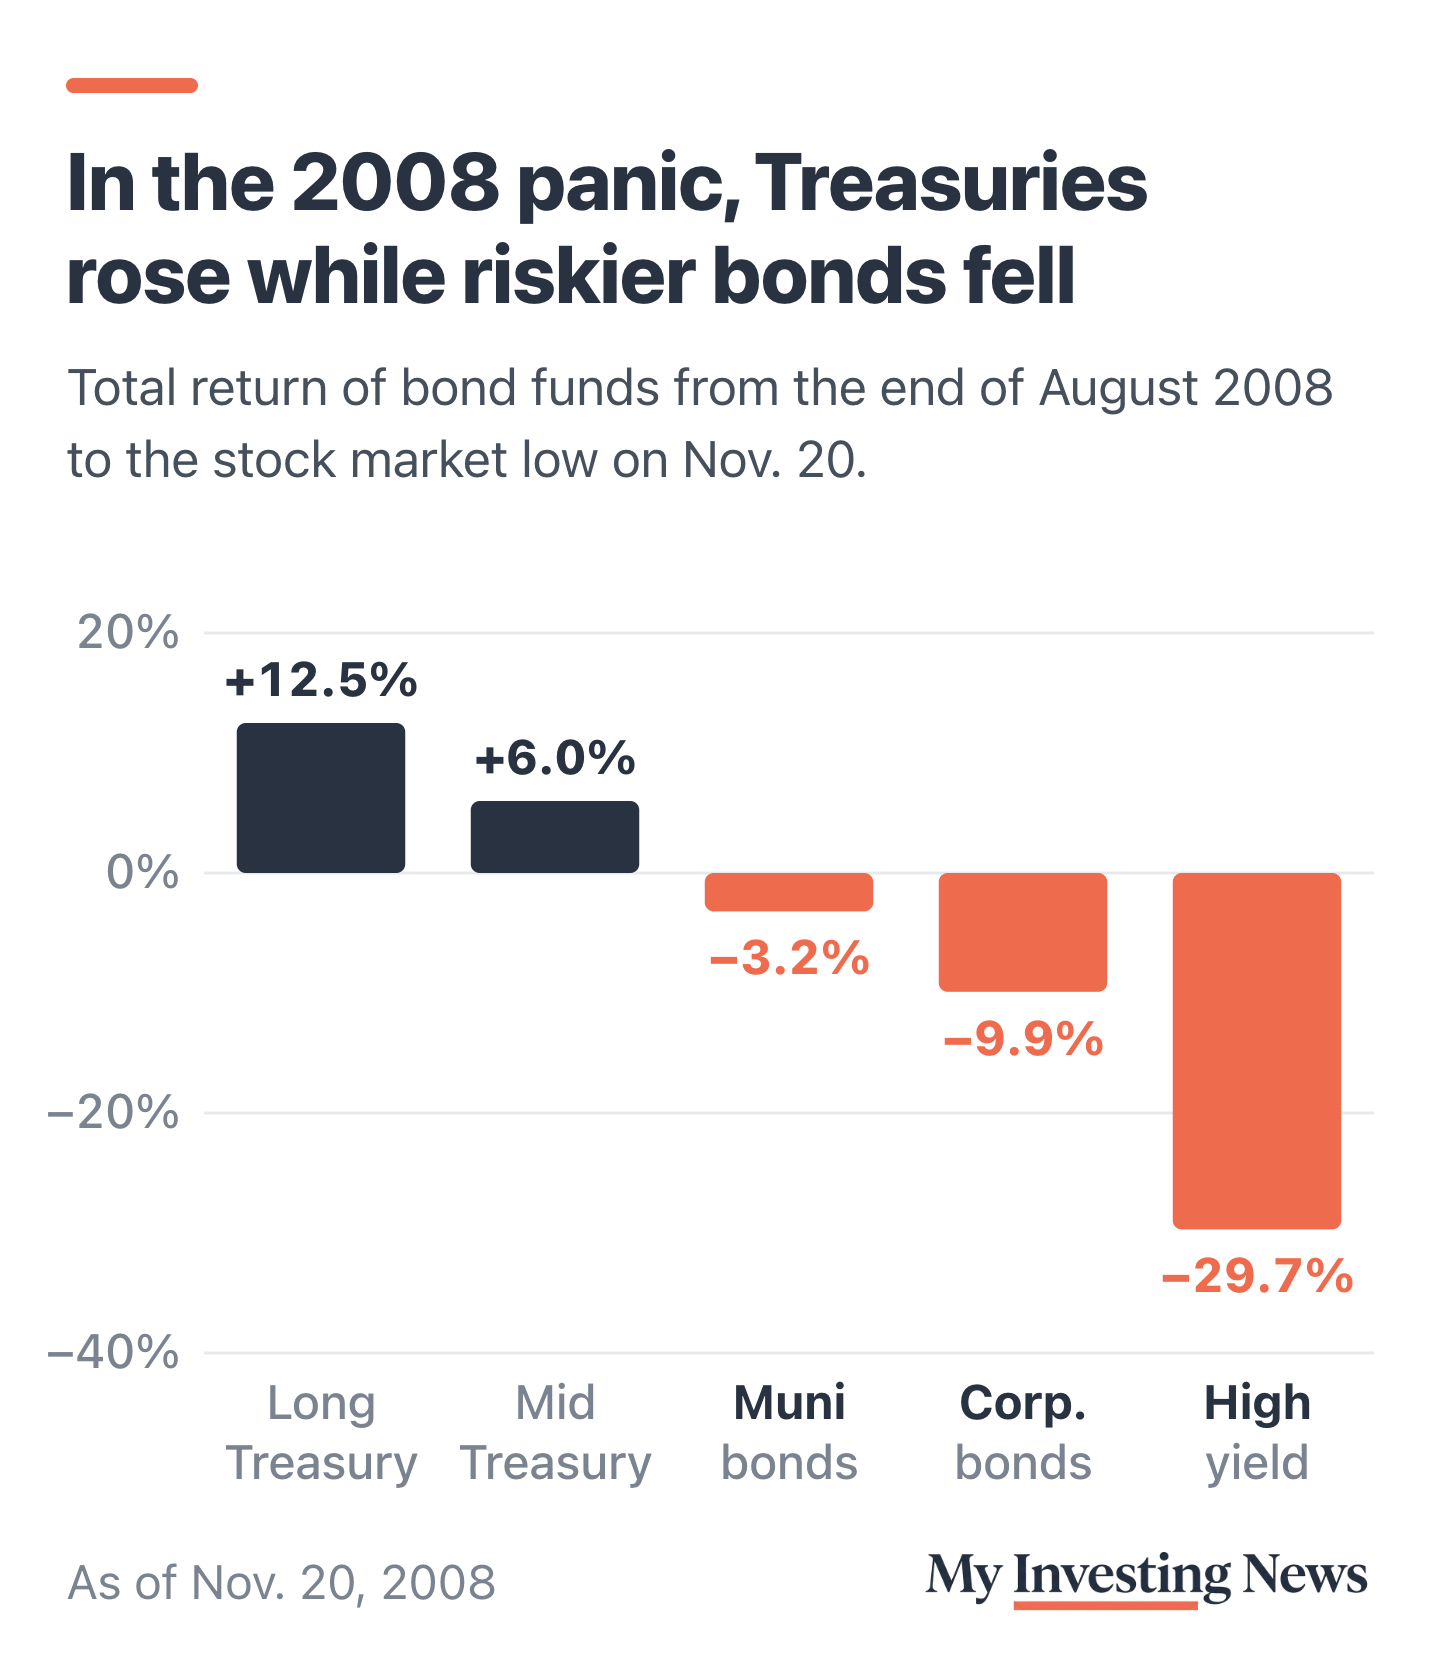
Adam Taggart said that “during the correction, the naked swimmers are going to die off” in the muni market. The line repeats the familiar saying about who is exposed when the tide goes out. Lance Roberts agreed. When Taggart added that the survivors would be at lower prices, Roberts answered, “Exactly, with higher yields.” Their argument is that stress sorts out the credits that only looked safe from the ones that are. The hard part is telling them apart in the middle of a panic, and neither man explained how an ordinary investor would do that.
On taxes: tax loss harvesting means selling holdings worth less than their purchase price so the realized losses can offset gains. IRS Publication 550 explains how gains and losses on investment property are calculated and reported, and bonds that have slipped below cost often come up in year-end reviews.
Limits Investors Should Weigh
- The whole bond thesis requires a correction. Roberts gave no firm timeframe (he said it could come “five years from now, three years from now, 10 years from now, whatever”), no trigger and no estimate of how deep it would be.
- Waiting costs something. Money parked in Treasuries is not invested anywhere else, and the wait can last a long time.
- A discounted bond only pays off if the issuer survives. Bonds trade at a discount because the market has doubts, and sometimes those doubts are justified.
- He is describing a portfolio he manages. His time horizon, strategy and risk tolerance are unknown and may not match yours.
Roberts has made real trades today and has a plan for a day that has not come. Those are different kinds of claims and should be considered differently.
Roberts took profits in AMD and Nvidia after big runs and added to Berkshire Hathaway and utilities, which he calls beaten up. His bigger plan is to buy discounted munis and corporate bonds after a correction that he says could be years away. The risk is the wait: he named no trigger, and a bond bought at a discount still loses if the issuer fails.