Where we heard itThe Investor’s Podcast Network, We Study Billionaires, episode TIP851, “HEICO Vs. TransDigm: Whose Aerospace Monopoly Is Better?” Released Oct. 4, 2026. Hosts: Kyle Grieve and Shawn O’Malley. Listen at TIP
On the October 4, 2026 episode of The Investor’s Podcast Network’s We Study Billionaires, titled “HEICO Vs. TransDigm: Whose Aerospace Monopoly Is Better?”, Kyle Grieve and Shawn O’Malley compared the debt levels of two aerospace parts makers with opposite capital structures. Figures below come from the episode audio.
Grieve said TransDigm GroupTDG has about $31 billion in net debt, with a net leverage ratio near 5.8 times. He put HEICOHEI at $2.3 billion and 1.6 times. He said EBITDA covers interest expense 3 times at TransDigm and 11 times at HEICO.
How the Podcast’s Numbers Compare With the Filings
We checked each figure against the companies’ filings using TransDigm’s quarter ended June 27, 2026 and HEICO’s quarter ended July 31, 2026. Leverage and coverage use trailing four-quarter EBITDA.
According to the filings, TransDigm’s net debt comes from $33.485 billion in total debt minus $2.773 billion in cash, against trailing EBITDA of $5.050 billion. HEICO’s comes from $2.541 billion in debt minus $240.959 million in cash, against EBITDA of $1.467 billion.
Grieve’s HEICO figures match the filings. His TransDigm figures match the company’s own yardstick, EBITDA As Defined, which adds back acquisition costs and stock-based pay: about 5.8 times leverage and 2.8 times interest coverage. On plain EBITDA, leverage is 6.1 times and coverage 2.7 times, a slightly worse debt position than described.
A $9.8 Billion Equity Gap the Episode Left Out
The segment never got to the most striking number in either filing. TransDigm reported a total stockholders’ deficit of $9.809 billion, meaning its shareholder equity is negative. HEICO reported positive equity of $4.948 billion.
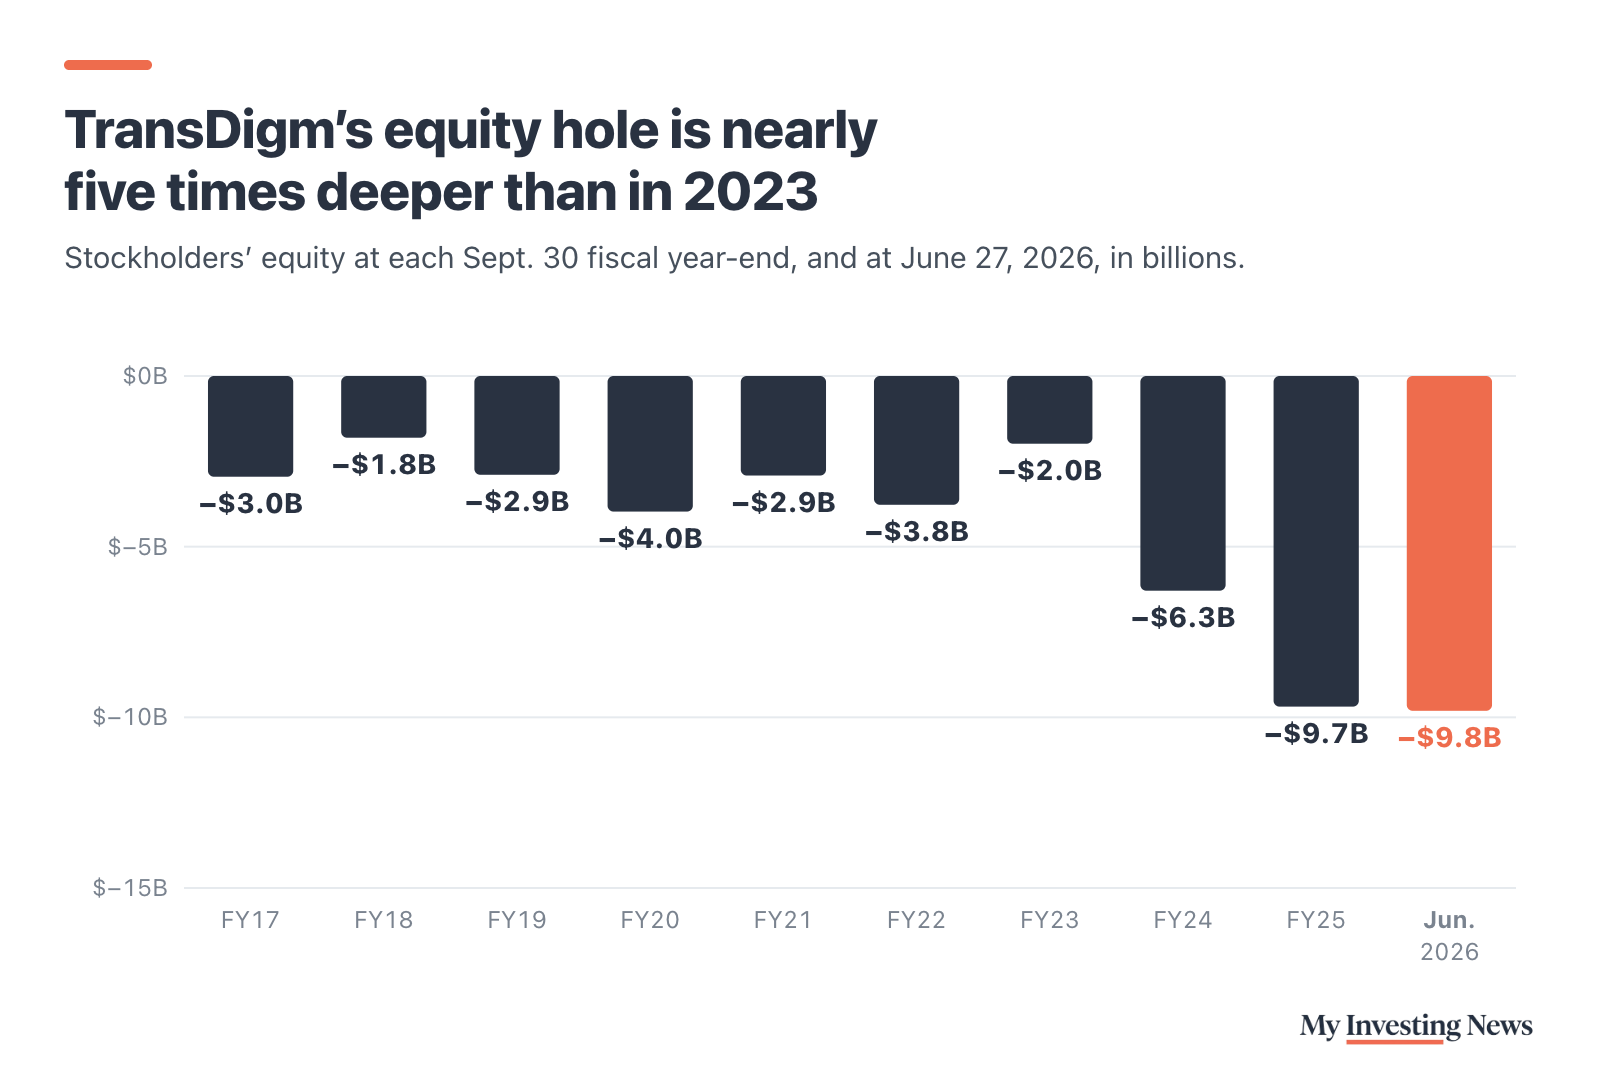
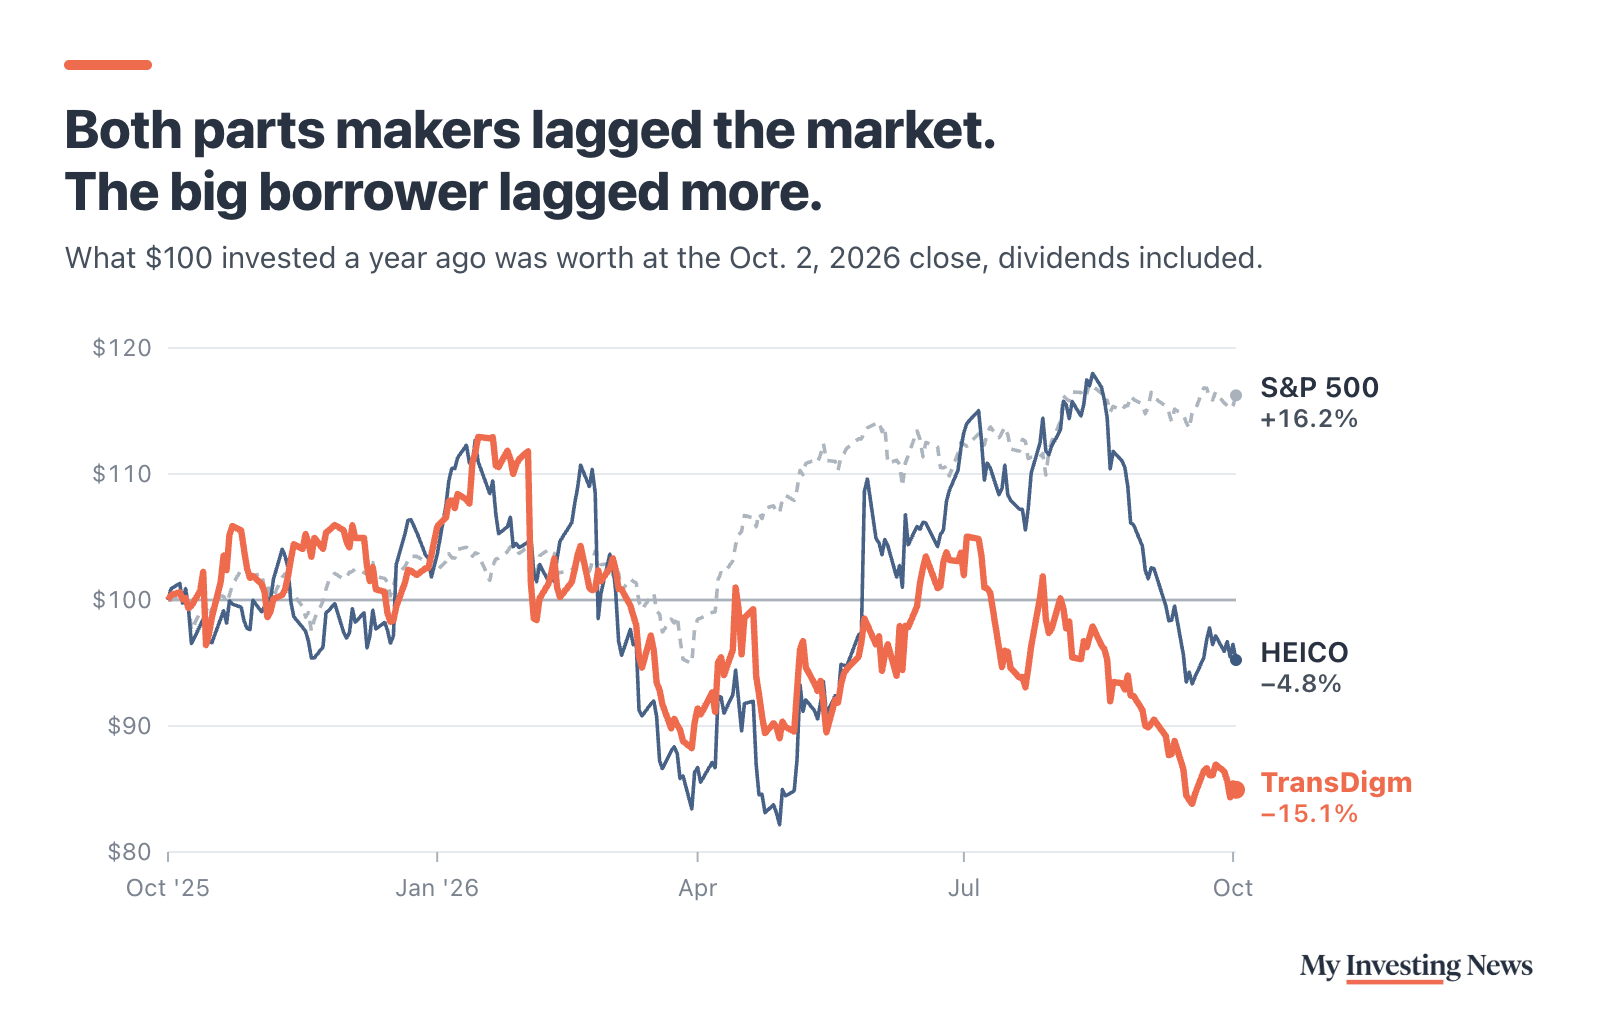
Negative equity results from years of buybacks and special dividends funded with borrowed money exceeding retained earnings. TransDigm remains profitable and pays interest, but has chosen to send capital to shareholders while funding itself with debt. HEICO has built equity over time. At the October 2 close, the market valued TransDigm at about $60.3 billion versus about $35.7 billion for HEICO, counting both of HEICO’s share classes.
The two balance sheets, latest quarter
Grieve Praised TransDigm’s Deal Playbook
Grieve cited TransDigm’s 2019 purchase of Esterline Technologies as an example of its acquisition strategy. He said TransDigm sold about a quarter of the business to sell off non-aerospace units, then applied price increases, cost reductions, and new business development. According to Grieve, Esterline’s EBITDA margins doubled over a 5-year period.
O’Malley called the debt figure “pretty scary.” The hosts still thought highly enough of the business to add it to their portfolio for a while: “We did add TransDigm to the Intrinsic Value Portfolio for a period of time,” Grieve said. That tension between concerning debt and a business they admire runs through the whole discussion.
A Co-Host’s Natural Monopoly Argument
O’Malley said that natural monopolies form when one company far outperforms competitors, citing TransDigm as an example. He mentioned a House Oversight Committee hearing where lawmakers tried to understand why companies like TransDigm face no competition, concluding that if government cannot step in in such businesses, it has limited power to constrain pricing. This is the co-host’s view.
What to Watch at Both Companies
Both companies sell proprietary aircraft parts, mostly aftermarket, and face high barriers to entry. TransDigm’s components are used on nearly all commercial and military aircraft in service. HEICO runs two segments and acquires niche businesses. TransDigm borrows heavily and returns cash aggressively; HEICO funds growth from earnings and keeps low debt. If aftermarket demand slows or refinancing costs rise, higher leverage poses greater risk.
Two things are worth tracking. First, whether TransDigm’s 2.7x interest coverage improves or slips. Second, whether HEICO starts buying companies faster, since its 1.6x leverage leaves plenty of room to borrow.
Grieve and O’Malley admire both businesses but give HEICO the edge on its balance sheet, and the filings back them up: TransDigm carries $30.7 billion in net debt and negative equity of $9.8 billion, while HEICO carries $2.3 billion and positive equity. The key risk is TransDigm’s leverage: if aftermarket demand slows or refinancing costs rise, its debt load would bite far harder than HEICO’s.