Where we heard itBloomberg TV, Horizons Middle East & Africa, Oct. 2, 2026, live from Dubai. Speaker: Amol Shitole, fixed income head at Mashreq Capital. Watch the segment
Amol Shitole, fixed income head at Mashreq Capital, went on Bloomberg TV on October 2 with a contrarian bond call. “We expect 10-year US Treasury yields to touch 4.6% in 12 months time. I think significant amount of bad news is already in the price. All the news about deficits, debt supply, which is largely reflected in the current yields. And I think investors are getting compensated for taking the duration risk now versus any time in the last five years,” Amol Shitole said.
The ten-year Treasury yield closed at 5.28% on October 2, 2026. On September 30, 2026, it closed at 5.29%, its highest level of the trailing year. The yield was up 0.49 percentage points over the past month. Shitole is calling for a fall from near a one-year high after sharp increases.
His Inflation Number Checks Out
“There is a significant disconnect between inflation and yields. In 2022, we had US inflation at 9% and 10-year US Treasury yields were at 3%. Now we have inflation back down to 3.4% and Treasury yields are at 5.25%. I think one of it is wrong and I think it’s yields. They have to come back and follow inflation numbers in my view,” Shitole said.
The Consumer Price Index rose 3.4% in the year through August 2026, the latest month available. His description of current inflation is accurate.
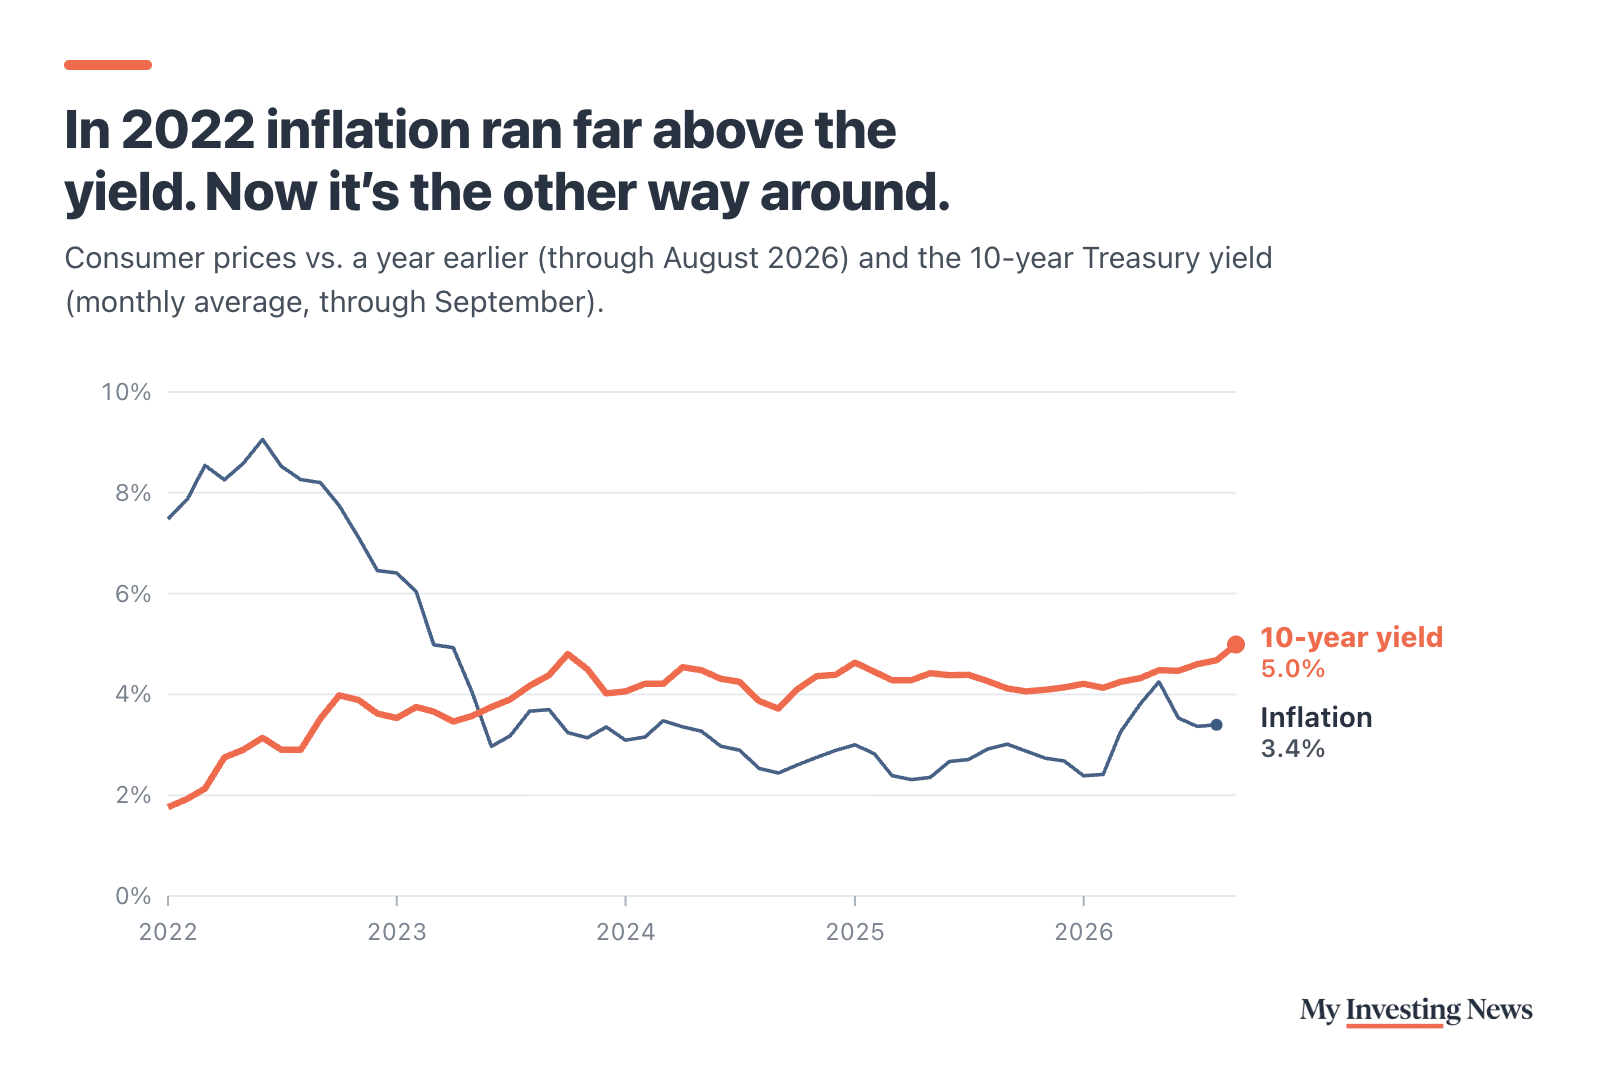
His 2022 comparison also holds up. Inflation peaked at 9.1% in June 2022, when the 10-year yield averaged about 3.1%.
Bond Market Pricing Tells a Different Story
Shitole says yields must fall to catch up with inflation. But the bond market has priced in an inflation outlook well below the reported rate. As of October 2, 2026, the ten-year breakeven inflation rate was 2.36%, close to the five-year breakeven of 2.37%. The real ten-year yield was 2.92%.
The breakeven is the inflation rate the market expects; the real yield is what a Treasury pays above that. With expectations anchored below reported inflation, today’s high nominal yield comes mostly from a high real yield. Investors demand more pay to lend for ten years, regardless of inflation. This weakens his reasoning: a yield driven by the real component can stay high even with moderate reported inflation.
Where rates stood on Oct. 2
Real yields can fall, so his 4.6% target remains possible. His point that bad news is already priced in is a separate argument. What the data shows is that his stated reason doesn’t match what the bond market is actually pricing.
His Fed Read Came Before the Jobs Report
“We expect a hold in October. I mean, market agrees to that as well. Probability of rate hike have gone down to inside 30% today. At the beginning of the week it was 70%,” Shitole said.
He spoke on the morning of October 2 in Dubai, before the U.S. September jobs report. Polymarket’s October rate-hike contract traded near 24.5% at the time, down from about 66% on September 28, so his numbers matched the market.
Later on October 2, Polymarket put the odds of no change at the October Federal Open Market Committee meeting at 81.5%. It put the odds of a quarter-point increase at 18.5%. These contracts trade on a scale from 0 to 1. Over the past week, the price of the October increase contract fell 0.44, and the price of the no-change contract rose 0.45. The jobs report pushed the odds of an increase even lower than when Shitole spoke. These numbers are market-implied probabilities based on where traders have placed real money. They reflect trader positioning, separate from official Fed guidance. Business Insider reported that stocks rallied Friday after a dismal jobs report eased rate-hike expectations.
Give the Call Credit, Then Test the Reasoning
Shitole made a specific, testable call while the yield sat near a one-year high. His read on near-term Fed expectations is accurate. His inflation figure is accurate. The weak link is his reasoning: the bond market tells a different story.
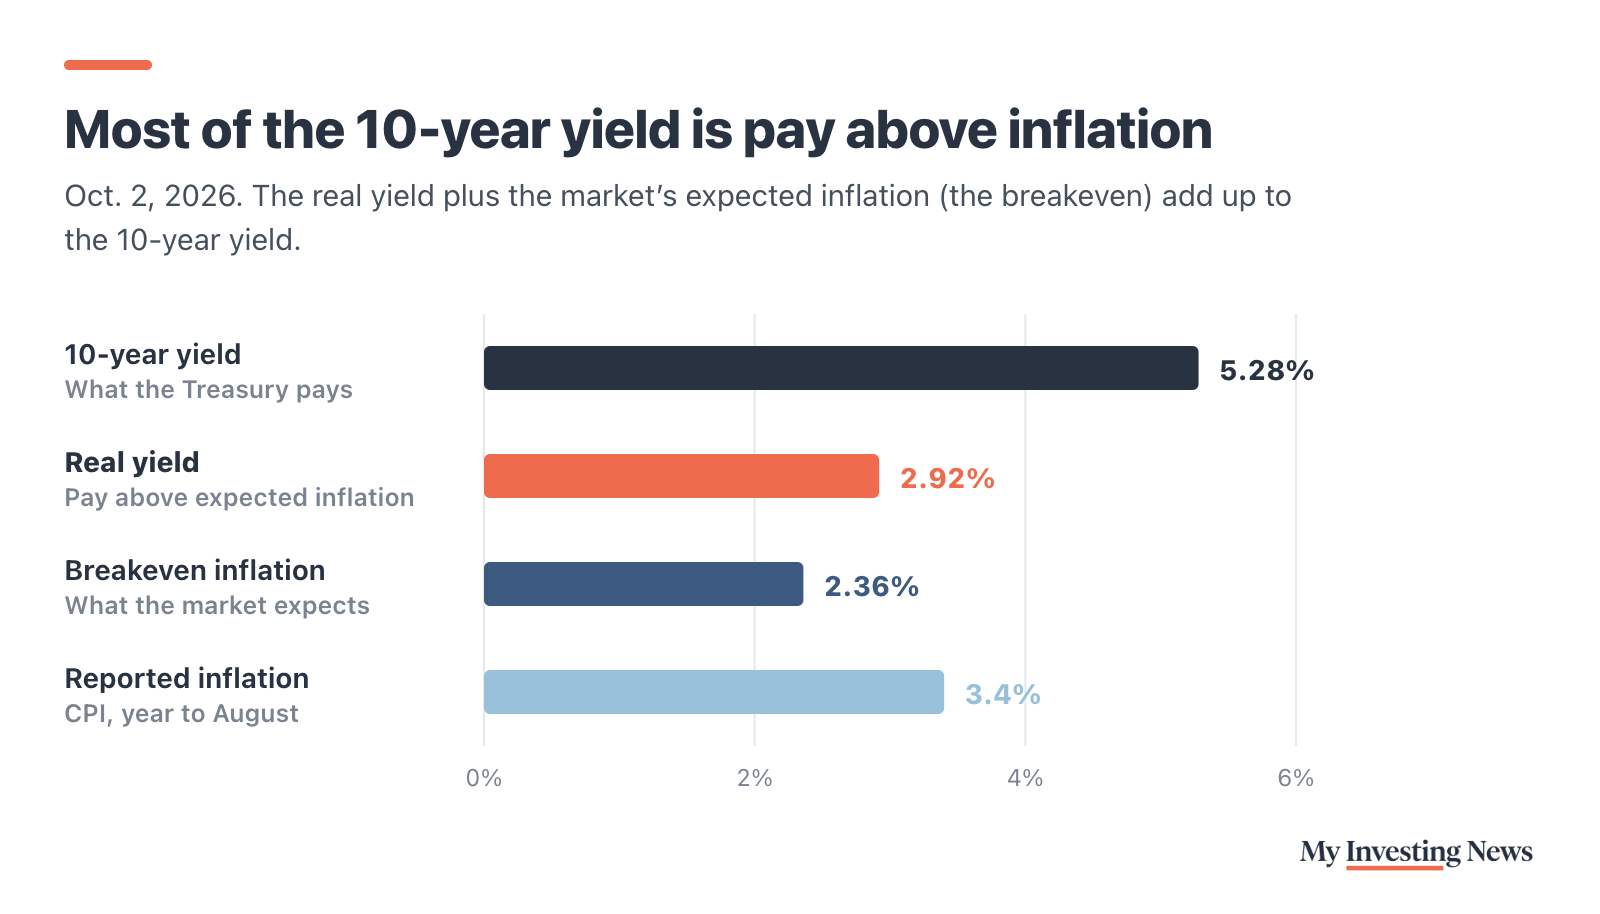
Breakevens point to anchored inflation expectations, while the real yield carries most of the weight.
Shitole expects the 10-year yield to fall to 4.6% within 12 months, arguing that yields have run too far above 3.4% inflation and that bad news is already priced in. The risk to his reasoning is that the market expects only about 2.4% inflation, so most of today’s 5.28% yield is real return, which can stay high even if inflation cools.