Where we heard itBloomberg TV, “Insight with Haslinda Amin,” Oct. 2, 2026, recorded in Singapore. Speaker: Christian Stracke, president of PIMCO, interviewed by Paul Allen.
PIMCO president Christian Stracke told Bloomberg that rising real rates are driving Treasury yields higher. “It’s the rise in real rates that has pulled yields higher. It’s not a rise in inflation expectations,” he said. Bond market data supports this view.
Three Numbers Show What Is Driving Yields
Treasury curve readings from October 1, 2026: the nominal ten-year yield was 5.24%, the real ten-year yield 2.88%, putting the ten-year breakeven inflation rate at 2.36%. The five-year breakeven matched at 2.36%, with nominal five-year at 5.01% and real five-year at 2.65%.
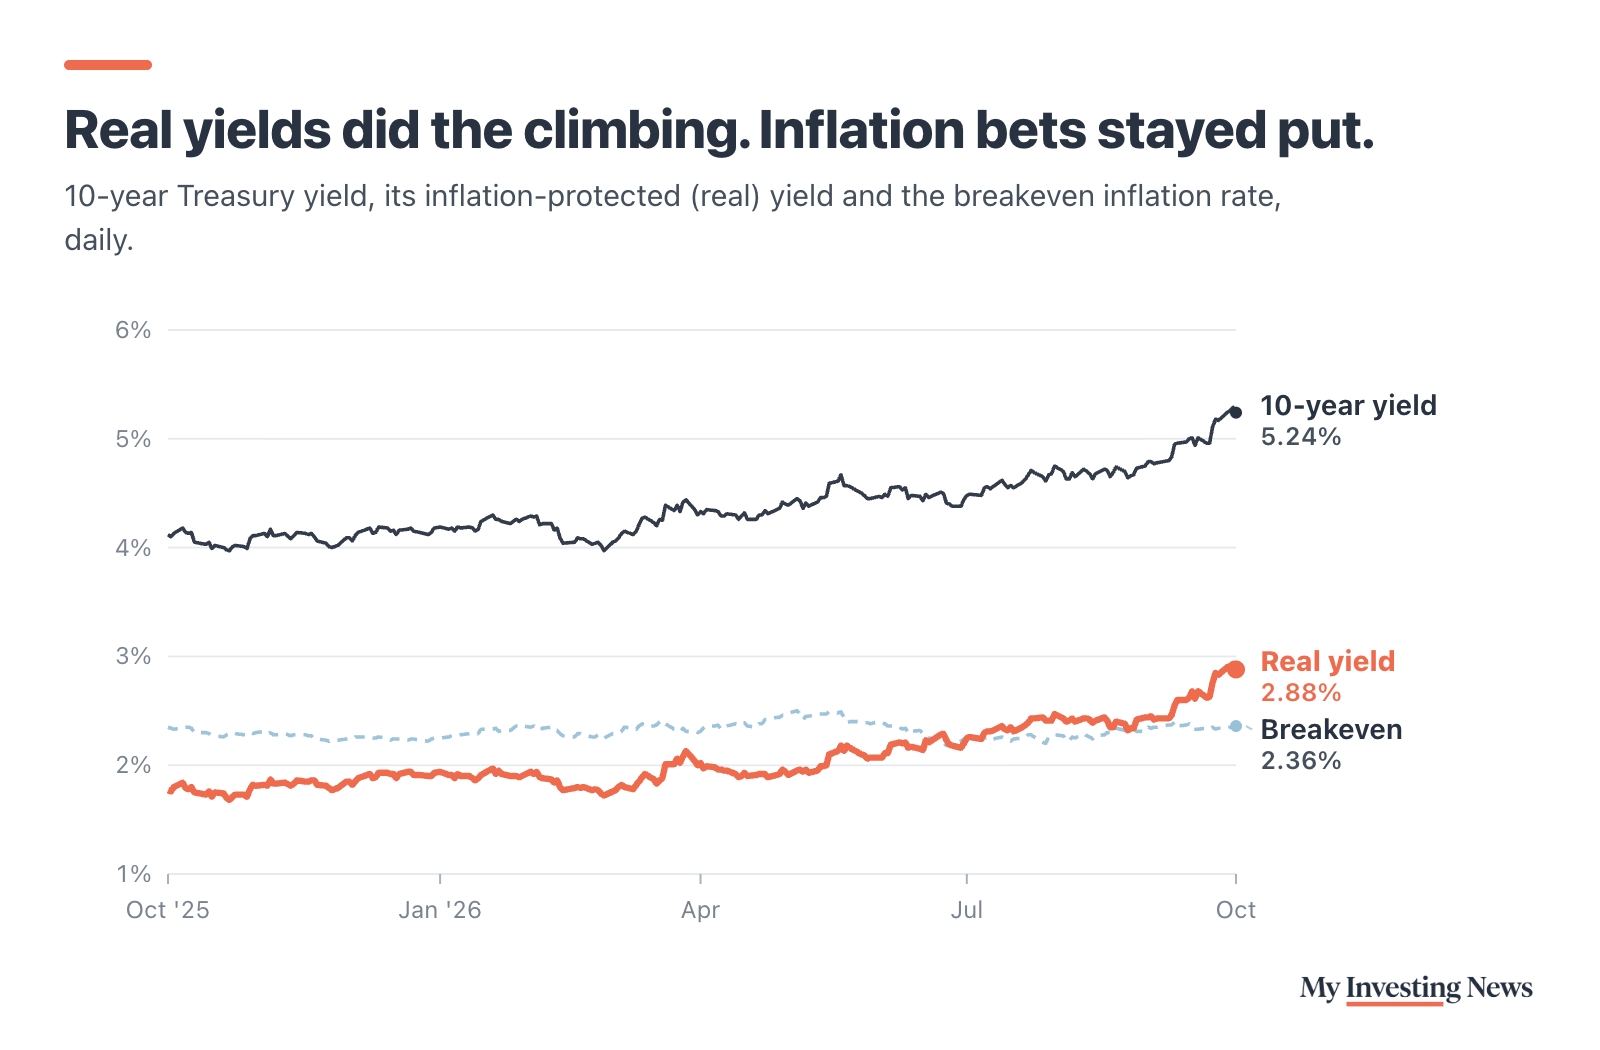
The nominal yield is what a Treasury pays; the real yield is what it pays after expected inflation is removed. The breakeven shows how much inflation the market has priced in. When nominal yields climb and the breakeven stays flat, the increase comes from the real side: investors are paying more for capital itself. Matching breakevens across maturities signal anchored inflation expectations.
AI Spending Is Pushing Up the Price of Capital
Stracke attributes the move to AI. Hyperscalers and technology companies building AI infrastructure are creating heavy capital demand, increasing investment-grade spreads without credit deterioration. ING sees the AI boom pushing yields higher beyond corporate borrowing, and Man Group warned that elevated yields risk cracking AI capex.
If Stracke is right, a corporate capital spending cycle is now setting the cost of money. That is a different investing problem from inflation, and it comes with its own risks.
Carry Trades Are Unwinding One After Another
Christian Stracke said “the market is saying to the Fed and really to all the rest of market participants” that “there’s a deleveraging going on in the system,” with “one after another after another of popular carry trades in the system coming down and getting de-risked and deleveraged.”
Why Steady Breakevens Point to Fed Credibility
Christian Stracke said “the market is saying that the Fed has credibility,” adding that “the Fed will do what it needs to do to get inflation down to the target. That is an extremely healthy indicator.” He linked that view to remarks from Minneapolis Fed President Neel Kashkari. The matching 2.36% breakevens are the evidence behind his claim.
Treasury readings, Oct. 1, 2026
Stracke’s Fed Outlook Comes With a Caveat
“Certainly looks like we’ve got at least one more to come from the Fed. How much more beyond that is really going to be driven by a lot of things that are frankly uncertain,” Stracke said. Reuters reports Fed policymakers lean against an October hike.
Where Credit Stress Is Showing Up First
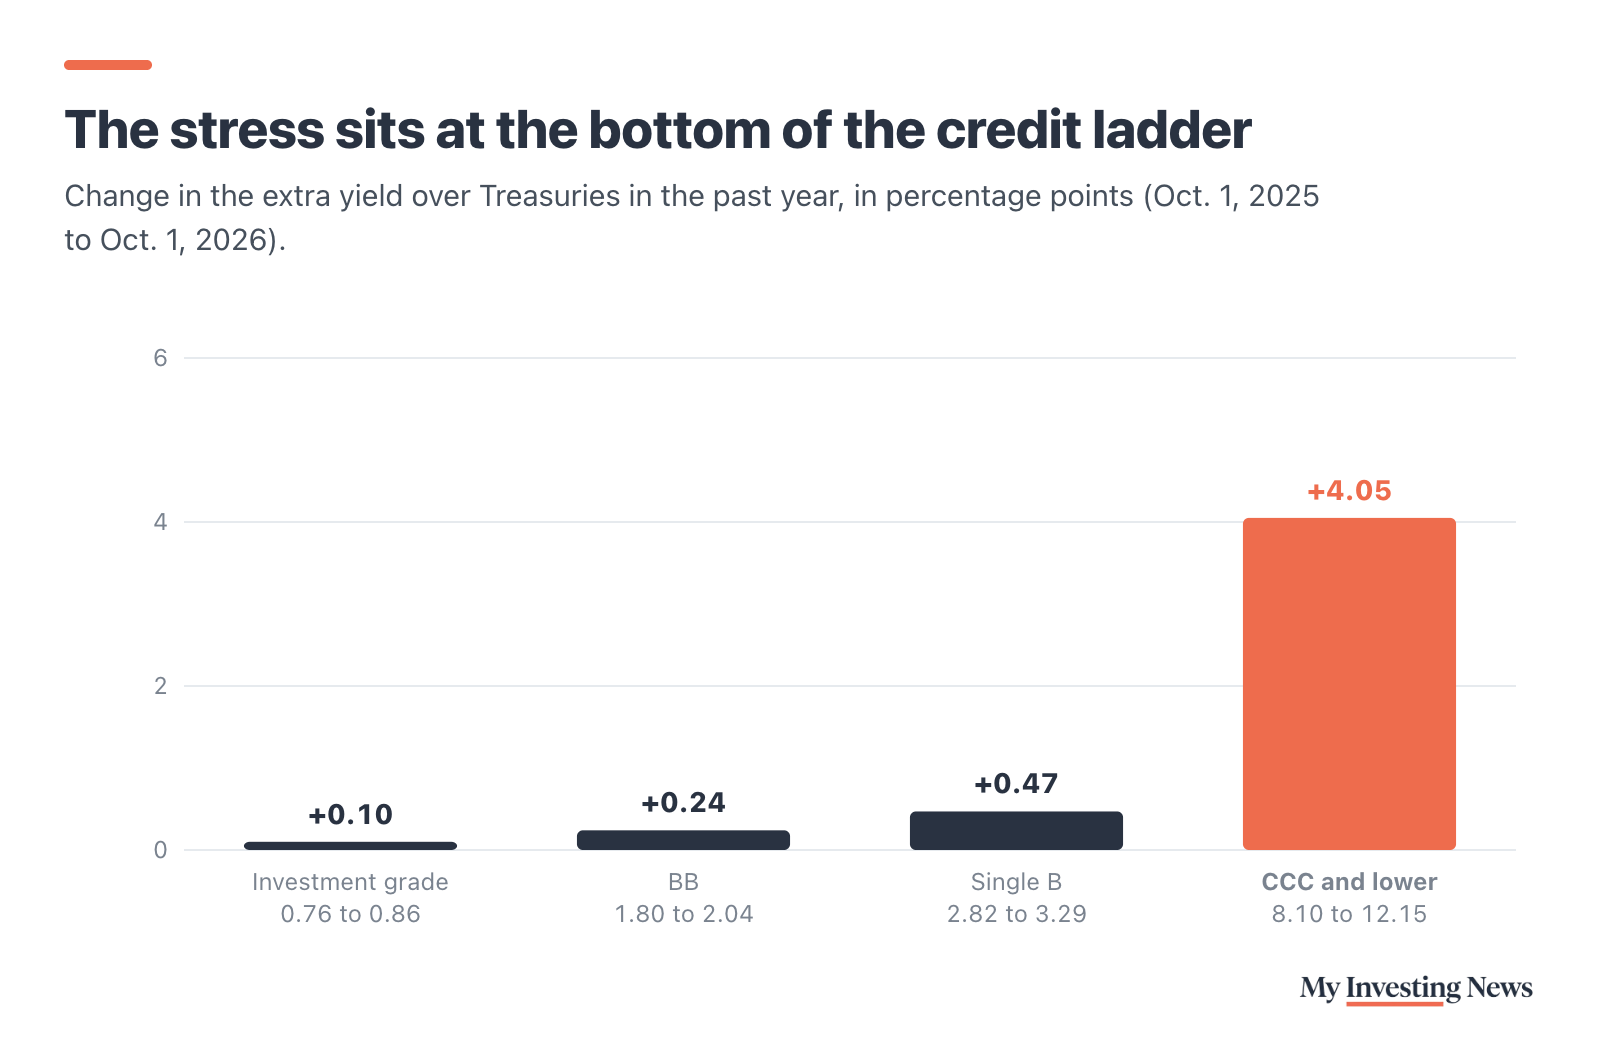
Stracke outlined a scenario: “If there are four rate hikes, it is going to be quite difficult for lower down the capital structure claims, particularly in the corporate market. And that’s [what] we’re already starting to see in triple Cs and lower single Bs, bank loans, high yield.” Direct lending, he added, “is going to be having some problems as well.” Low-rated borrowers carry heavy debt, much floating-rate or due for refinancing soon. Rising funding costs squeeze cash flow and reduce room to absorb a slowdown.
A Bond Manager Makes the Case for Bonds
Stracke said “balancing portfolios into this high quality, high yielding fixed income, in our view, is a pretty interesting alternative, especially for portfolios that have been loaded up on a number of different kinds of risk.” He cited a 5.3% return on a 10-year Treasury, a 6.5% return on an investment-grade credit portfolio and a 7.5% return on a more diversified portfolio of high-quality bonds. PIMCO, one of the world’s largest fixed income managers, has clear incentive to recommend the asset class it specializes in.
What Investors Should Watch Next
Rising yields as a real-rates story changes the bonds-versus-stocks calculus. High-quality Treasuries now offer real returns well above anchored inflation. Stock valuations face a higher discount rate tied to an AI spending cycle with no clear end. Stracke reasons that stock-heavy portfolios could benefit from adding high-quality fixed income. Track: whether the breakeven stays anchored, whether real yields keep rising, whether AI spending plans get raised again, and whether stress in lowest-rated credit spreads to higher-rated debt.
Stracke blames AI companies’ appetite for capital for the rise in yields, and the data back him: the real yield rose about as much as the 10-year while the breakeven barely moved. He expects at least one more Fed hike and sees high-quality bonds as a good counterweight for portfolios heavy in risk. The risk is more hikes than that, which would hit the lowest-rated borrowers hardest, where spreads have already widened the most.