Where we heard itCNBC’s Squawk Box, Oct. 6, 2026. Speaker: Amy Wu Silverman, head of derivatives strategy at RBC Capital Markets. Watch the clip at CNBC
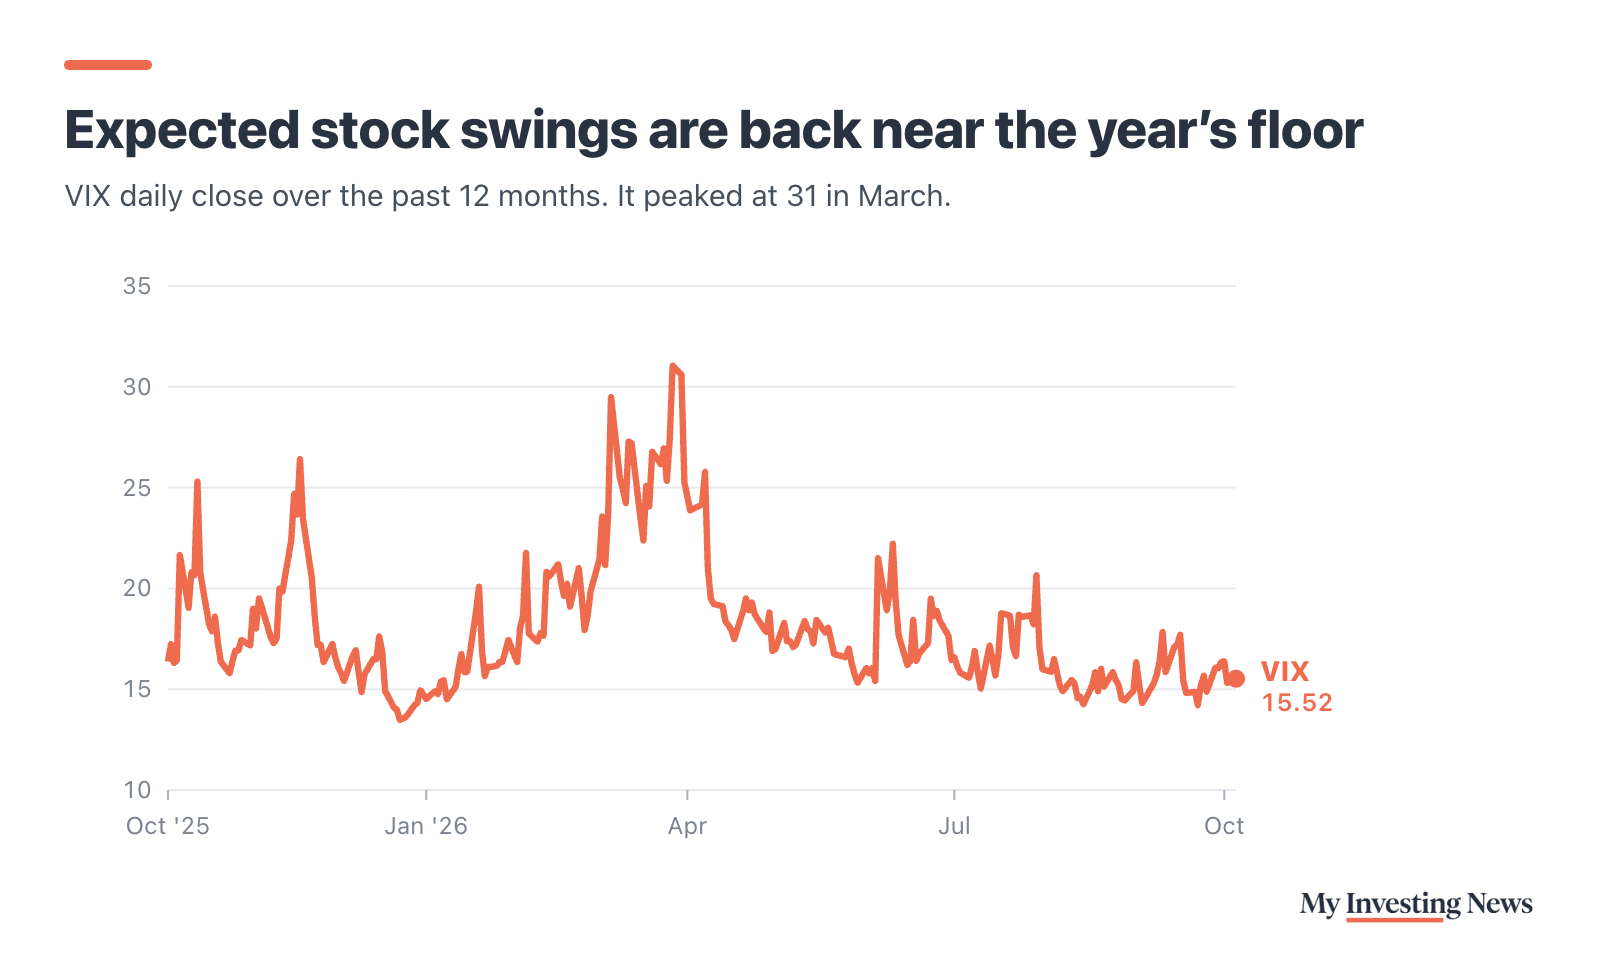
The Cboe Volatility Index (the VIX), which measures expected 30-day moves in the S&P 500, closed at 15.52 on October 5, 2026. That close sits in the 17.8 percentile of its trailing twelve months: only 17.8% of daily closes over that span were lower. Federal Reserve Bank of St. Louis data show that range running from a low of 13.47 on December 24, 2025 to a high of 31.05 on March 27, 2026. The twelve-month average is 18.101. Expected volatility is priced near the bottom of where it has traded over the past year.
Amy Wu Silverman, head of derivatives strategy at RBC Capital Markets, says the calm is a mistake. She explained her view in a Squawk Box appearance on CNBC on Tuesday.
Where Wu Silverman Sees the Mispricing
Wu Silverman’s main claim: the derivatives market has not repriced for severe artificial intelligence outcomes. Using a flooding comparison, she noted a homeowner would act differently if flood risk rose to 20%. Options traders have not made the same adjustment for AI. The derivatives market shows “no change”. Positioning remains focused on right tail risk and AI momentum. She called the complete absence of “p doom” pricing (the perceived odds of extreme AI outcomes) the single most mispriced thing she sees.
Her claim is a strategist’s read of market positioning. No public data tracks it independently.
Index Gains Rest on a Narrow Base
Asked whether the market’s gains have concentrated in the AI trade among a few companies, Wu Silverman agreed, calling it “very narrow breadth” in the market.
The SPDR S&P 500 ETF TrustSPY closed at $777.22 on October 7, 2026, up 14.0% year to date (14.9% including dividends).
Debt Risk at the Top of the House
The most concrete risk lies in what she called the “top of the house”. Those companies are issuing more debt and are more sensitive to interest rates. A few stumbles there would spread problems across the entire market.
The calm in numbers, Oct. 5 close
The 10-year Treasury yield was 5.31% on Monday, October 5, 2026.
Bond Volatility Keeps Rising, She Says
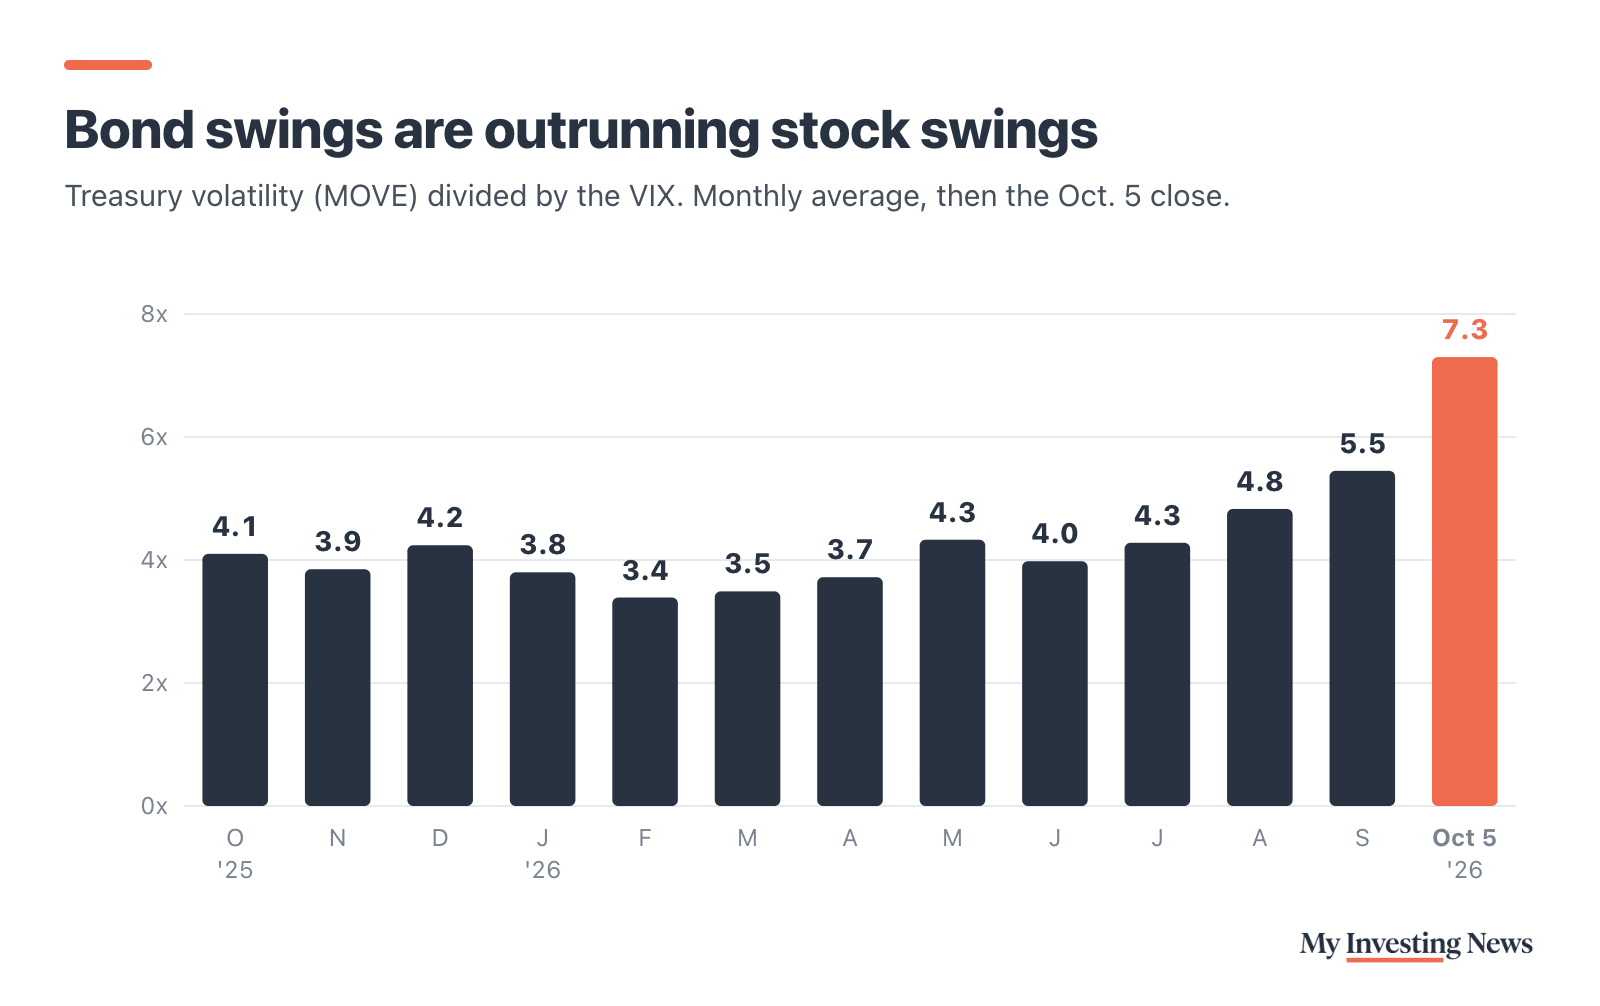
Wu Silverman also points to bond market volatility rising relative to stock volatility. She cited the ratio between expected Treasury volatility (the MOVE index) and the VIX, saying it keeps getting “higher and higher”.
The 10-year yield’s twelve-month high was 5.31% on October 5, 2026, and its low was 3.97%, reached on October 22, 2025 and again on February 27, 2026, according to St. Louis Fed data. That range shows how widely rates have moved over the past twelve months.
One Number, Two Readings
A VIX close of 15.52 near the bottom of its twelve-month range is true. Wu Silverman’s argument that this calm is dangerous rests on options positioning, narrow breadth, rising corporate debt, and bond volatility, and investors differ on whether the calm is justified or complacent. They’re reading the same number differently based on how much weight they give to the risks she says the options market has left out.
Wu Silverman thinks the low VIX understates real dangers: options traders have priced in almost no chance of a severe AI shock, gains rest on a few big companies, and bond-market swings keep growing relative to stocks. She argues it is a matter of time before that volatility spills into stocks, though the calm could also last longer than her warning implies.