Where we heard itCNBC’s Squawk Box, Oct. 6, 2026, the morning the deal closed. Speaker: Rich Greenfield, co-founder of LightShed Partners.
The combination of Paramount SkydanceSKYD with Warner Bros. Discovery closed on October 6, and Rich Greenfield, co-founder of LightShed Partners, has already said how he thinks it should be judged. The combined company is now called Skydance. In a CNBC appearance, Greenfield said the real challenge for the merged company is whether it can generate free cash flow. His point was that investors should watch the cash the business produces and pay less attention to earnings before interest, taxes, depreciation and amortization (EBITDA), a figure management controls.
“You can manipulate EBITDA. What you can’t manipulate is cash,” Greenfield said. He asked whether the combined company can actually generate and grow sustained cash flow, and he pointed to seven times leverage as the reason the question matters so much to investors. Lenders get paid in cash, and an adjusted earnings figure covers no interest payments.
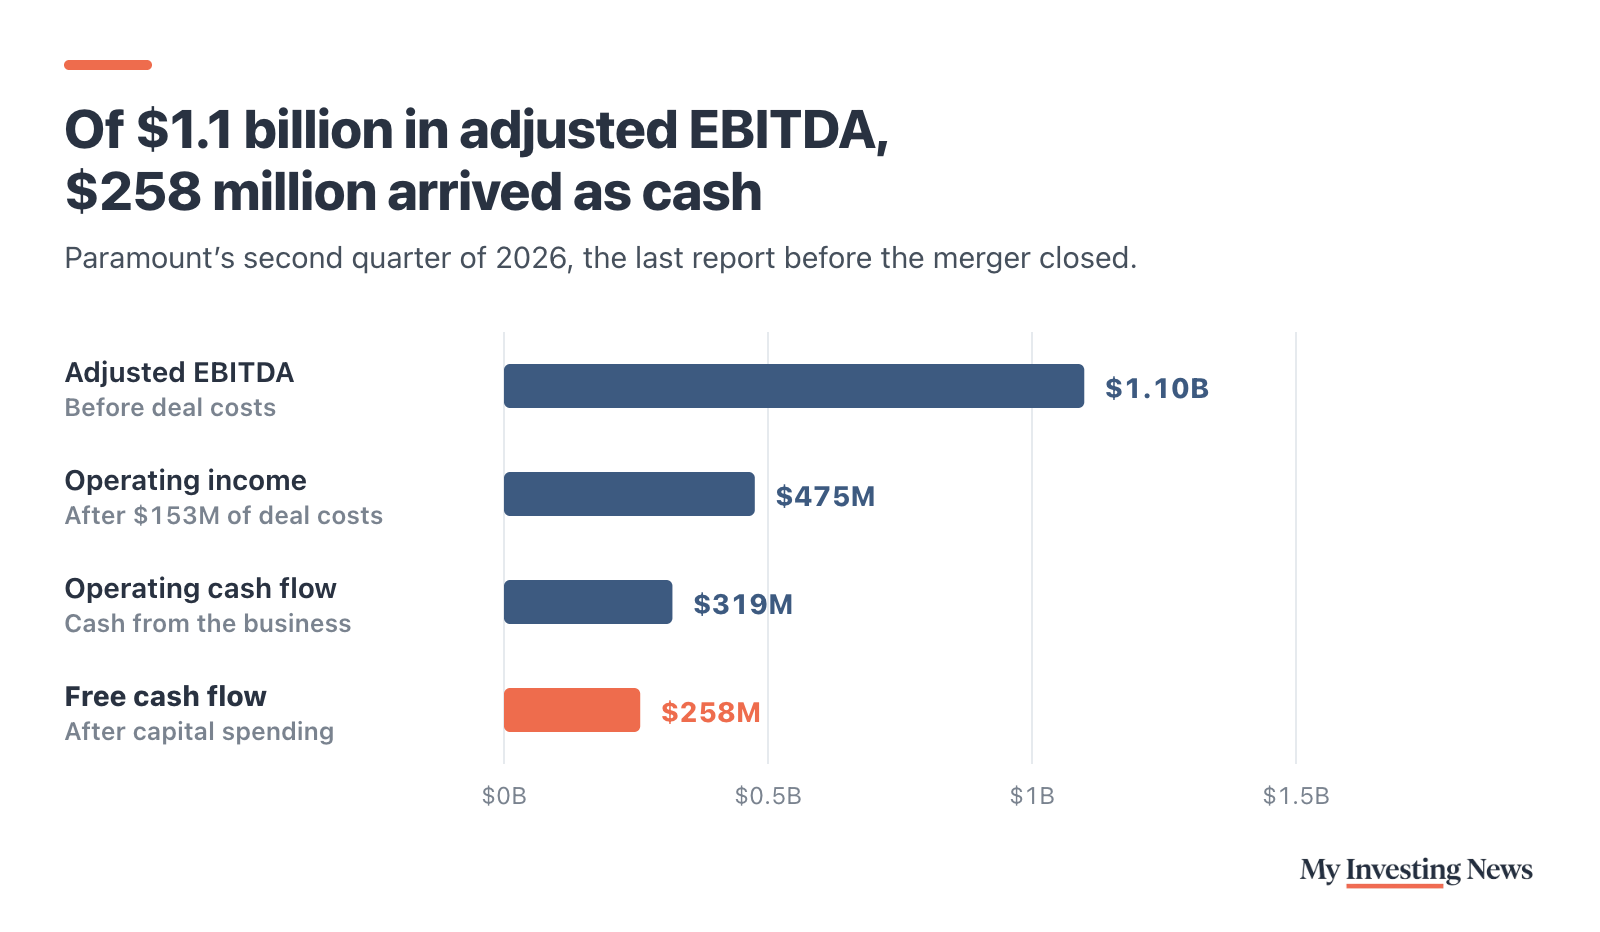
Paramount’s own results already showed how wide that gap can get. In its second-quarter 2026 earnings release filed with the SEC, Paramount reported companywide adjusted EBITDA of $1.10B. GAAP operating income was $475M after including $153M of transaction-related costs.
How the Stock Has Performed So Far
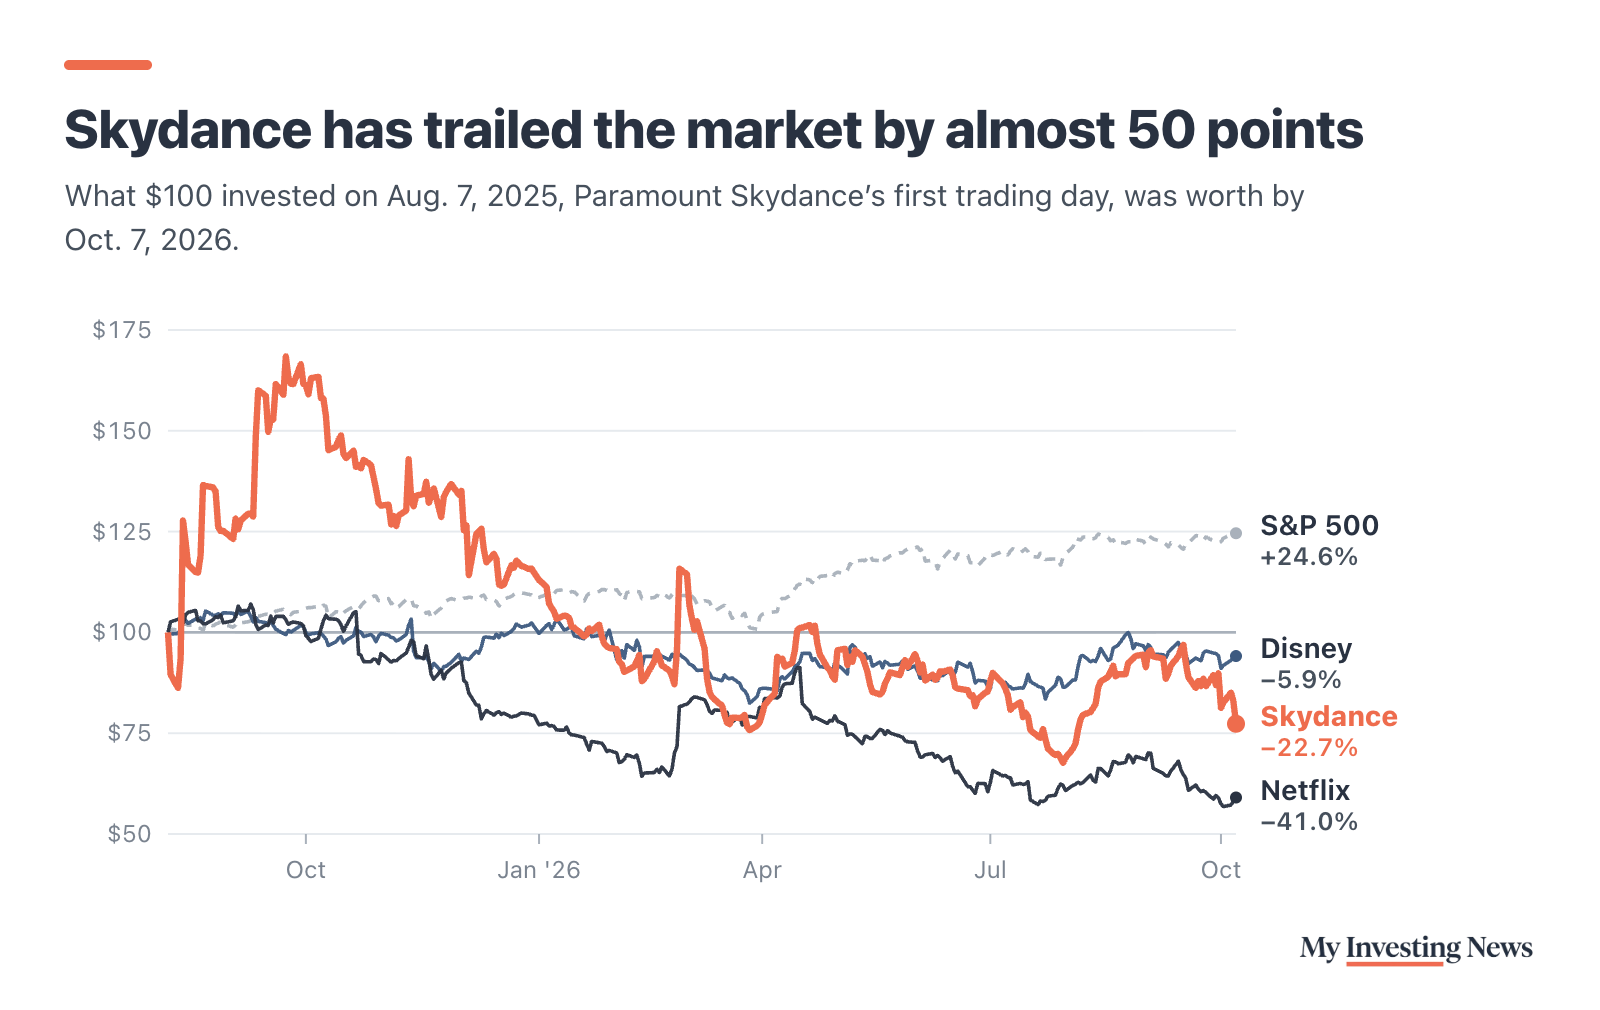
Paramount Skydance shares had fallen about 48% over the past twelve months and about 26% year to date, including dividends. Over the past month they declined about 10%. All of those figures run through the October 5, 2026 close, the day before the deal closed. The company was formed in August 2025, so a longer comparison is not available. The shares now trade on the New York Stock Exchange as SKYD and closed at $8.89 on October 7.
A Starting Line This Company Has Seen Before
Greenfield also cited what he called the magic number. He said the total EBITDA of the combined Warner Bros. Discovery and Paramount is once again at $12 billion. According to Greenfield, management forecasts that figure reaching $18 billion by 2030.
The words “once again” refer to history: Warner Bros. Discovery started out at that same EBITDA level when it was formed in 2022. Before this deal, its EBITDA had fallen to $9 billion.
Under Greenfield’s analysis, the bigger combined company starts at the same figure the smaller company started at when it was created. To hit the plan, it has to reach a level that neither company has ever reached.
Why the Earlier Version Lost Ground
Greenfield gave a general explanation for that decline. He said the core business eroded faster than synergies could be piled on. He named David Ellison and Ynon Kreiz as the executives who now face that challenge. In his view, this management team has to prove it can grow earnings and actually generate free cash flow, according to CNBC.
The deal at closing
Rising Deal Costs Add Pressure on Debt Paydown
Greenfield also said the transaction got more expensive, and that this puts more urgency on paying down debt. He offered his own guess that the company would soon begin cutting employees to reduce the combined cost structure. That is Greenfield’s expectation only. In an October 6 memo to staff, Ellison and Kreiz said integrating the companies would bring “difficult decisions that affect our workforce,” but the company has not said how many jobs will go.
NFL Rights Hold the Plan Together
Greenfield said the whole future of the company is riding on keeping its NFL rights. In his words, the company has to have them and has to pay whatever is required, because they are too important to the transaction. As Greenfield sees it, those rights are what make the shrinking television networks worth keeping while the company pays down debt.
What Investors Should Track Next
Greenfield has set out a clear test. Management’s target, as Greenfield describes it, is $18 billion of EBITDA by 2030. The combined company starts at $12 billion, the same level a smaller version of it began at when that company was created. Between the starting point and the target sits debt at about seven times leverage, and that debt has to be serviced with cash. For investors following the stock, the quarterly free cash flow numbers and how fast the debt balance comes down will show whether Greenfield’s test is being met, according to CNBC.
Greenfield says Skydance should be judged on the free cash flow it produces and how fast it pays down debt he puts at about seven times leverage. The risk he sees is the one that hit Warner Bros. Discovery: old cable networks shrinking faster than cost cuts can make up the difference.