Where we heard itCNBC’s Executive Decisions with Steve Sedgwick, Oct. 13, 2026. Speaker: Tarang Amin, chairman and chief executive of e.l.f. Beauty.
e.l.f. BeautyELF chief executive Tarang Amin almost passed on the company he now runs. On CNBC, Tarang Amin said he first thought there were “way too many brands, way too fragmented a category, not enough product differentiation.” That was a fair read of color cosmetics.
Amin went by a personal rule instead: “I’ve always had this other saying in my career, which is it never hurts to have a conversation.”
“I fell in love with the business,” Amin said. He described “a father and son entrepreneur who created this brand back in 2004 with this crazy idea of selling cosmetics over the internet for $1. Everyone thought they were nuts.” He then put his own family’s money into the company.
Why an 18-Month Timeline Was Unacceptable
Amin said product ideas often come from customers: “Our community will come to us and say, ‘Hey, e.l.f. help us out. We want a lip oil, but we can’t afford $36.’ The community comes to us.”
When Amin asked when one product would launch, he was told “18 months.” He answered: “I cannot get yelled at by our community” and “It has to happen now.” At most consumer goods companies, 18 months is a normal development cycle. Declining it reflects a separate operating philosophy, one that puts how fast the company answers its community ahead of internal process.
Amin describes the dupe strategy as selling products at a fraction of a prestige competitor’s price, made with a different formulation. The Washington Post reported on December 17, 2023 that viral dupes had made e.l.f. “the makeup brand of the moment.” The Business of Fashion called it beauty’s biggest disruptor on February 27, 2023. Forbes described its influencer-driven model as “management without managers” on February 22, 2026. A Mastercard economist has said today’s shoppers are more careful about how they spend.
Your Entry Point Decided Whether e.l.f. Paid Off
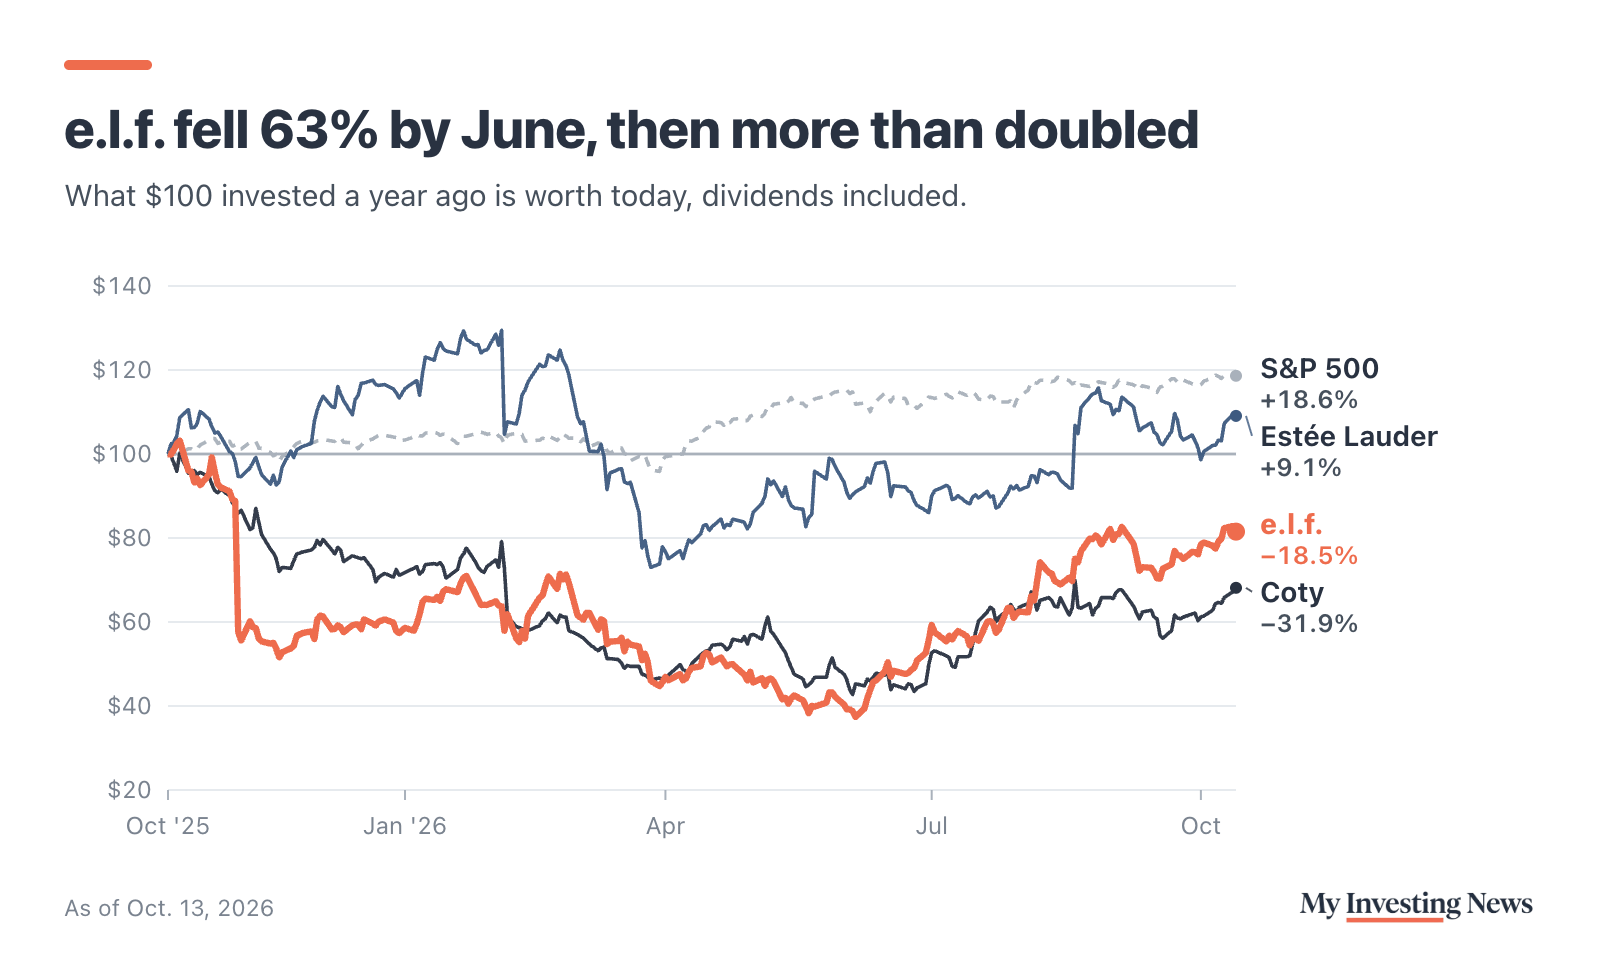
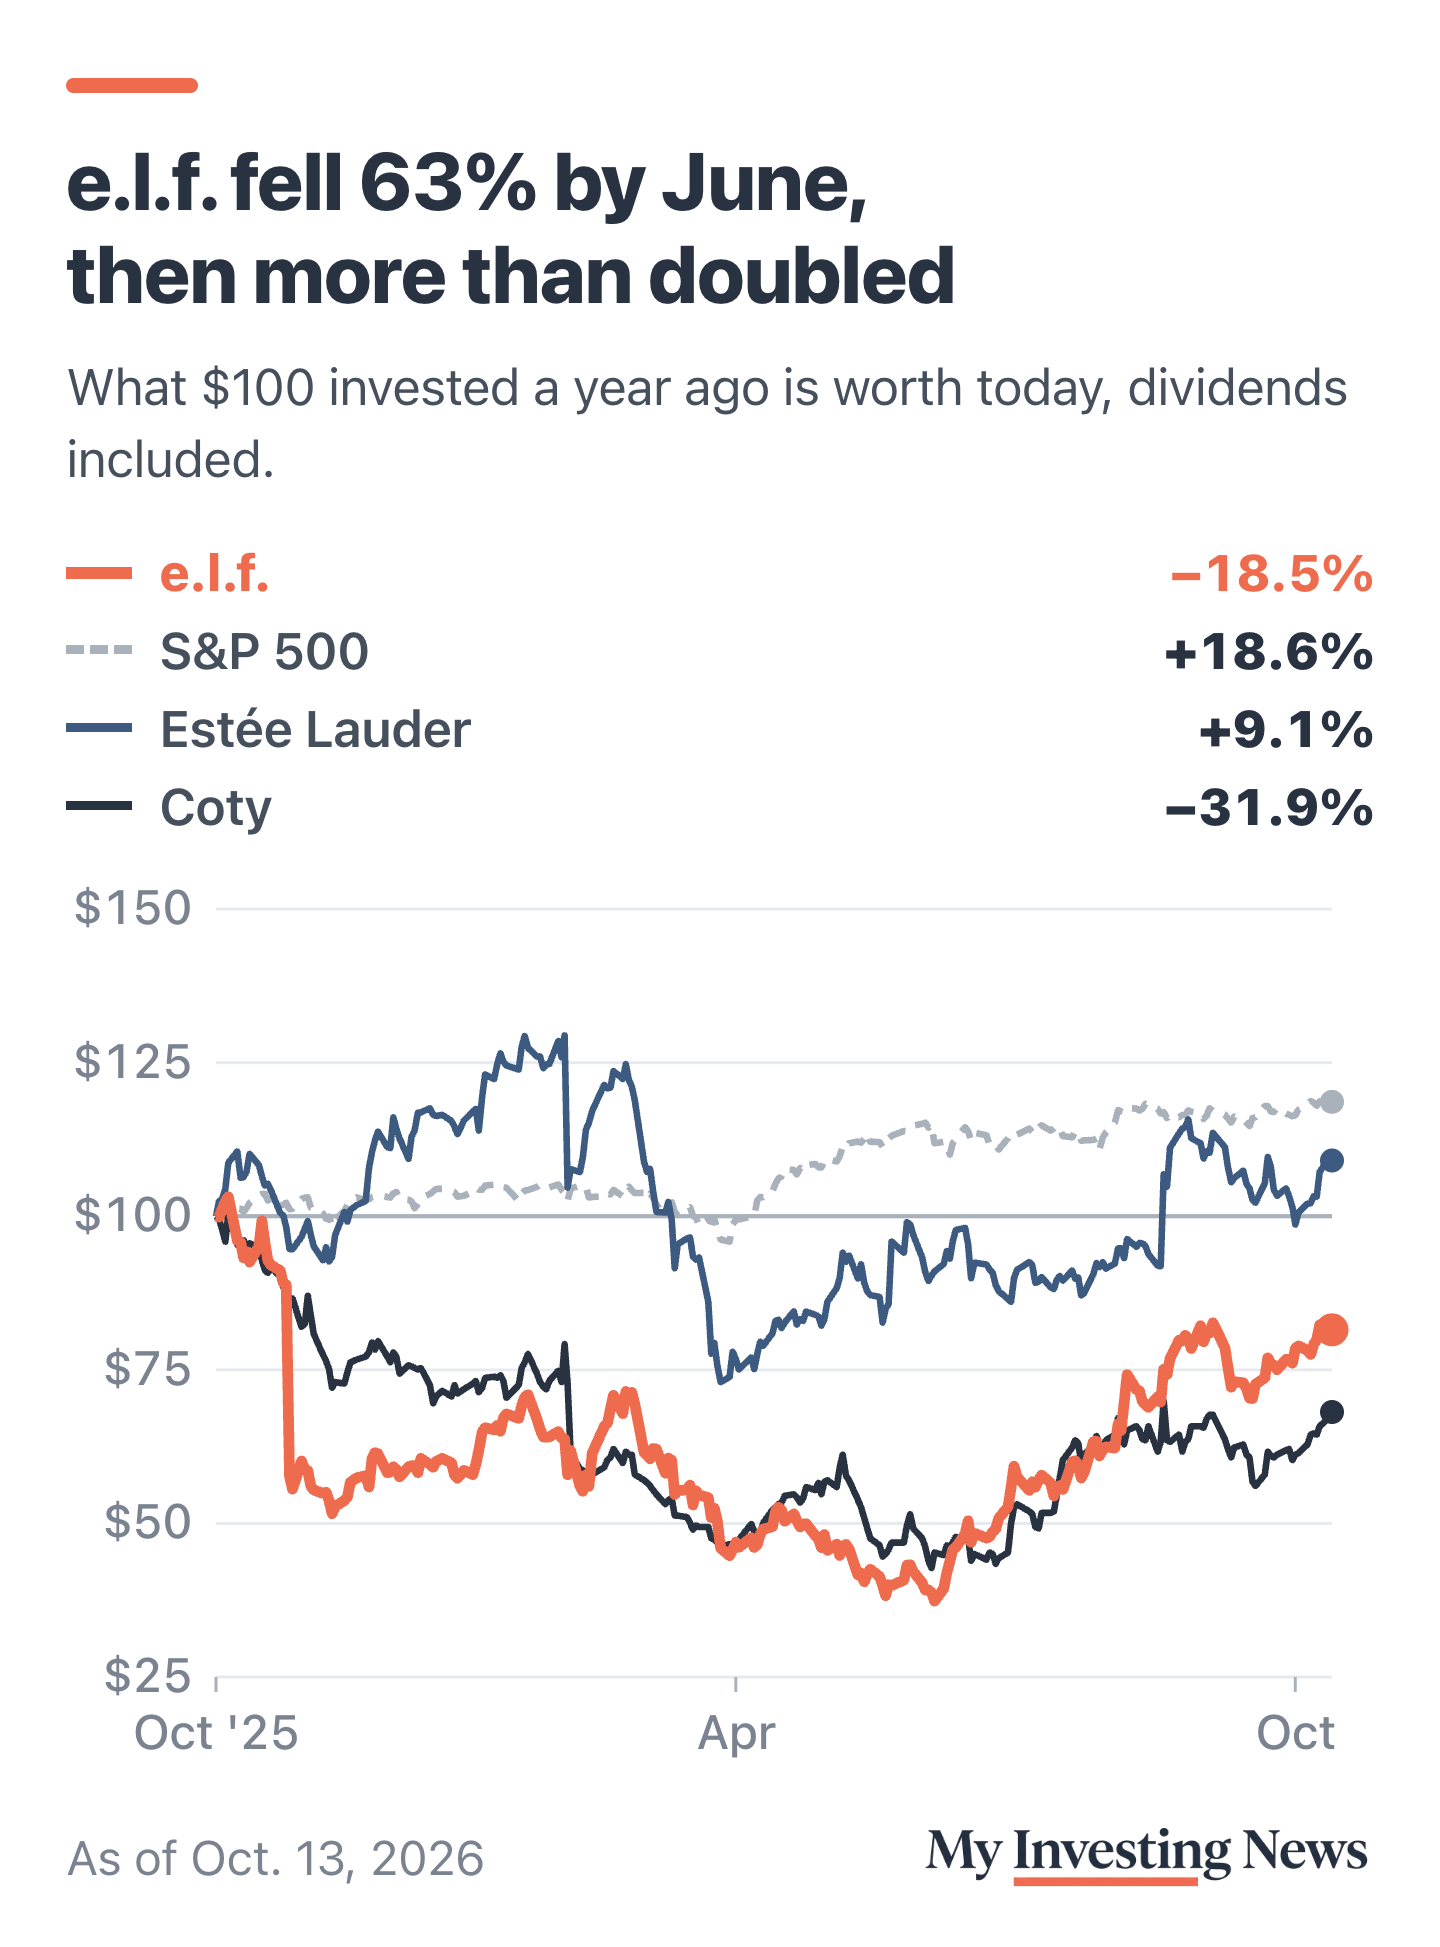
At the Oct. 13, 2026 close, Amin’s company traded at $108.16, up 42.2% year to date. Over the past year, the stock fell 18.5%. Someone who bought at the start of 2026 has done very well. Someone who bought a year ago has not. The difference in outcome comes down to entry timing.
Shorter periods are also positive: 11.6% over the past month and 5.2% over the past week. The five-year gain is 266.9%. Shares slipped 1.6% in the Oct. 13 regular session. This pattern is consistent with a stock that declined over the past year and has since been recovering.
Six Brands and a Sector Label That Misleads
e.l.f. now sells cosmetics, skincare and hair care through e.l.f. Cosmetics, e.l.f. SKIN, e.l.f. Hair, rhode, Naturium and Well People. It is listed on the New York Stock Exchange and has a market capitalization of about $6.4 billion. It went public in 2016, and Fortune’s headline on September 22, 2016 read “e.l.f. Beauty IPO Shines in Wall Street Debut.”
e.l.f.’s latest quarter, reported Aug. 5
The stock is classified as consumer defensive, in household and personal products. That label usually goes with steady, unexciting businesses, and the price moves above are neither. If you screen stocks by sector, it helps to know that a classification and a stock’s actual behavior can differ.
The company markets its products as clean, vegan and double-certified cruelty free. It says it was the first beauty company with Fair Trade Certified facilities and that it donates 2% of net profits to organizations making positive impacts. These are the company’s own claims, laid out in its SEC filings.
What Amin’s Rule Actually Teaches
Amin read the category correctly: it was fragmented and generic. That read still pointed him to the wrong conclusion about this company. e.l.f. was the exception, and the only way to find that out was to look. Most such meetings go nowhere.
Risks Hidden Behind a Flattering Story
A story about joining a company, told by the person who joined, tends to flatter its teller. Every operational claim here is Amin’s, including community-led development, retail productivity and generational rankings.
Growth built on dupes depends on prestige competitors continuing to set the reference price, which makes it a source of dependence as well as advantage. Those prestige houses are under strain of their own: LVMH’s biggest division just posted a 5% sales drop. A company that has made acquisitions is also a different investment than the single-brand business in the founding story.
The stock has risen over five years. Investors should watch the next earnings report, rhode’s integration into the portfolio and tariff costs.
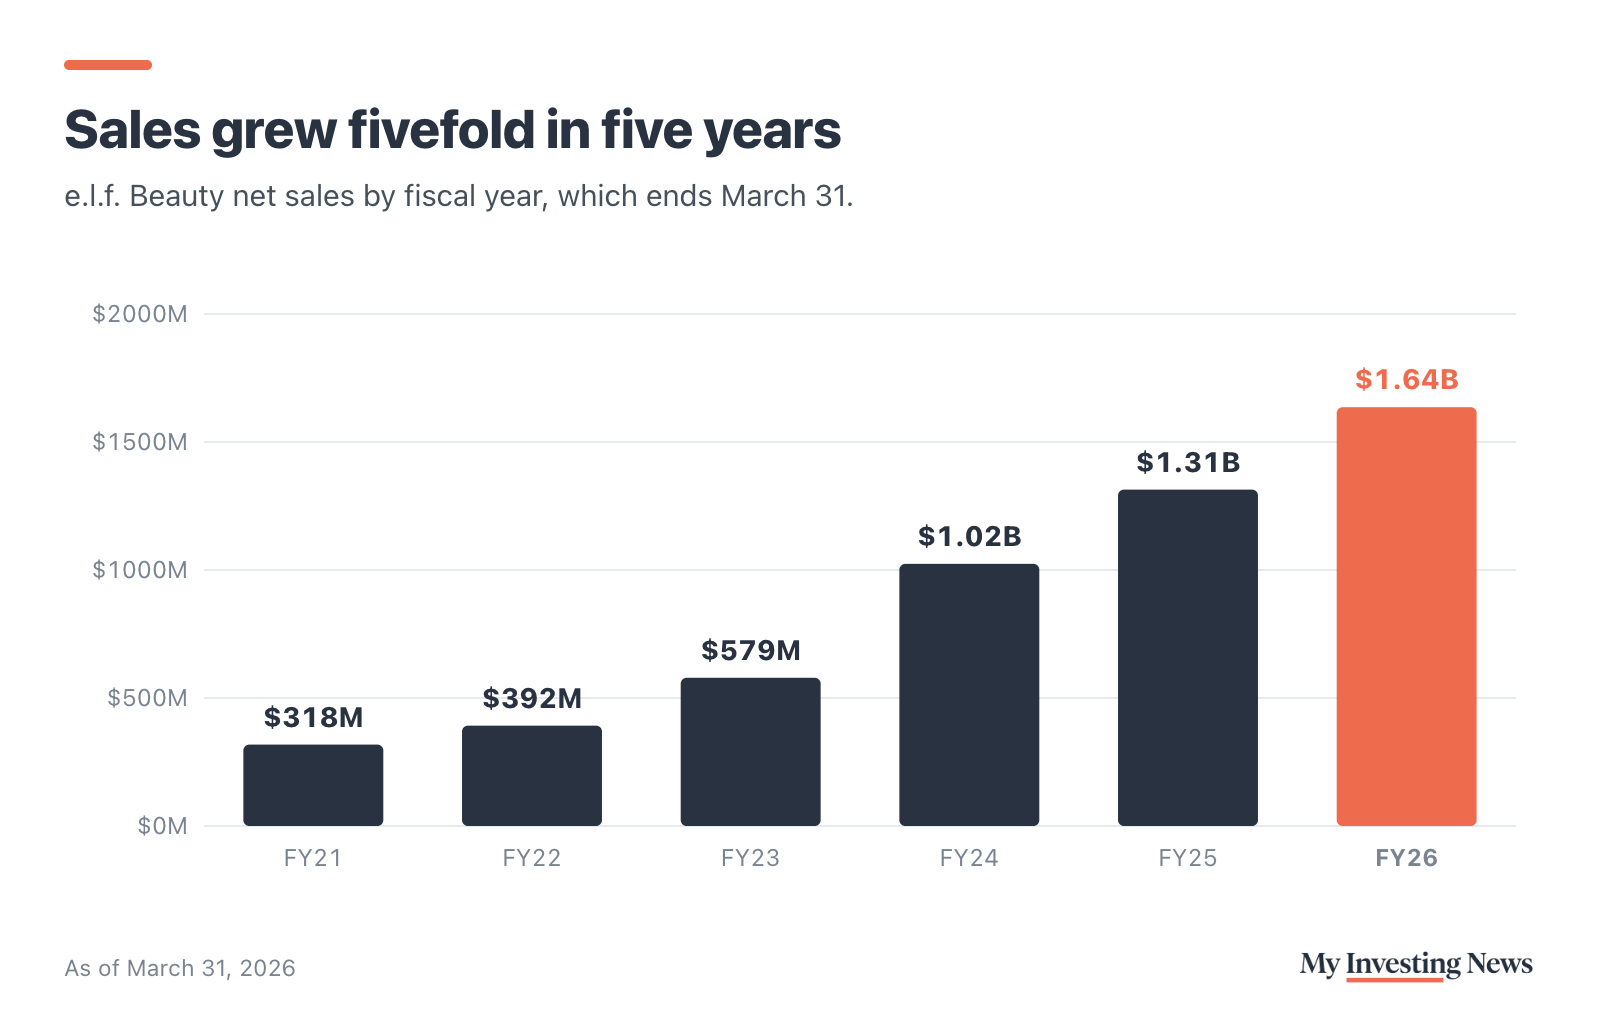
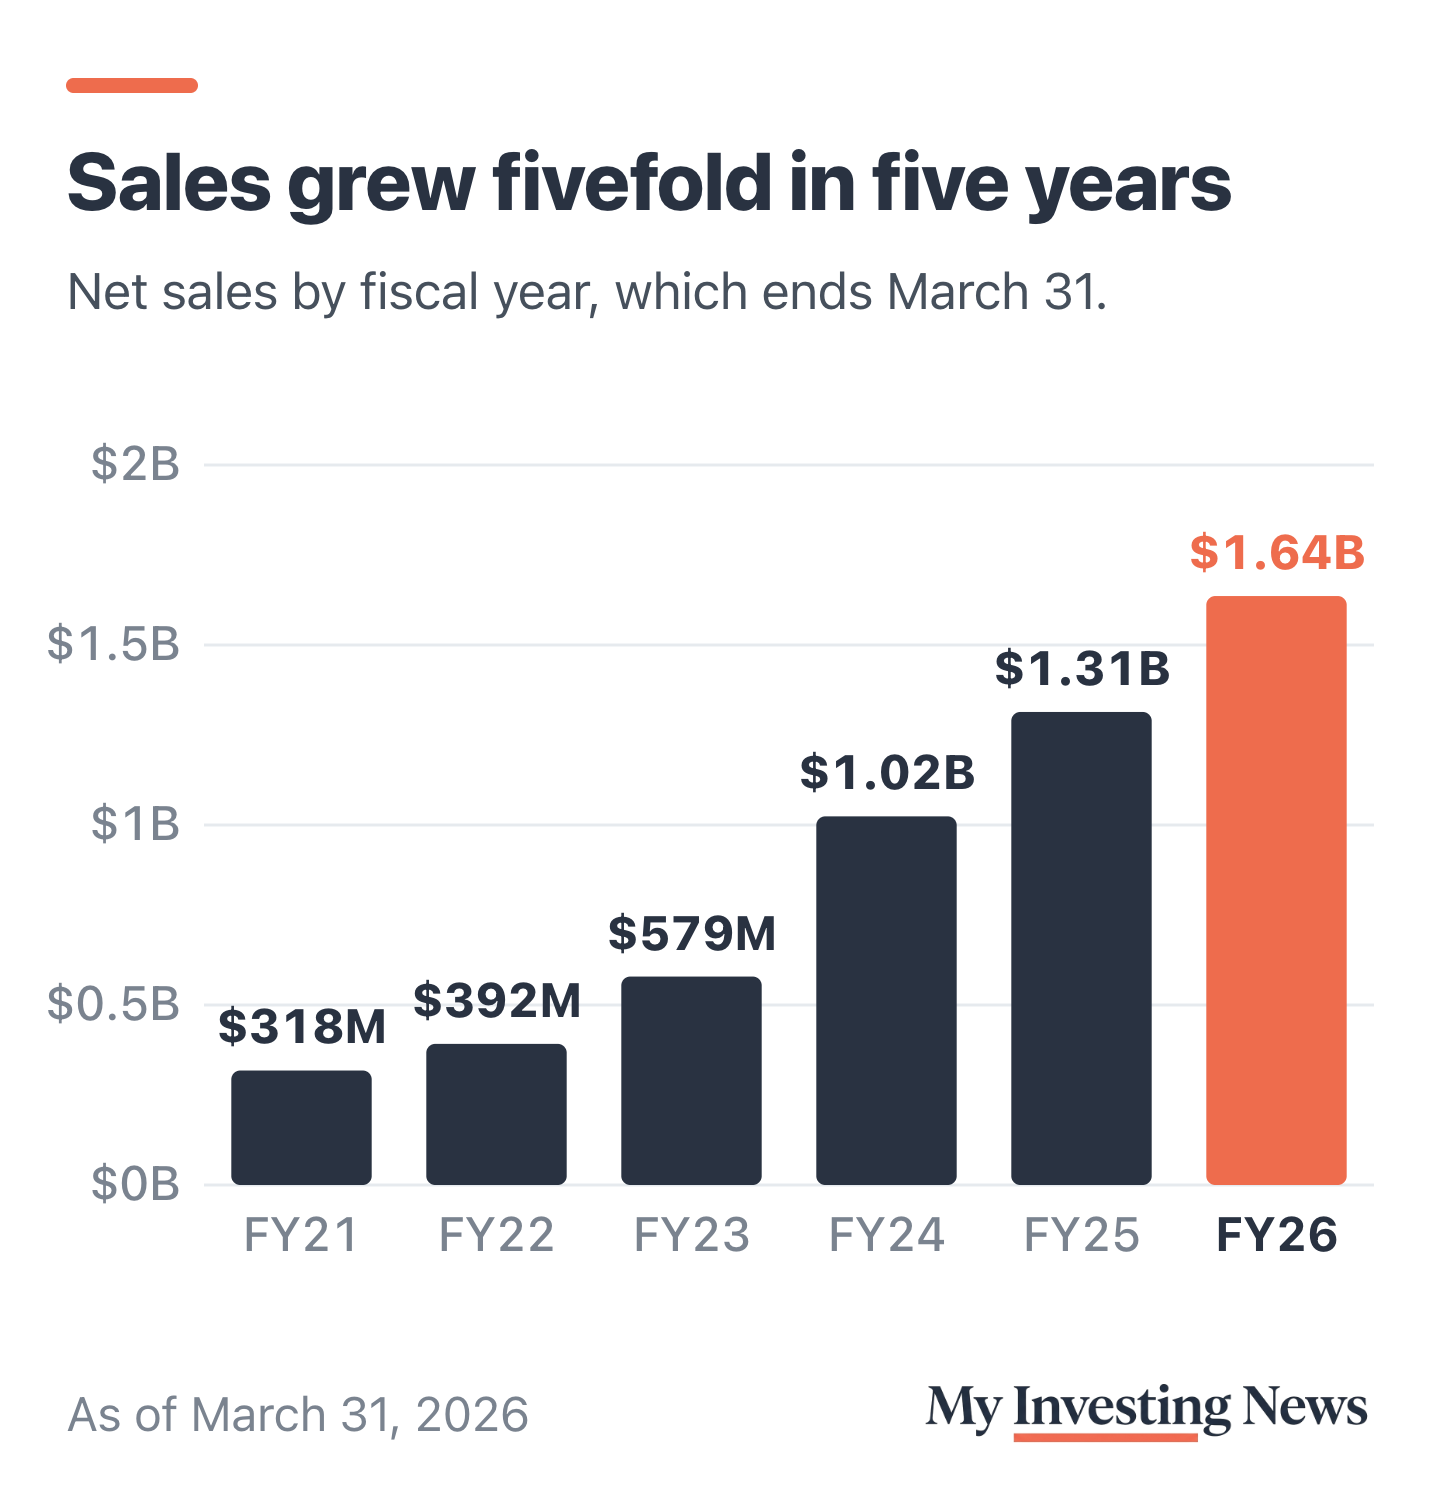
Amin nearly skipped the meeting that led him to e.l.f., and he credits a simple rule, that it never hurts to have a conversation. The company has grown sales fivefold in five years, and the stock is up 42% this year. The risk is in the timing: buyers from a year ago are still down 18%, and growth built on dupes and acquisitions has to keep delivering.