Where we heard itBloomberg Daybreak Europe (Bloomberg TV), Oct. 13, 2026, the morning after LVMH’s third-quarter sales report. Speaker: Bloomberg luxury reporter Angelina Rascouet, live from Paris.
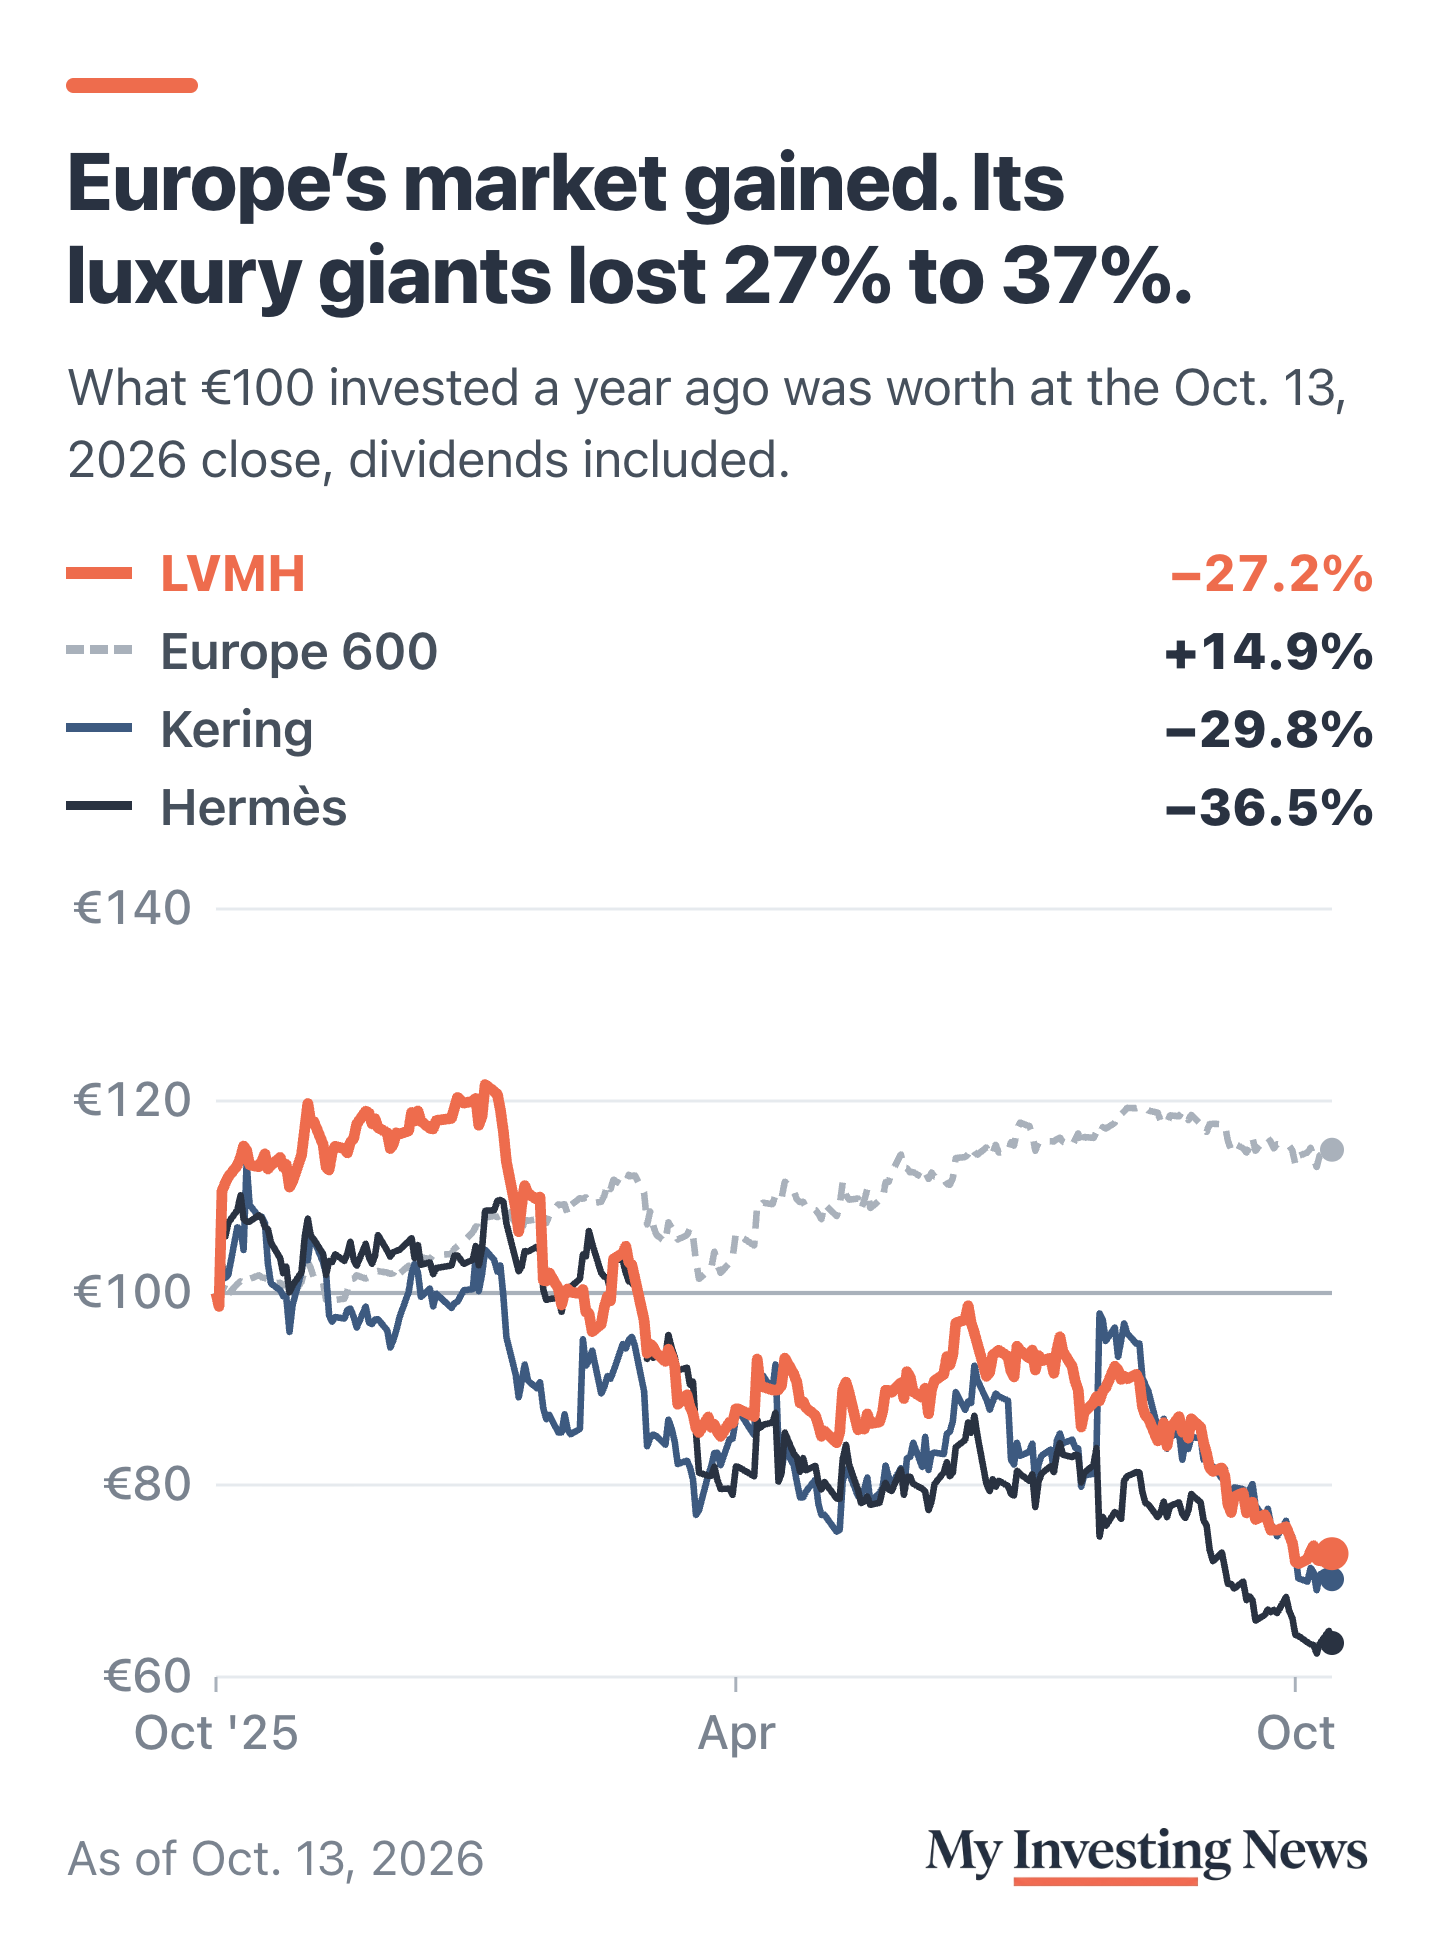
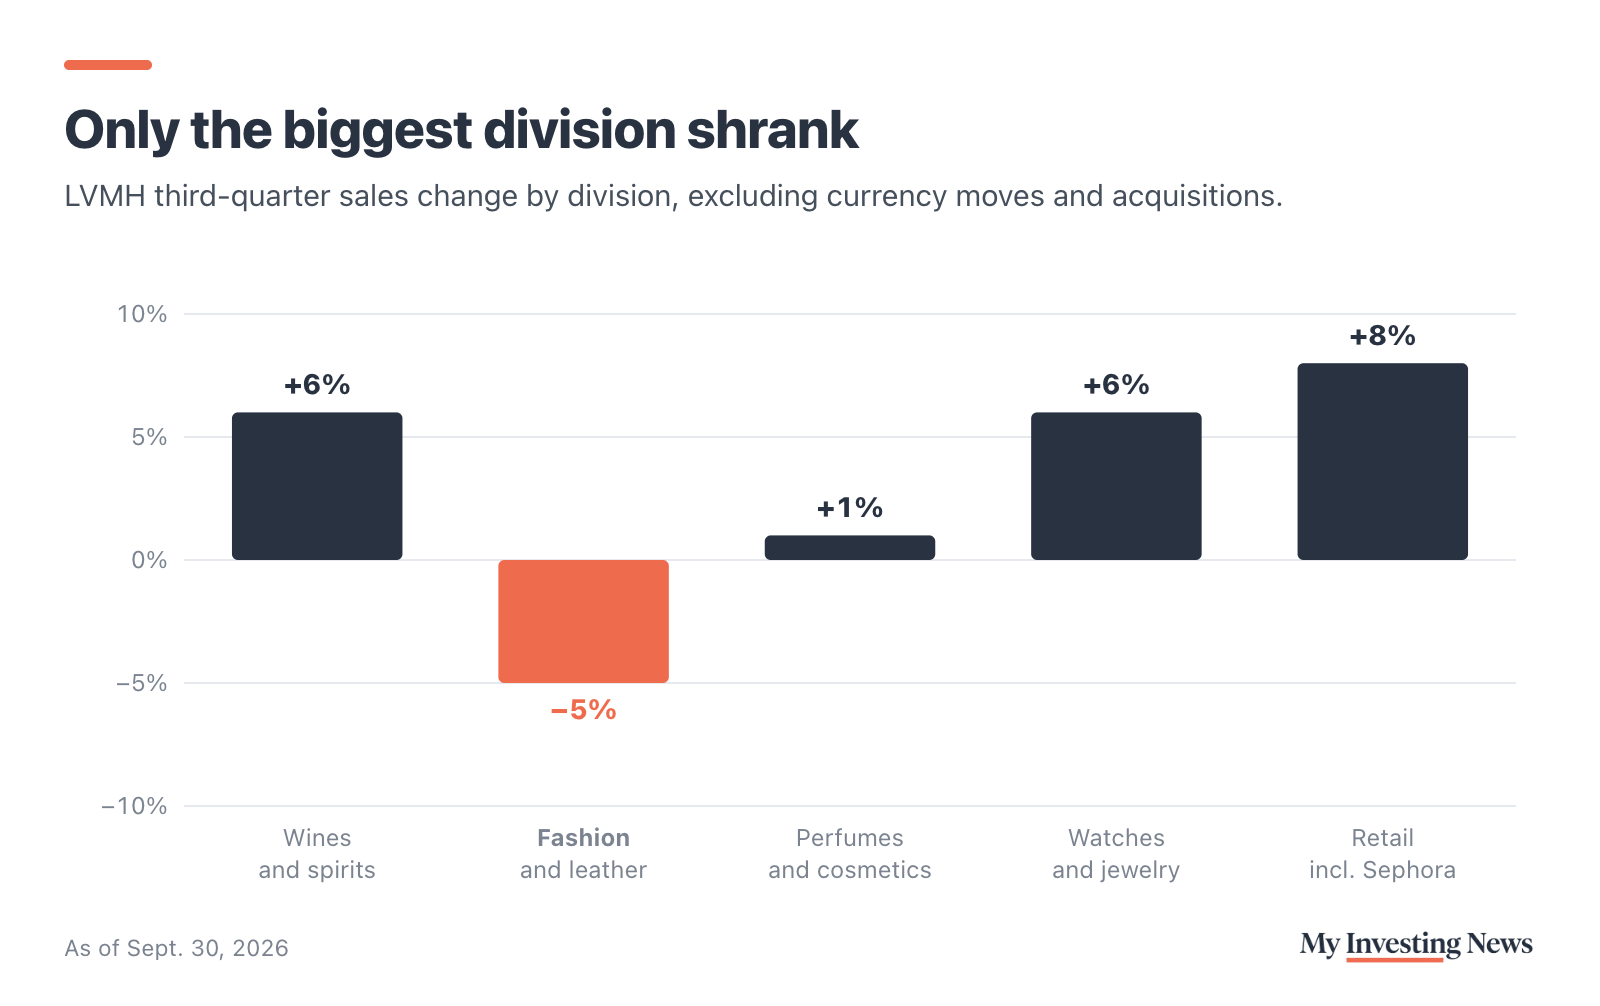
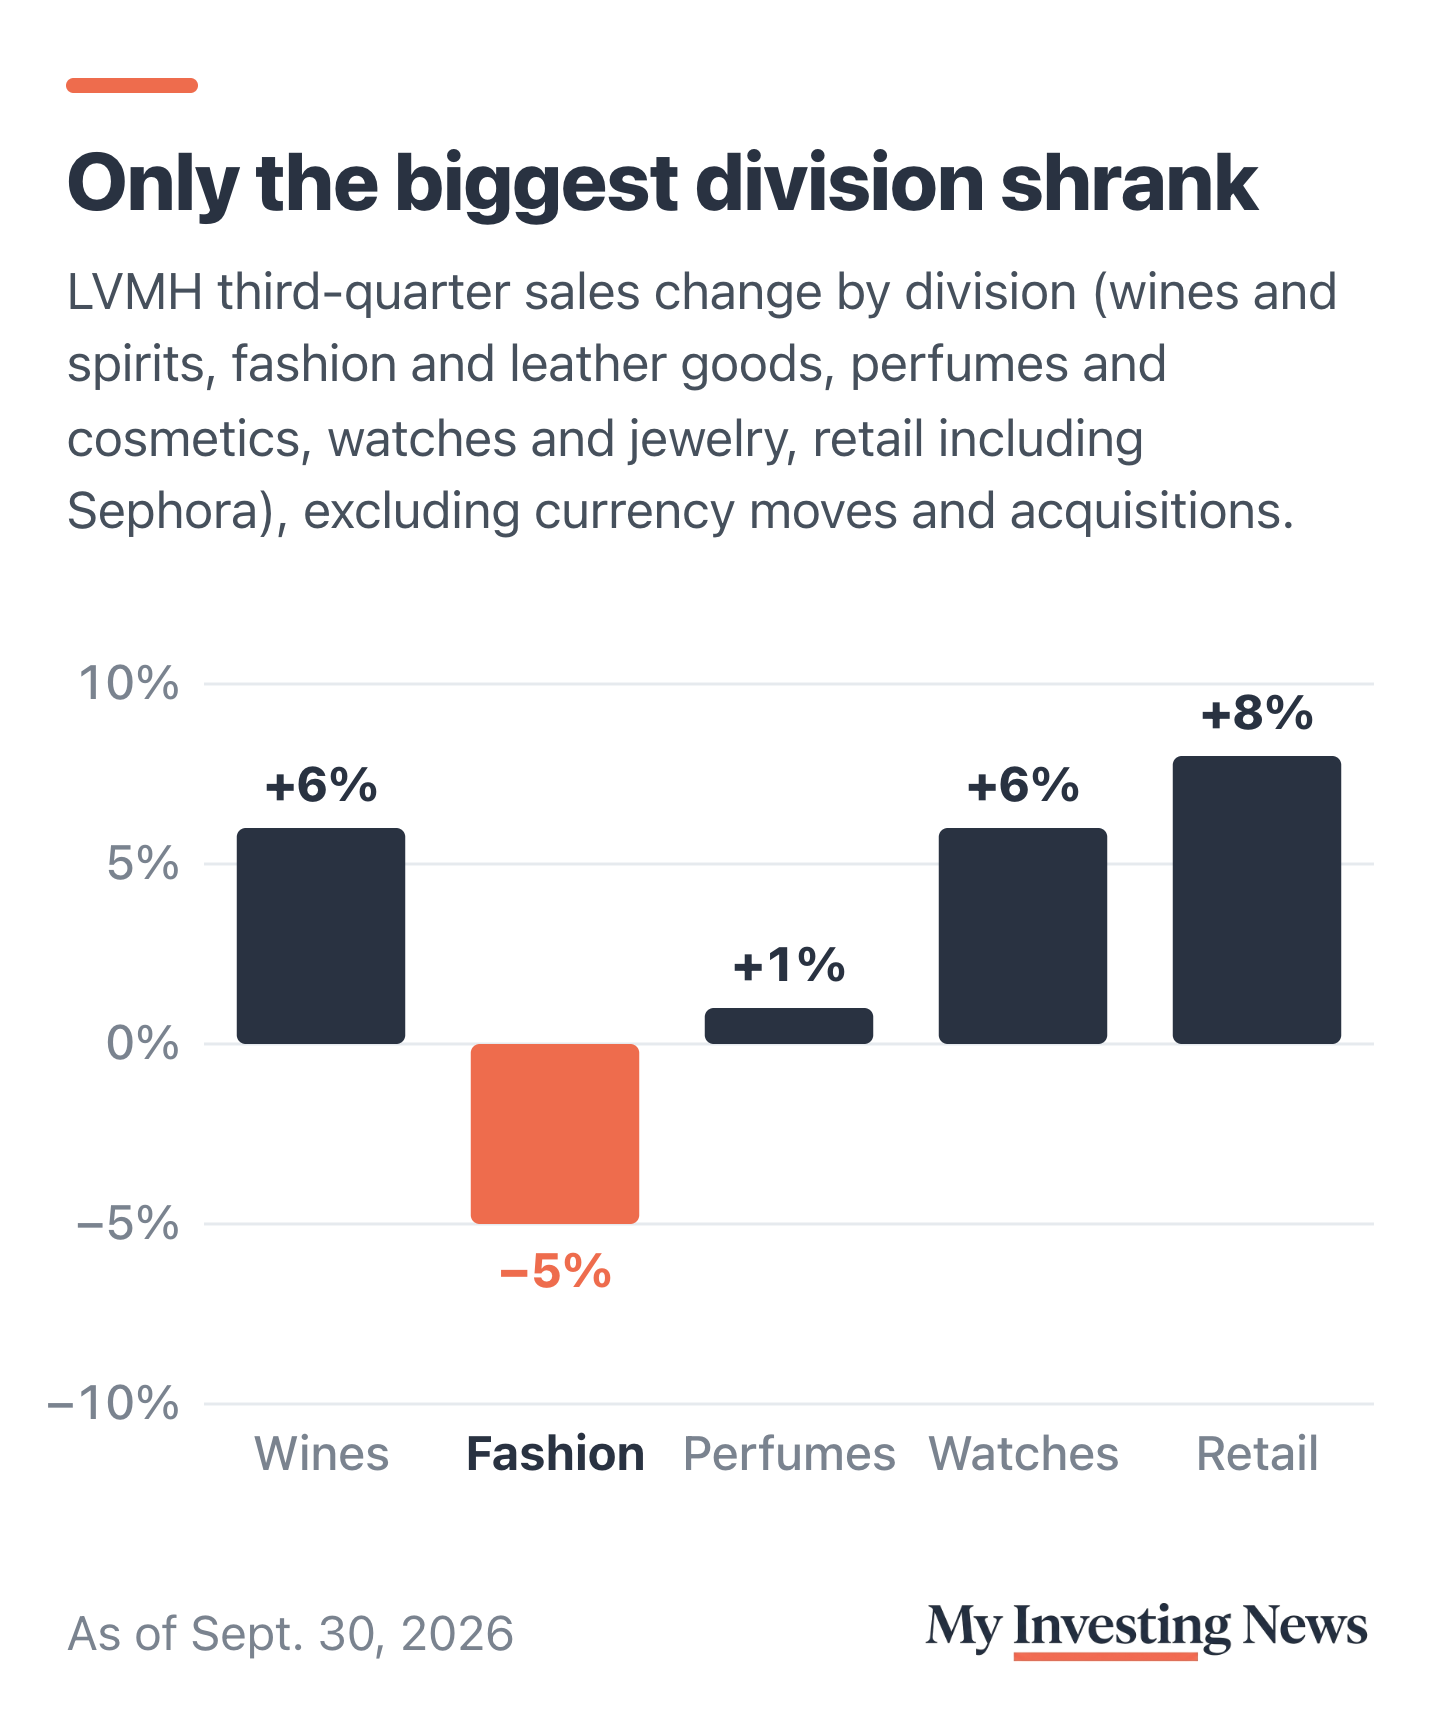
Louis Vuitton won a trademark lawsuit in China against a local tea chain called Molly Tea. Consumers pushed back after the ruling. LVMH’s Fashion & Leather Goods division, its largest, then reported a sales decline for the third quarter. Quartz reported that LVMH fashion sales fell 5% on a China drag, and Seoul Economic Daily also reported a 5% drop as the China backlash built.
That figure is an organic decline, which strips out currency moves and acquisitions. It covers the whole Fashion & Leather Goods division, which houses both Louis Vuitton and Dior, and much of the coverage confuses the two, though the distinction matters.
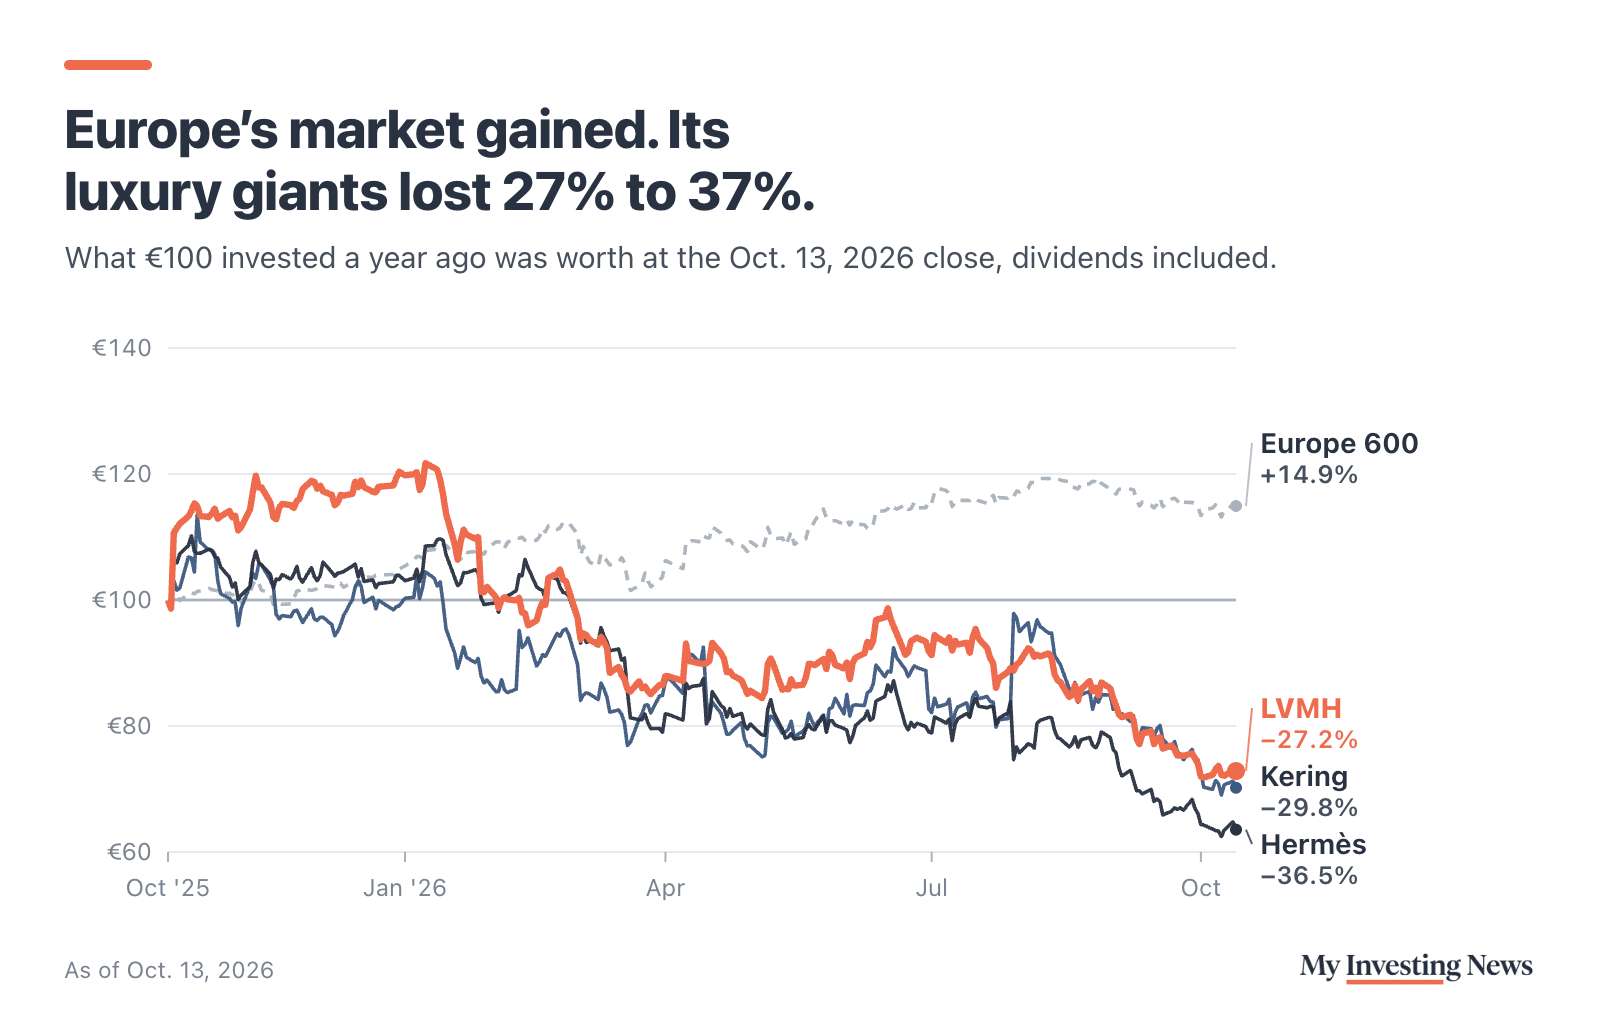
LVMH is listed in Paris and does not trade on a major US exchange, so American investors can only reach it indirectly.
The results were widely reported as a setback for the sector, and Reuters, The Wall Street Journal, CNBC and Quartz all covered the quarter in those terms.
Management Confirms the Backlash Hit Sales
Bloomberg luxury reporter Angelina Rascouet described the sequence: “Louis Vuitton, the main brand, suffered from a backlash from consumers after Louis Vuitton won a trademark lawsuit against a local tea chain called [Molly Tea].” Rascouet said sales for the division were down 5%, calling the result “much worse than expected.”
Rascouet also said LVMH’s chief financial officer, Cécile Cabanis, said “it definitely had an impact, especially at the start of the quarter.” Bloomberg’s written report quoted Cabanis as saying the backlash “had a negative impact, at least at the beginning of the quarter” on Louis Vuitton sales.
When a company confirms that a reputation event moved its revenue, that confirmation tells investors more than any outside estimate could. Management has the store-level data.
How a Legal Victory Turns Into a Commercial Cost
Trademark enforcement protects an asset worth protecting. A luxury house that stops defending its marks will see them diluted over time, and that cost is real, which is the reason legal departments act.
An enforcement action is public, while the thing it defends is a feeling. A luxury brand’s pricing power depends on how consumers feel about it. If an action looks like a large foreign company overwhelming a small local business, it can damage that feeling faster than dilution would have. Porsche is leaning on the same kind of pricing power: it plans to raise prices on its top models by 20%.
So the real trade-off is legal risk against brand risk. Brand risk is harder to quantify, and things that are hard to measure tend to get underweighted. This describes a mechanism, and causation remains unproven. Nobody outside the company knows how much of the decline came from the backlash and how much came from the broader economy.
LVMH’s third quarter at a glance
China Was Already a Hard Market
Reuters, The Wall Street Journal and CNBC covered the results on October 12, 2026, with Reuters citing China gloom dimming hopes of a luxury revival. Reuters reported on October 9, 2026 that a Chinese tax crackdown was adding pressure on luxury brands while US spending faltered. In the U.S., a Mastercard economist has said consumers have the money to spend, though FINRA found a record share spending more than they earn. Rascouet said “the macro backdrop is much harder” and is “going to be delaying the recovery.” The backlash landed on top of a weak market likely to produce a poor quarter on its own.
Cost Cuts Cannot Replace Demand
Angelina Rascouet reported that the CFO hinted cost cutting “will not bring sales” back. Defending margins works for a while, but it cannot stand in for demand. When management says so publicly, it is telling investors that the tools it can pull are limited.
Why Brand Risk Belongs in Every Investor’s Analysis
LVMH is the largest operator in luxury, so its results are read as a signal for the whole sector. The Wall Street Journal wrote that the results cast a pall over luxury’s fragile recovery, and CNBC said they were dashing sector hopes. Other luxury groups report later in October.
Beyond luxury and China, companies face hidden exposures. Any company whose pricing power depends on customer sentiment carries an exposure that never appears on its balance sheet and that a legal risk review may miss. This quarter is unusual because management acknowledged the damage and it showed up in a reported number within a single quarter.
Reasons to Keep the Backlash in Perspective
- One quarter does not make a trend, and luxury demand moves in cycles.
- The company did not put a number on the backlash’s contribution, so its size is unknown.
- Letting a trademark go unprotected carries its own long-term cost, and that cost would never show up in any single quarter.
- This is one division’s figure. LVMH did not report this decline for the company as a whole.
Whether the legal win was worth its apparent cost cannot be calculated. Investors should watch other luxury groups’ reports later in October and LVMH’s next update for signs the backlash is fading. More detail on the group’s reporting is available on LVMH’s investor relations site.
Bloomberg’s Angelina Rascouet tied a 5% organic drop at LVMH’s biggest division to a weaker China and a consumer backlash over Louis Vuitton’s trademark win against Molly Tea, an impact the company itself acknowledged. The rest of the group still grew. The risk is that China stays weak and nobody can yet say how much of the drop came from the backlash.