Where we heard itCNBC’s Squawk Box, Oct. 12, 2026. Speaker: Jacob Manoukian, head of U.S. investment strategy at J.P. Morgan Private Bank.
Jacob Manoukian, head of U.S. investment strategy at JPMorgan ChaseJPM Private Bank, went on CNBC as earnings season opened and called semiconductor stocks cheap. “When we look at the semiconductor names they’re trading at a discount to the market, discount to their own average multiples and that’s telling us that the market expects a pretty material deceleration,” Manoukian said.
Strategists often talk their book, and readers should consider the view with that in mind.
Up This Much and Still Cheap?
The iShares Semiconductor ETFSOXX has returned 81.2% year to date and 101.0% over one year, including dividends, through the Oct. 12 close. The SPDR S&P 500 ETFSPY returned 15.0% and 20.4% over the same windows. So how is something up this much cheap?
How a Rising Stock Gets Cheaper
A valuation multiple measures price against earnings. If earnings climb faster than the share price, the multiple declines even as the stock rises. That is exactly what Manoukian’s forecast describes.
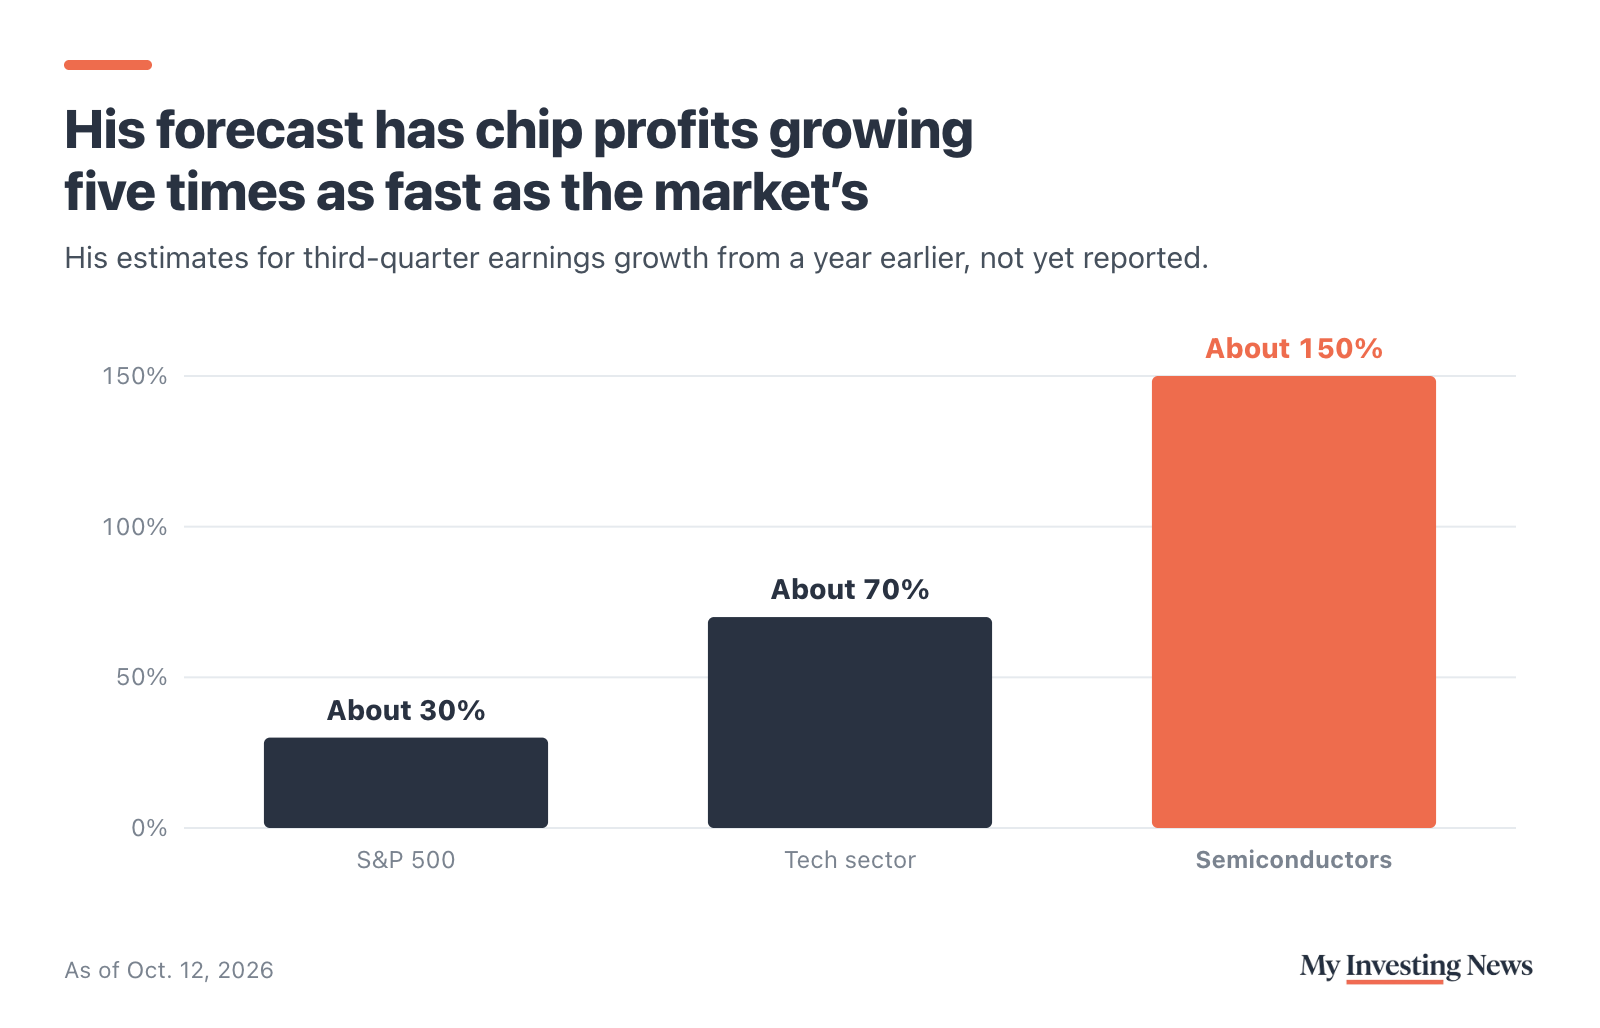
Manoukian estimates semiconductors “might come in around 150% earnings growth” this quarter, with Manoukian’s estimate for the broad tech sector at around 70%. For the full index, Manoukian said “The S&P 500 did about 30% ex items last quarter, it’s probably going to do around 30% again this quarter.” Every one of those current-quarter figures is his estimate. None has been reported.
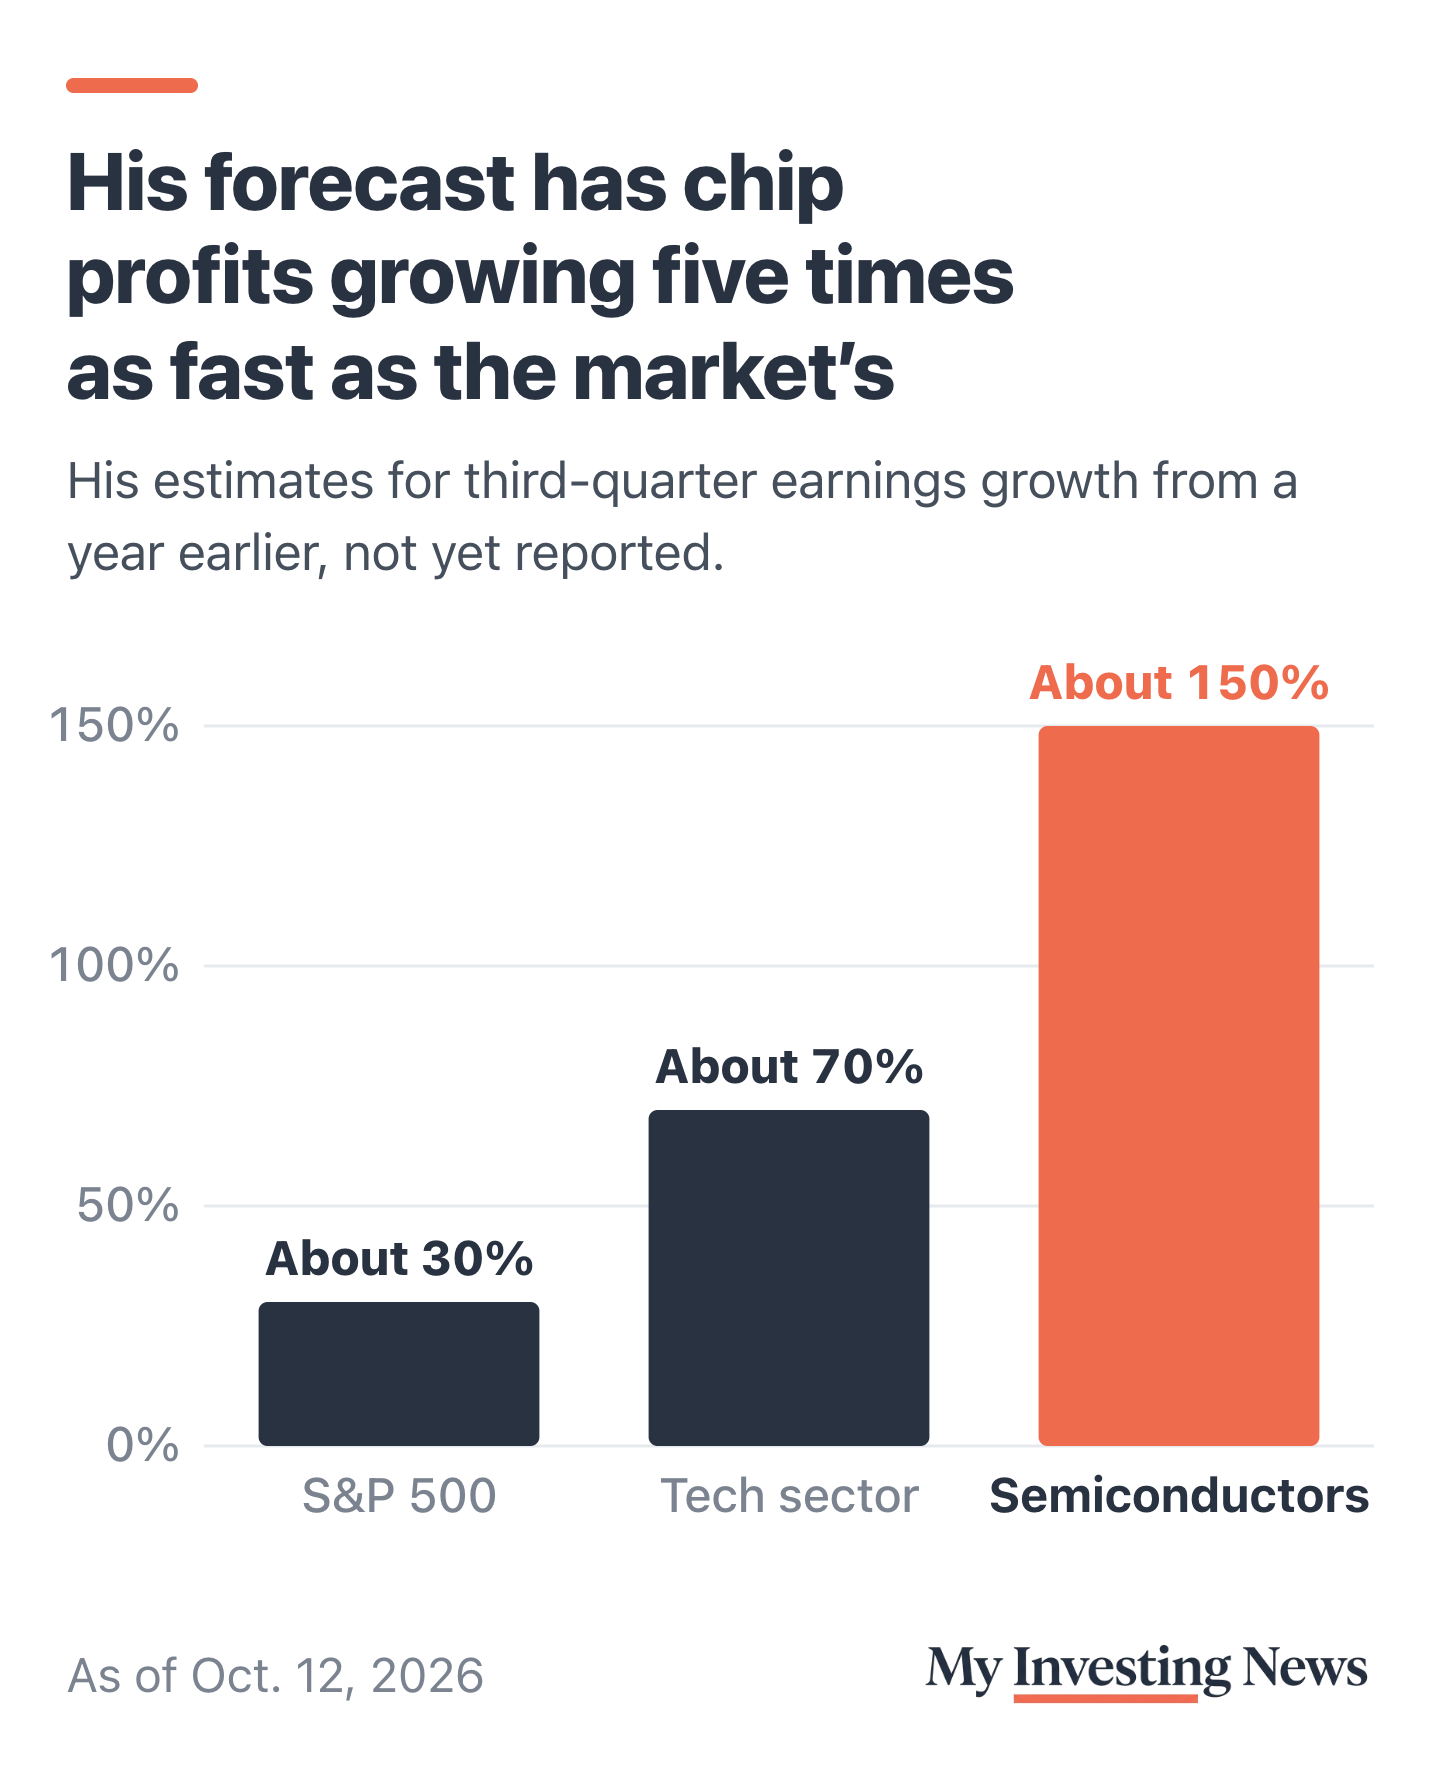
Whether the thesis is right depends entirely on earnings coming as forecast.
Catalyst to Track: Hyperscaler Budgets
Manoukian named his trigger: “We think the catalyst is that hyperscale capex will get revised higher.” Hyperscalers are the largest cloud operators, running data centers at enormous scale. Their capital budgets buy servers, accelerators, memory and networking gear, and chips sit inside nearly all of it, so higher capex guidance tends to flow into chipmaker revenue. Marvell’s CEO has called a $30 billion custom chip target “not a stretch.” That revision is the specific, verifiable event to follow. It has not happened yet.
Last Week Pointed the Other Way
Over the past week, SOXX fell 7.58% while SPY rose 0.42%. Manoukian attributed the rotation late in the week to changing perceptions about how quickly private model labs are growing. That is his explanation, and we did not verify the cause of the move.
One week is no trend, and a sector that has run this far can give some back without the thesis breaking. Still, it is the only live evidence available, and it cuts against him. Portfolio manager Lance Roberts said he was trimming AMD and Nvidia after big runs.
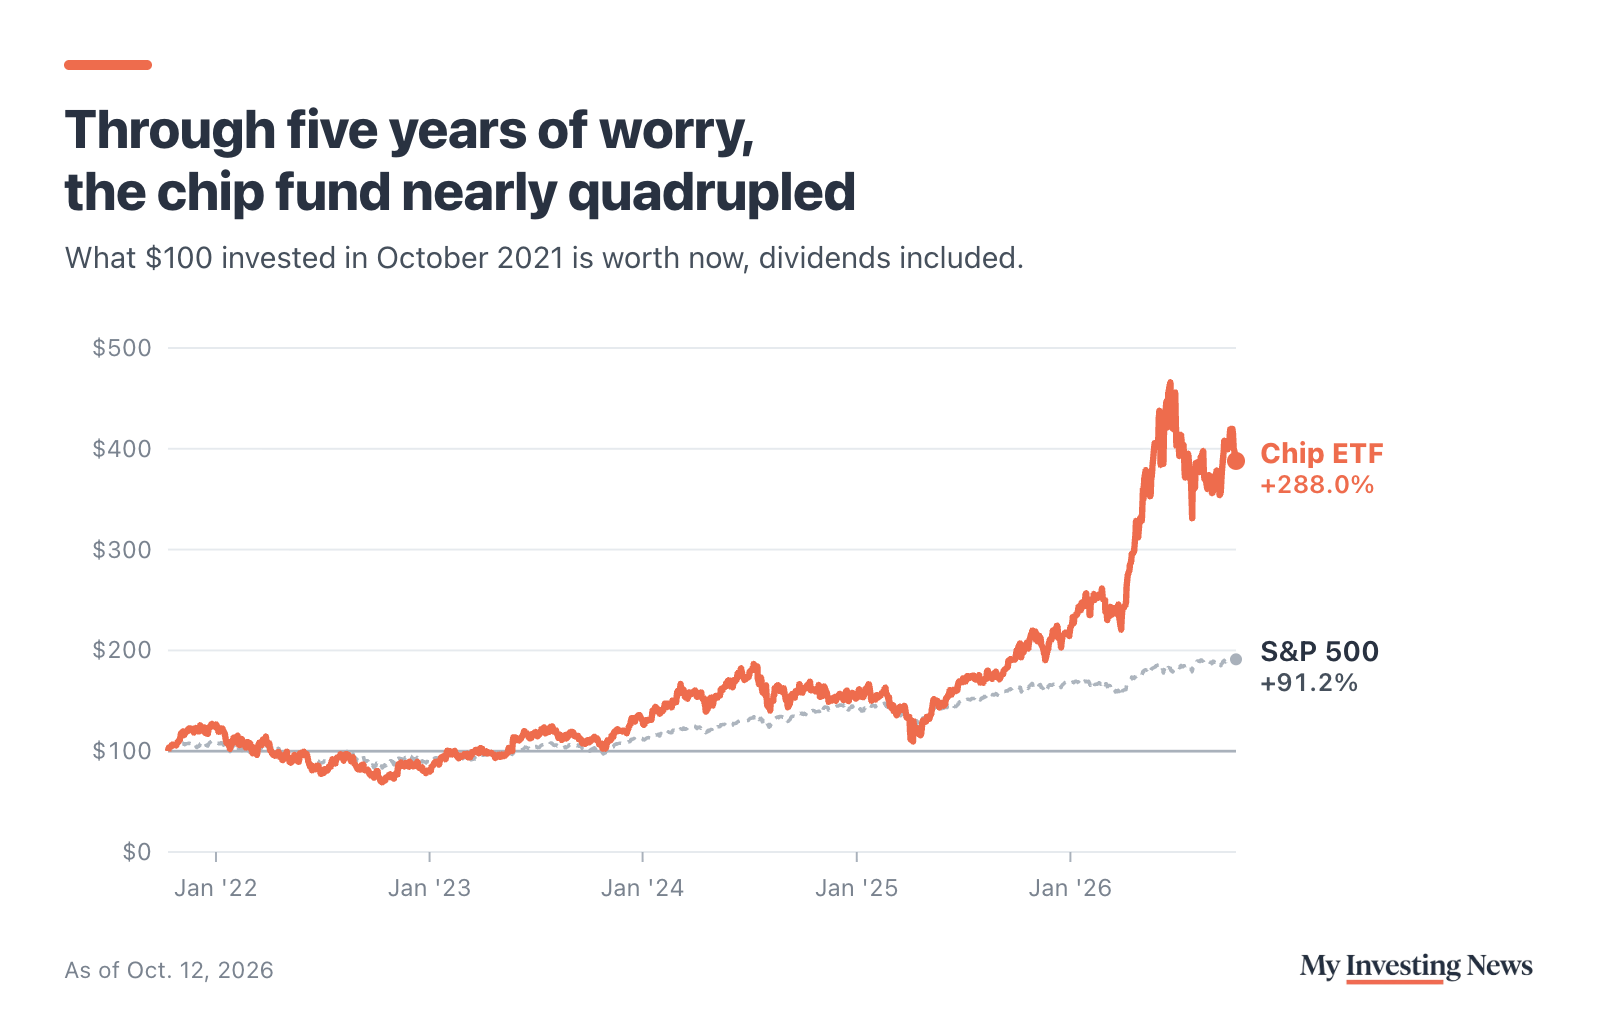
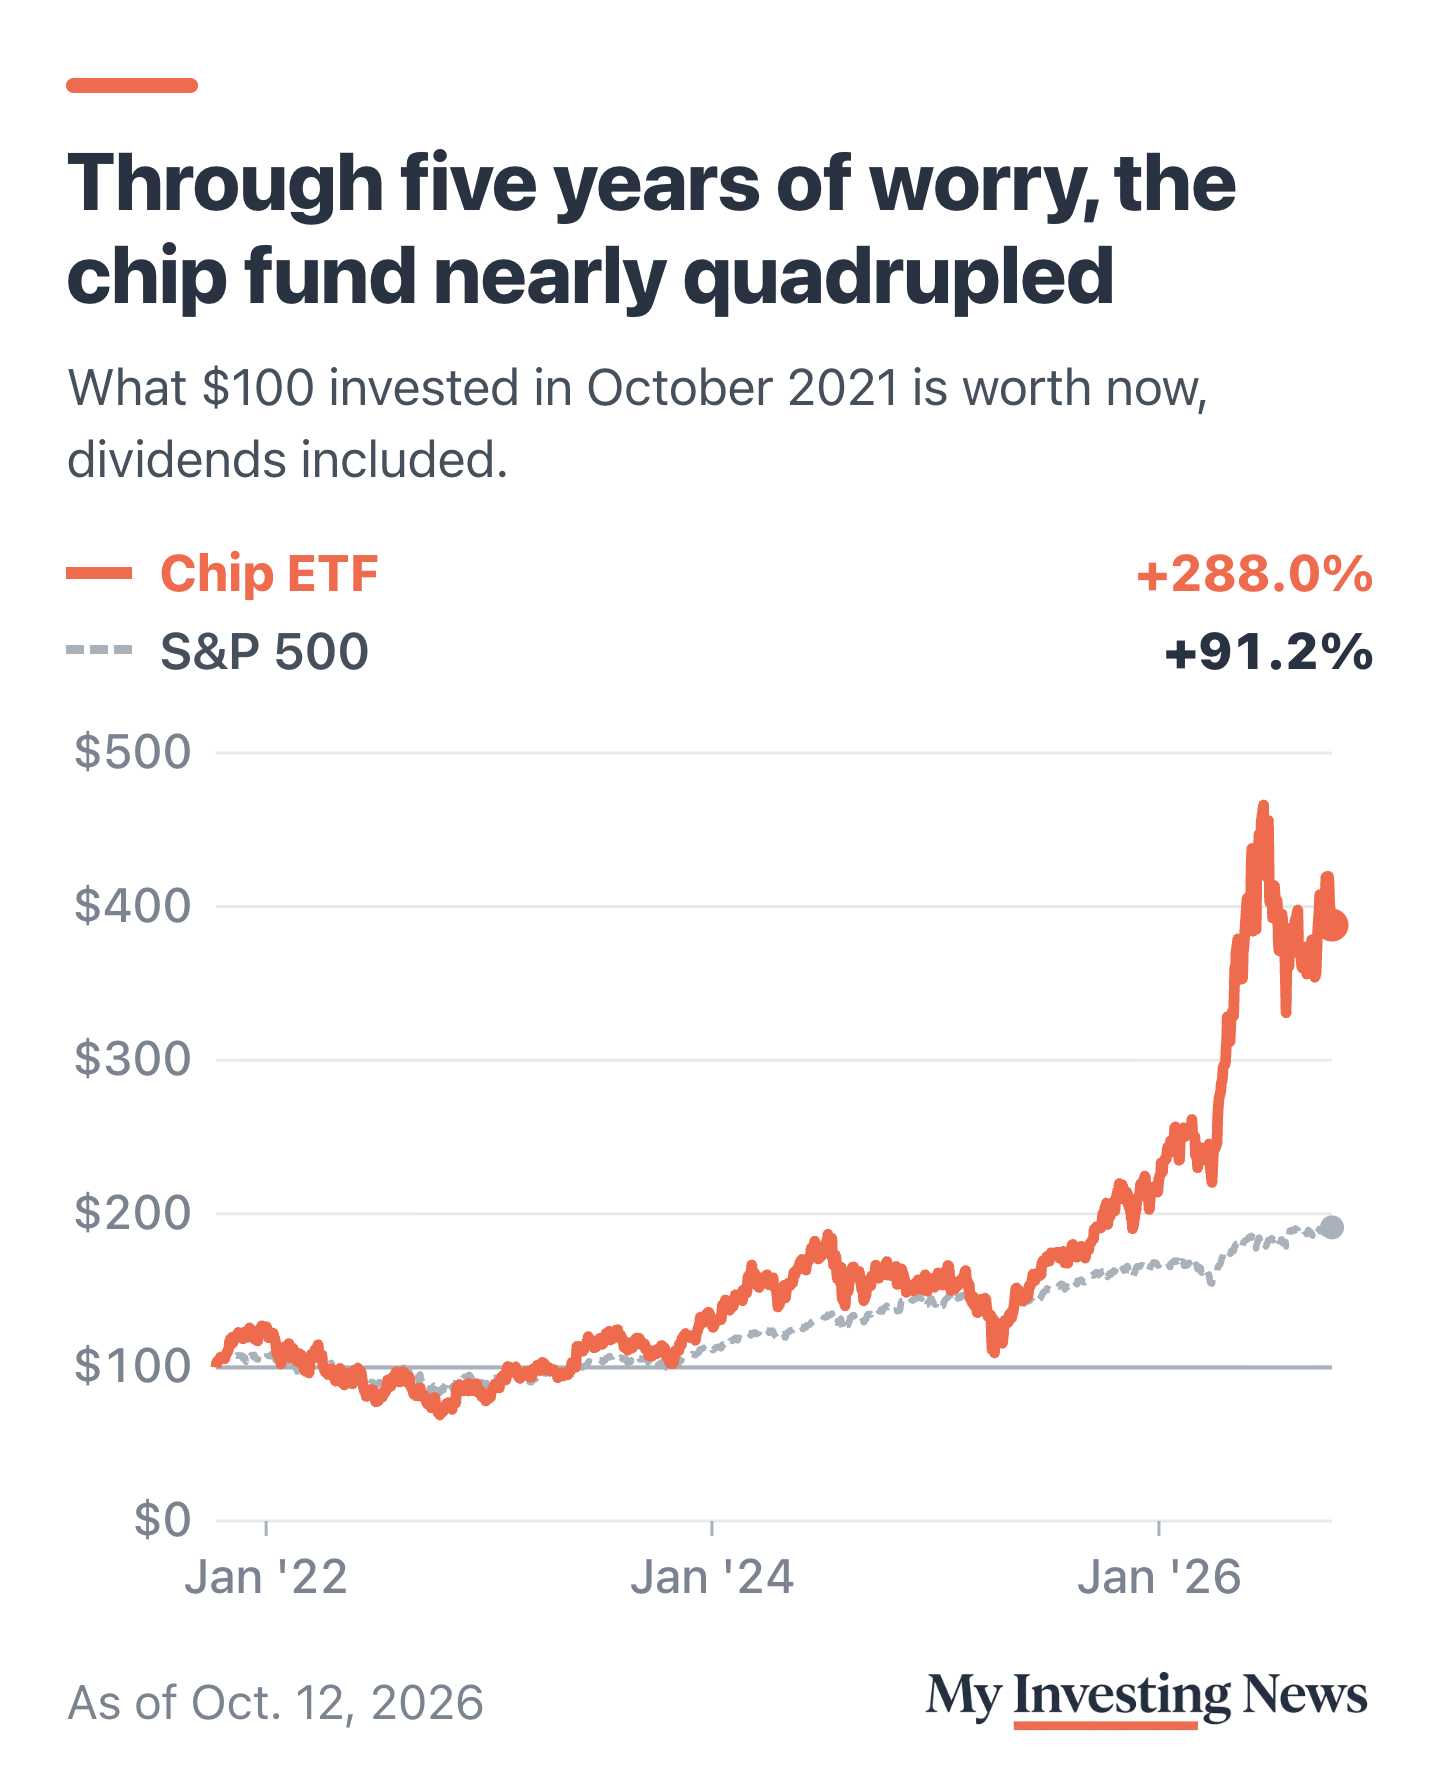
The chip fund vs. the S&P 500, through Oct. 12
Wall of Worry Has Paid So Far
Manoukian sees skepticism as fuel: “I think what the gift that keeps on giving to investors is this wall of worry that continues to get built around the AI trade.” Since the model labs launched their first consumer products, he said, there has been “a consistent stream of negativity surrounding the trade and throughout that time it’s continued to outperform.” He added that “throughout that period that wall of worry has kept valuations contained and it’s allowed the entire complex to exceed expectations.”
The record supports the outperformance. Over five years SOXX returned 288% against 91% for SPY, both including dividends, and it also led over one year. On the evidence so far, the worriers have been wrong.
An argument built on skepticism being wrong is hard to disprove in advance. A decline can be read as the worry finally being justified, and a rise as the worry being overblown again. Readers should recognize it as an interpretive frame. The verifiable parts of his case are the earnings forecasts.
A Second Supercycle Most Coverage Skips
Manoukian also pointed beyond AI to spending tied to “geopolitical fragmentation. So spending to defend against next generation conflict, exposure to choke points, increasingly defending against climate risks.” Specifically, that means governments and companies paying for modern defense, rerouting supply chains around concentrated chokepoints, and hardening infrastructure against extreme weather. He attached no numbers, which makes it a broader and less testable claim than his AI forecast.
Limits Investors Should Know
- Earnings season has barely opened. Every growth figure here is an estimate.
- A forecast of this size for one sector leaves little room for disappointment.
- We verified no valuation multiple. The claim that semiconductors trade below their own average multiple is his, and we did not confirm it.
- Strategist forecasts are frequently revised, and we have no record of his prior accuracy.
- Concentration cuts both ways. Index fund owners already hold this trade, chosen or not. Schwab’s Liz Ann Sonders has said market leadership is concentrated in mega-cap tech and AI-related names. SOXX itself charges a 0.33% expense ratio, per its prospectus filed with the SEC.
What Settles the Argument
Two things decide this: hyperscaler capex guidance and the semiconductor earnings reports themselves. Both arrive in the coming weeks, and each will either support Manoukian’s estimates or revise them.
Manoukian thinks chip stocks still look cheap because their earnings are growing faster than their share prices, and he expects bigger hyperscaler budgets to prove it. The risk is that his roughly 150% growth estimate leaves little room for a miss, and the chip fund fell 7.6% in the week through Oct. 12 while the S&P 500 fund edged up.