Where we heard itCNBC, Oct. 13, 2026, the morning the big banks began reporting third-quarter results. Speaker: Benjamin Gerlinger, director of equity research for US large cap and regional banks at Citi.
Benjamin Gerlinger, director of equity research for US large cap and regional banks at CitigroupC, went on CNBC as third-quarter bank earnings got underway and made a contrarian case for Bank of AmericaBAC. “We think Bank of America has been overly punished here. Although trading the update they did provide was a little bit softer than expected, we think the outlook for just higher interest rates and the three-month five-year spread like we talked about, just the core loans and deposits of the bank, continue to set up a really strong profitability into next year,” said Benjamin Gerlinger. Citi is itself a large bank and competes with Bank of America.
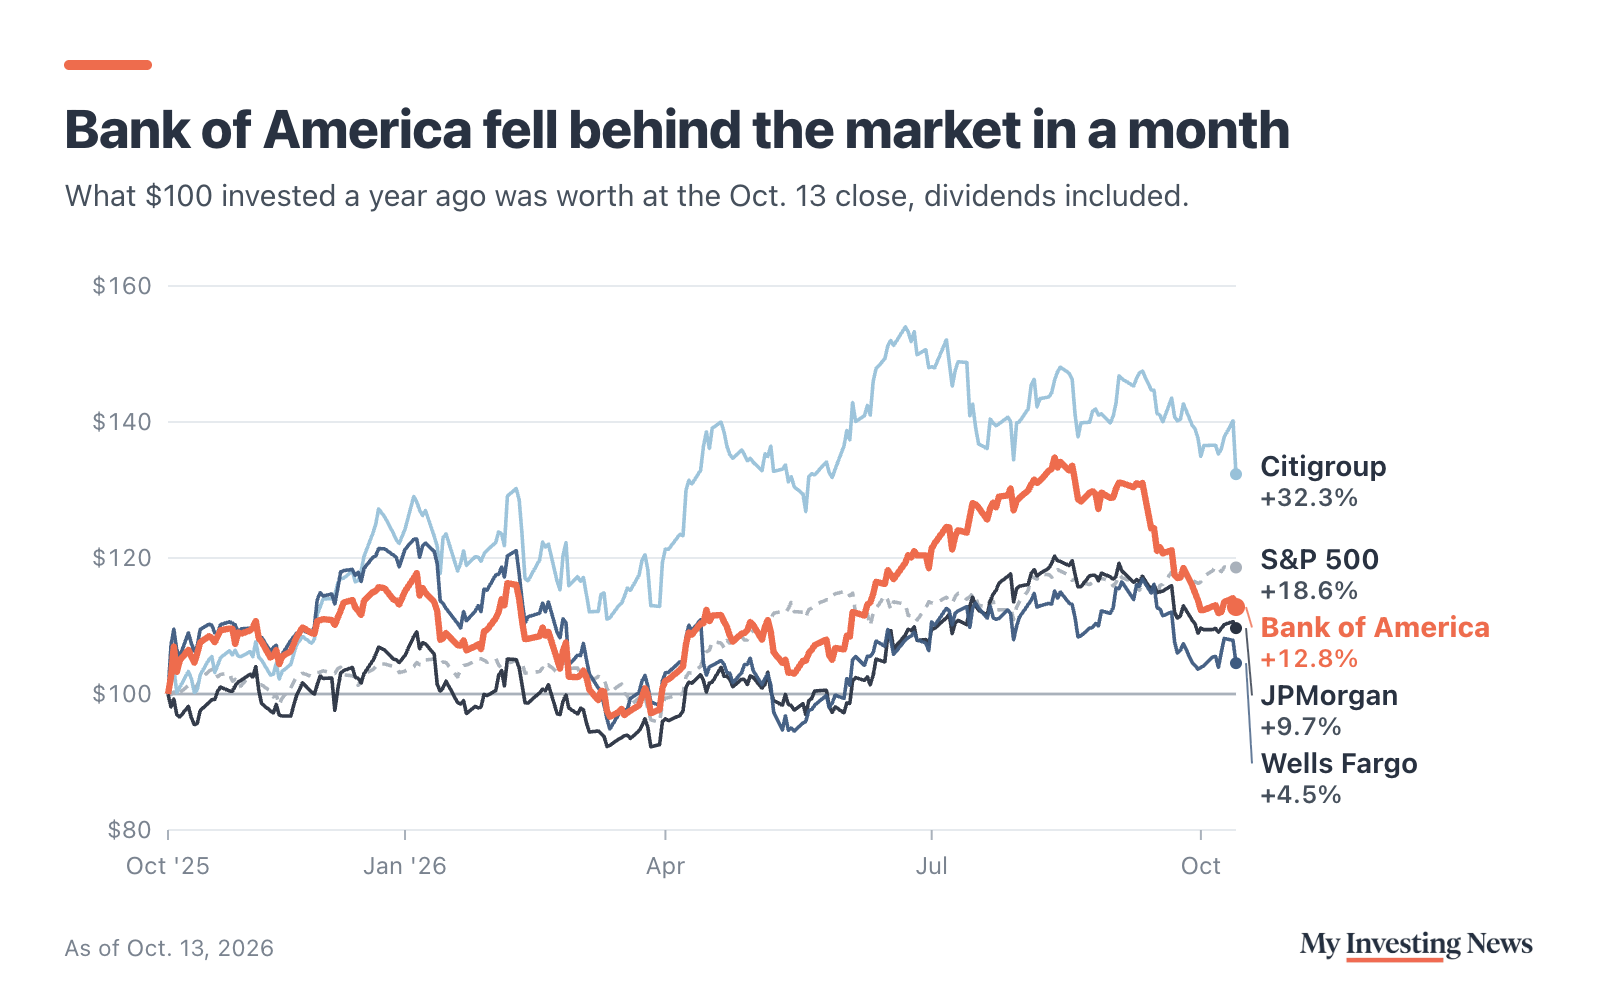
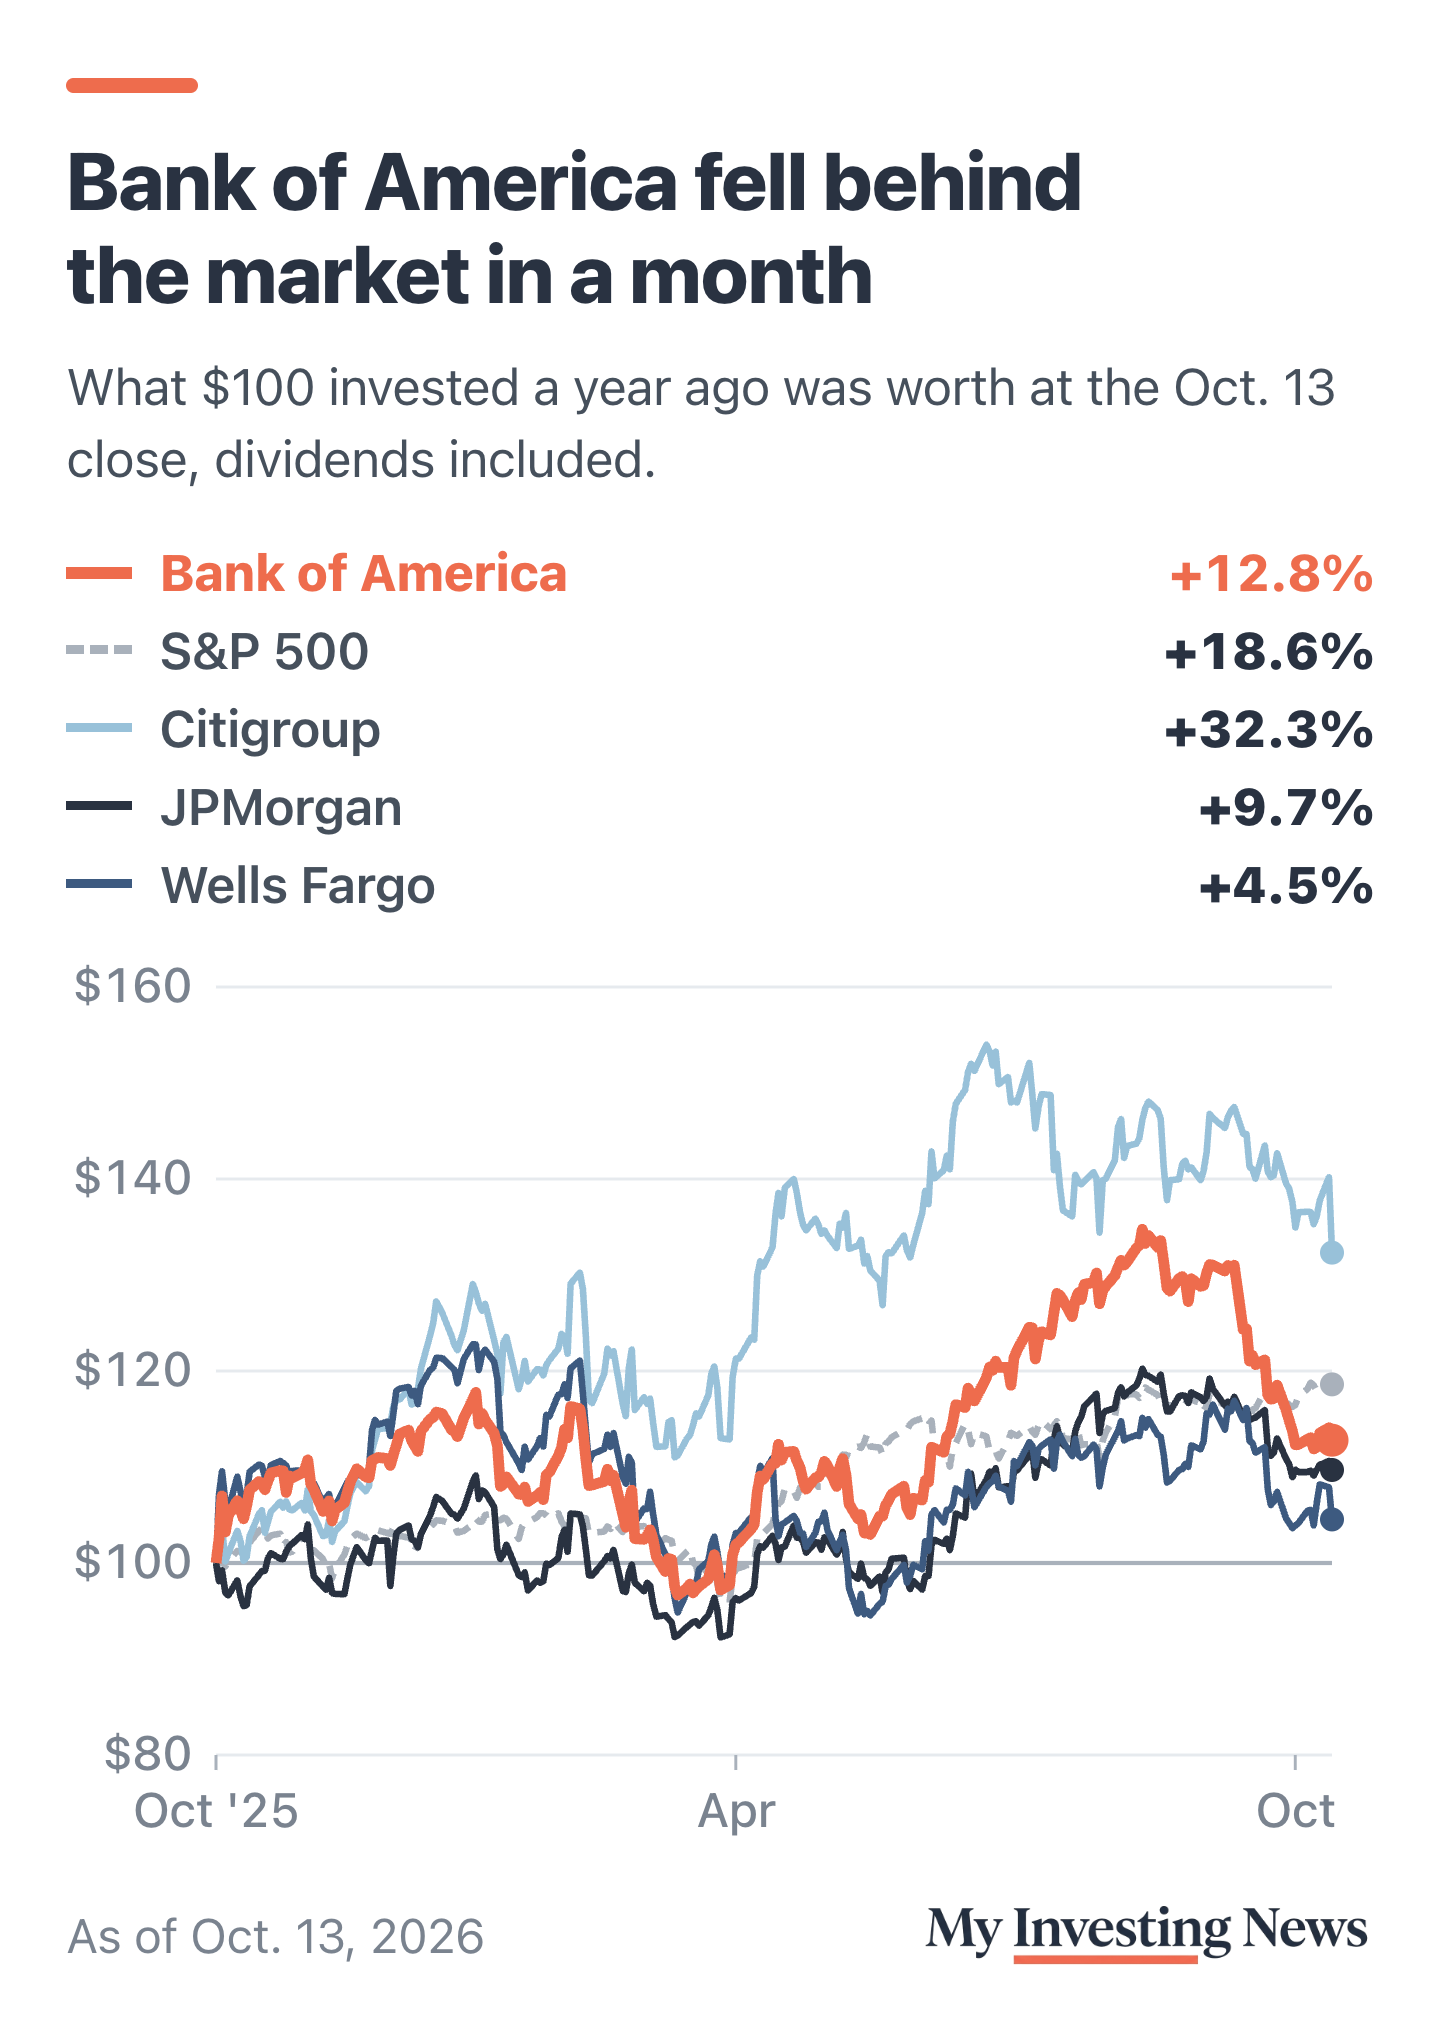
The decline he is responding to is real and recent. Bank of America shares have fallen 13.9% over the past month. The longer view looks different: including dividends, the stock is down 0.3% year to date, up 12.8% over one year and up 41.4% over five years. Nearly all of the damage came in the past month. Someone who bought a year ago is still ahead. Someone who bought a month ago is not. Shares slipped 1.1% on Tuesday, October 13, to close at $53.96.
A Call That Gets Tested Within Hours
Bank of America has announced it will report third-quarter results and host its investor call on October 14. The report is expected before the market opens, though the company has not confirmed that timing. Results will post on the Bank of America investor relations site. A call made the day before the evidence arrives is unusual, and it is useful: readers will know quickly whether Gerlinger was early or wrong.
How Interest Rate Spreads Drive Bank Profits
A bank pays for deposits and earns on loans and securities. Short-term rates largely set what it pays. Longer-term rates drive much of what it earns. When the gap between short and long rates is wide, the business is more profitable. When that gap narrows, profits get squeezed.
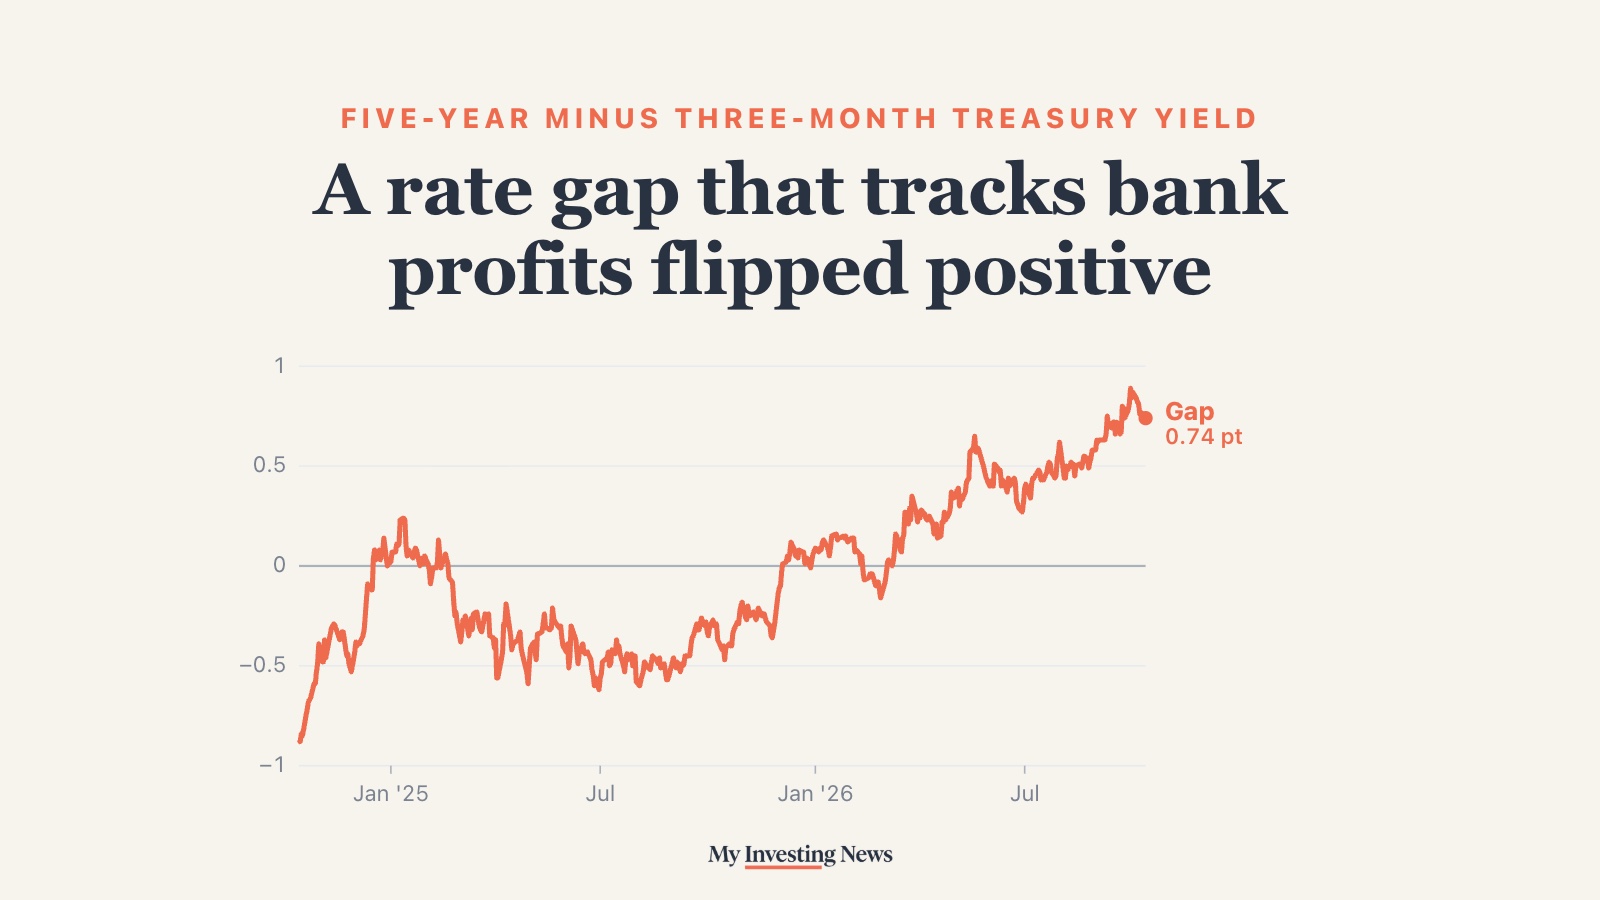
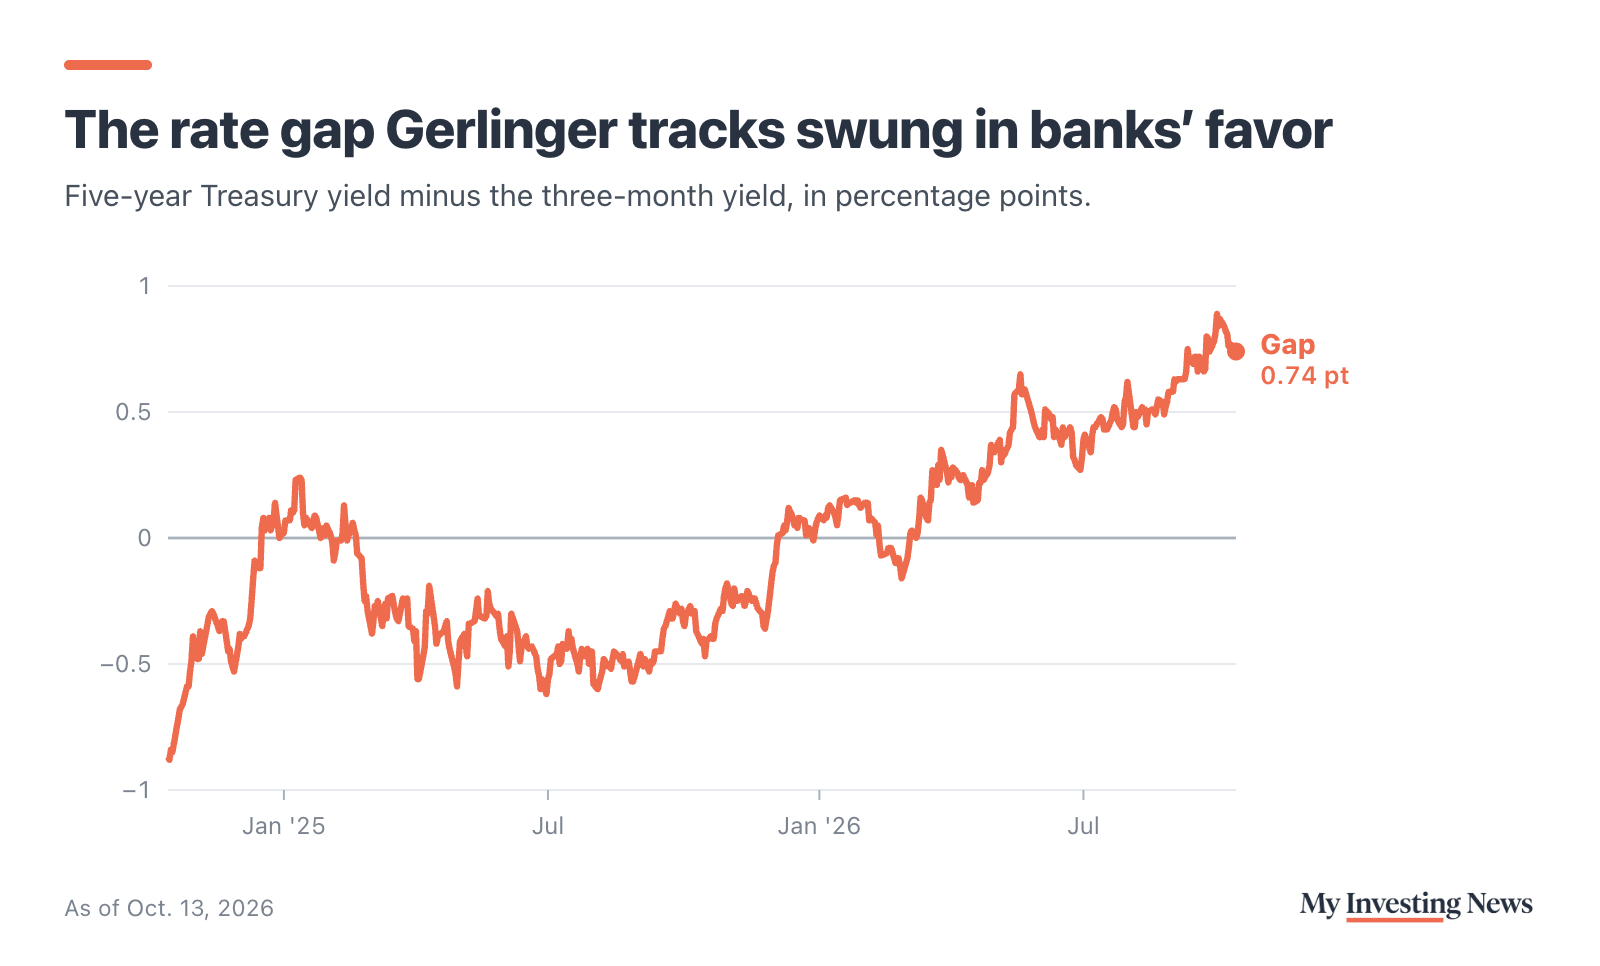
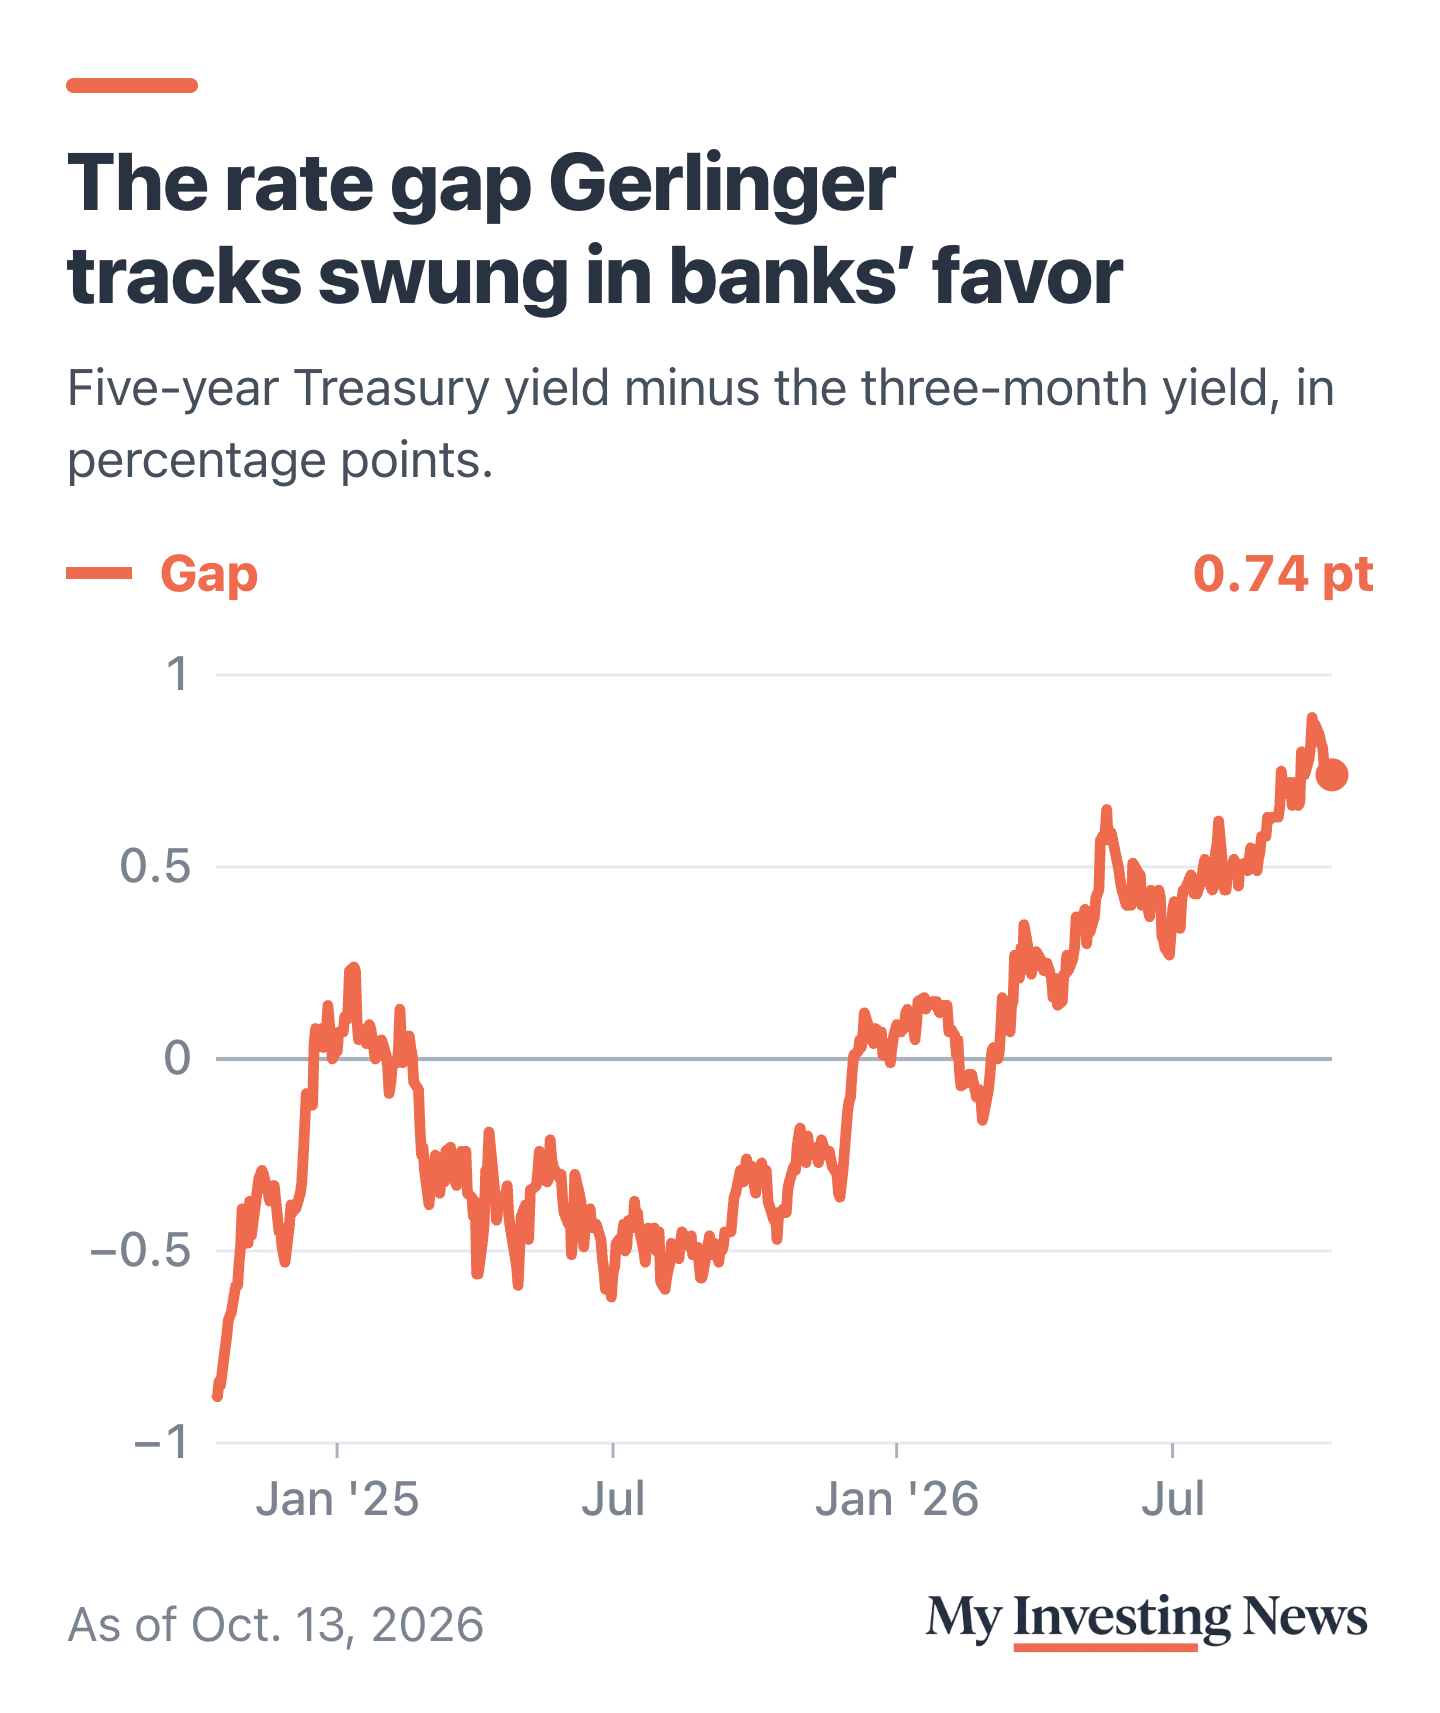
The government’s own data supports the shape his argument needs. On October 9, the Treasury daily yield curve showed the three-month yield at 4.25% and the five-year at 5.02%. The five-year sits above the three-month, which is the configuration his thesis requires. The same data backs his view that this spread has widened over the past year or two: a year earlier, on October 9, 2025, the five-year yielded 0.29 percentage point less than the three-month. For the long end, the ten-year stood at 5.24% and the thirty-year at 5.6% on October 9, a little below the ten-year’s one-year high of 5.31% on October 5.
Treasury yields on Oct. 9, 2026
Headwinds Gerlinger Flagged Himself
Benjamin Gerlinger said fixed income trading at the largest banks has “seemed to struggle a little bit on a linked quarter basis.” Linked quarter means compared with the immediately preceding quarter rather than the same quarter a year earlier.
Gerlinger also said, “Although profitability likely improves over the coming year, the quarter in which there’s an interest rate hike, it does show a little bit of noise in the quarter.” The mechanism: deposit costs tend to reprice faster than loan yields, so the transition period can look worse than where the bank ends up.
Gerlinger added that “the third quarter is not shaping up to be the continuation people had previously expected,” partly due to rates and partly because AI names are going to market on a different timeline than people had perceived. Investment banking fees depend on deals actually closing. A delayed listing pushes the fee into a later period, where it can still be booked.
Gerlinger argues the market has priced near-term problems as permanent while the structural setup improves. The argument holds together, and it is also the case analysts routinely make for stocks they like after a drop. Treat it as a thesis that still needs evidence.
Three Things to Watch in Tomorrow’s Report
- Trading revenue against the prior quarter, since Gerlinger flagged softness there.
- Whether investment banking revenue shows deals slipping into later quarters.
- Management commentary on deposit costs, the mechanism his entire thesis turns on.
Risks on the Other Side of the Call
A sharp one-month decline sometimes means the market is wrong and sometimes means the market knows something. The move itself does not tell you which. Gerlinger’s “overly punished” is a judgment about price against value, and a price decline cannot establish it.
Analyst calls carry no guarantee, and a single TV segment offers no view of Gerlinger’s track record. The yield curve supporting his thesis is a snapshot, and rate expectations shift faster than bank balance sheets. Credit quality also sits underneath everything: wider spreads help a bank only if borrowers keep paying, and credit conditions remain a key variable to monitor.
Some investors see a longer-term threat to the same spread income. Investor Jordi Visser has argued that AI agents and instant settlement could squeeze what banks earn on deposits.
Analyst calls can take several quarters to play out. This one starts getting tested tomorrow morning.
Gerlinger thinks the market overreacted to Bank of America’s 14% slide over the past month, and Treasury data backs the widening rate gap his case rests on. The risks are softer trading and delayed deals in the near term, and a rate gap that can narrow as quickly as it widened.