Where we heard itCNBC’s Squawk Box, Oct. 14, 2026. Speaker: Michael Fertik, founder and managing partner of Verdict Capital. Watch at CNBC
Michael Fertik, founder and managing partner of Verdict Capital, went on CNBC’s Squawk Box on October 14, 2026 to talk about Anthropic’s expected November IPO. His view is that the AI race is still wide open: “There are many astonishingly interesting companies that could potentially overtake Anthropic. Can you believe that? Can you imagine? Can you think about that? Overtake Anthropic in areas of models, in areas of learning in the next few years. So I think we’re still in the first inning of this whole thing.”
Reports say the IPO could value Anthropic at $2 trillion, which would make it the largest IPO in history, edging out SpaceX. Anthropic is privately held and has no listed shares, so individual investors cannot buy it today. OpenAI is also private. The offering is expected and reported. It has not priced.
Fertik’s Projection Next to the Reported Numbers
Michael Fertik pointed to a forward figure: “It looks like they are projecting over $100 billion of revenue run rate in just the next few months.” He added that his own count puts somewhere between 100 and 200 companies worldwide at that revenue level.
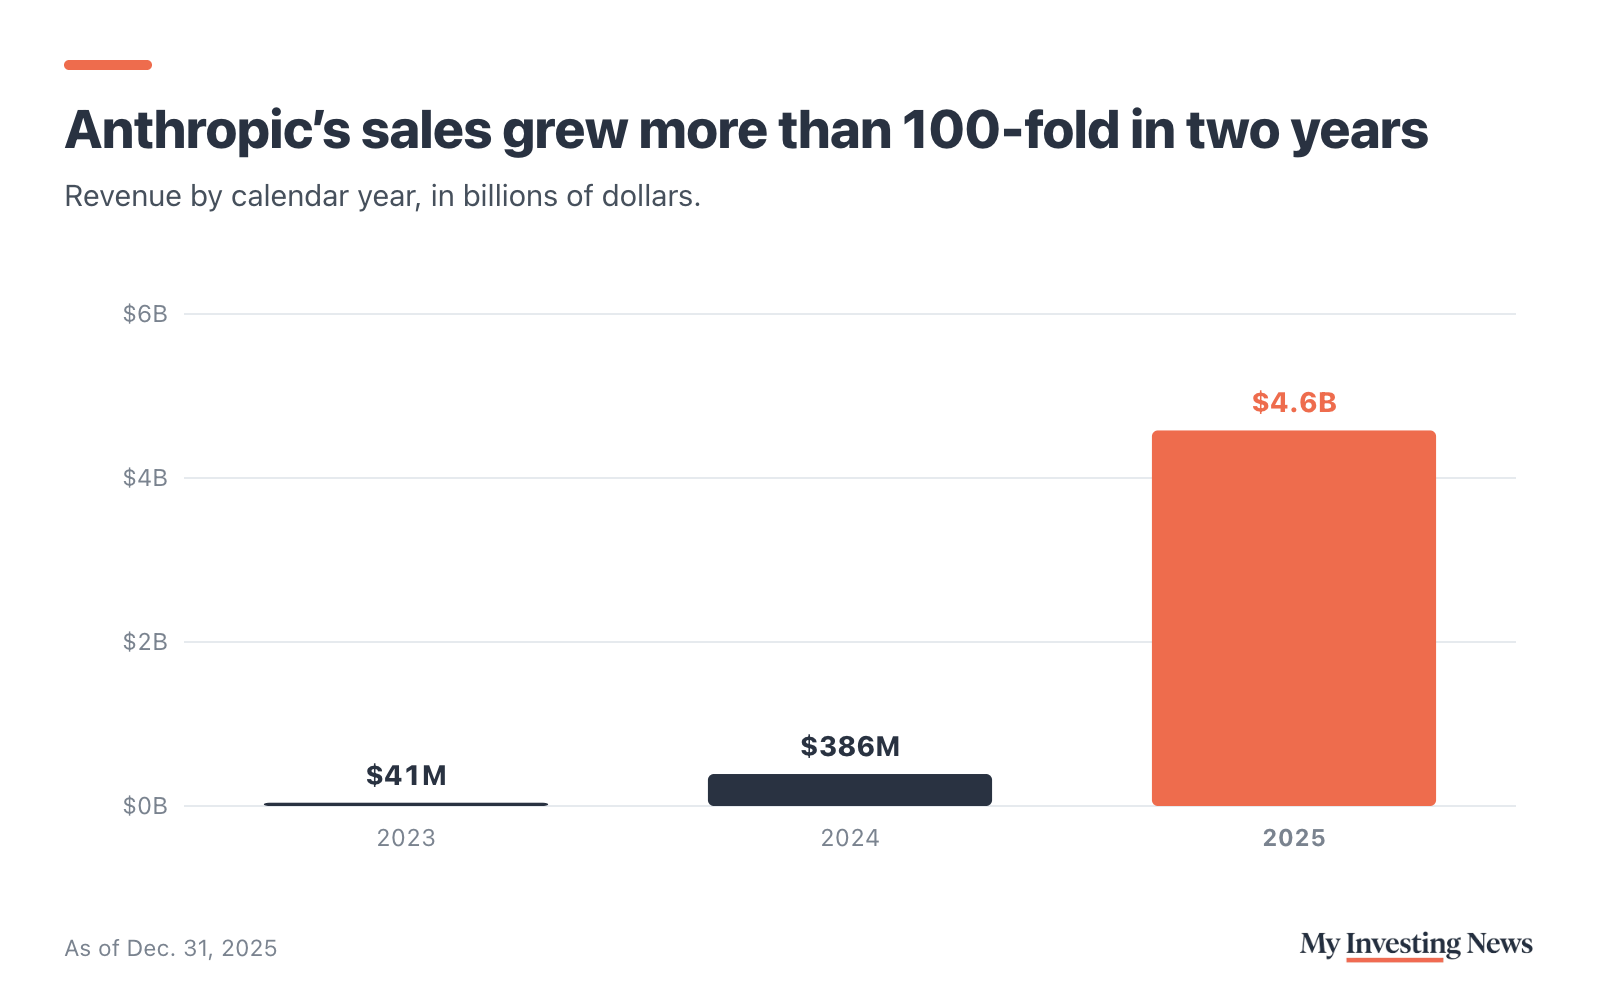
Here is what Anthropic’s IPO prospectus reports, according to The Motley Fool’s coverage on Yahoo Finance:
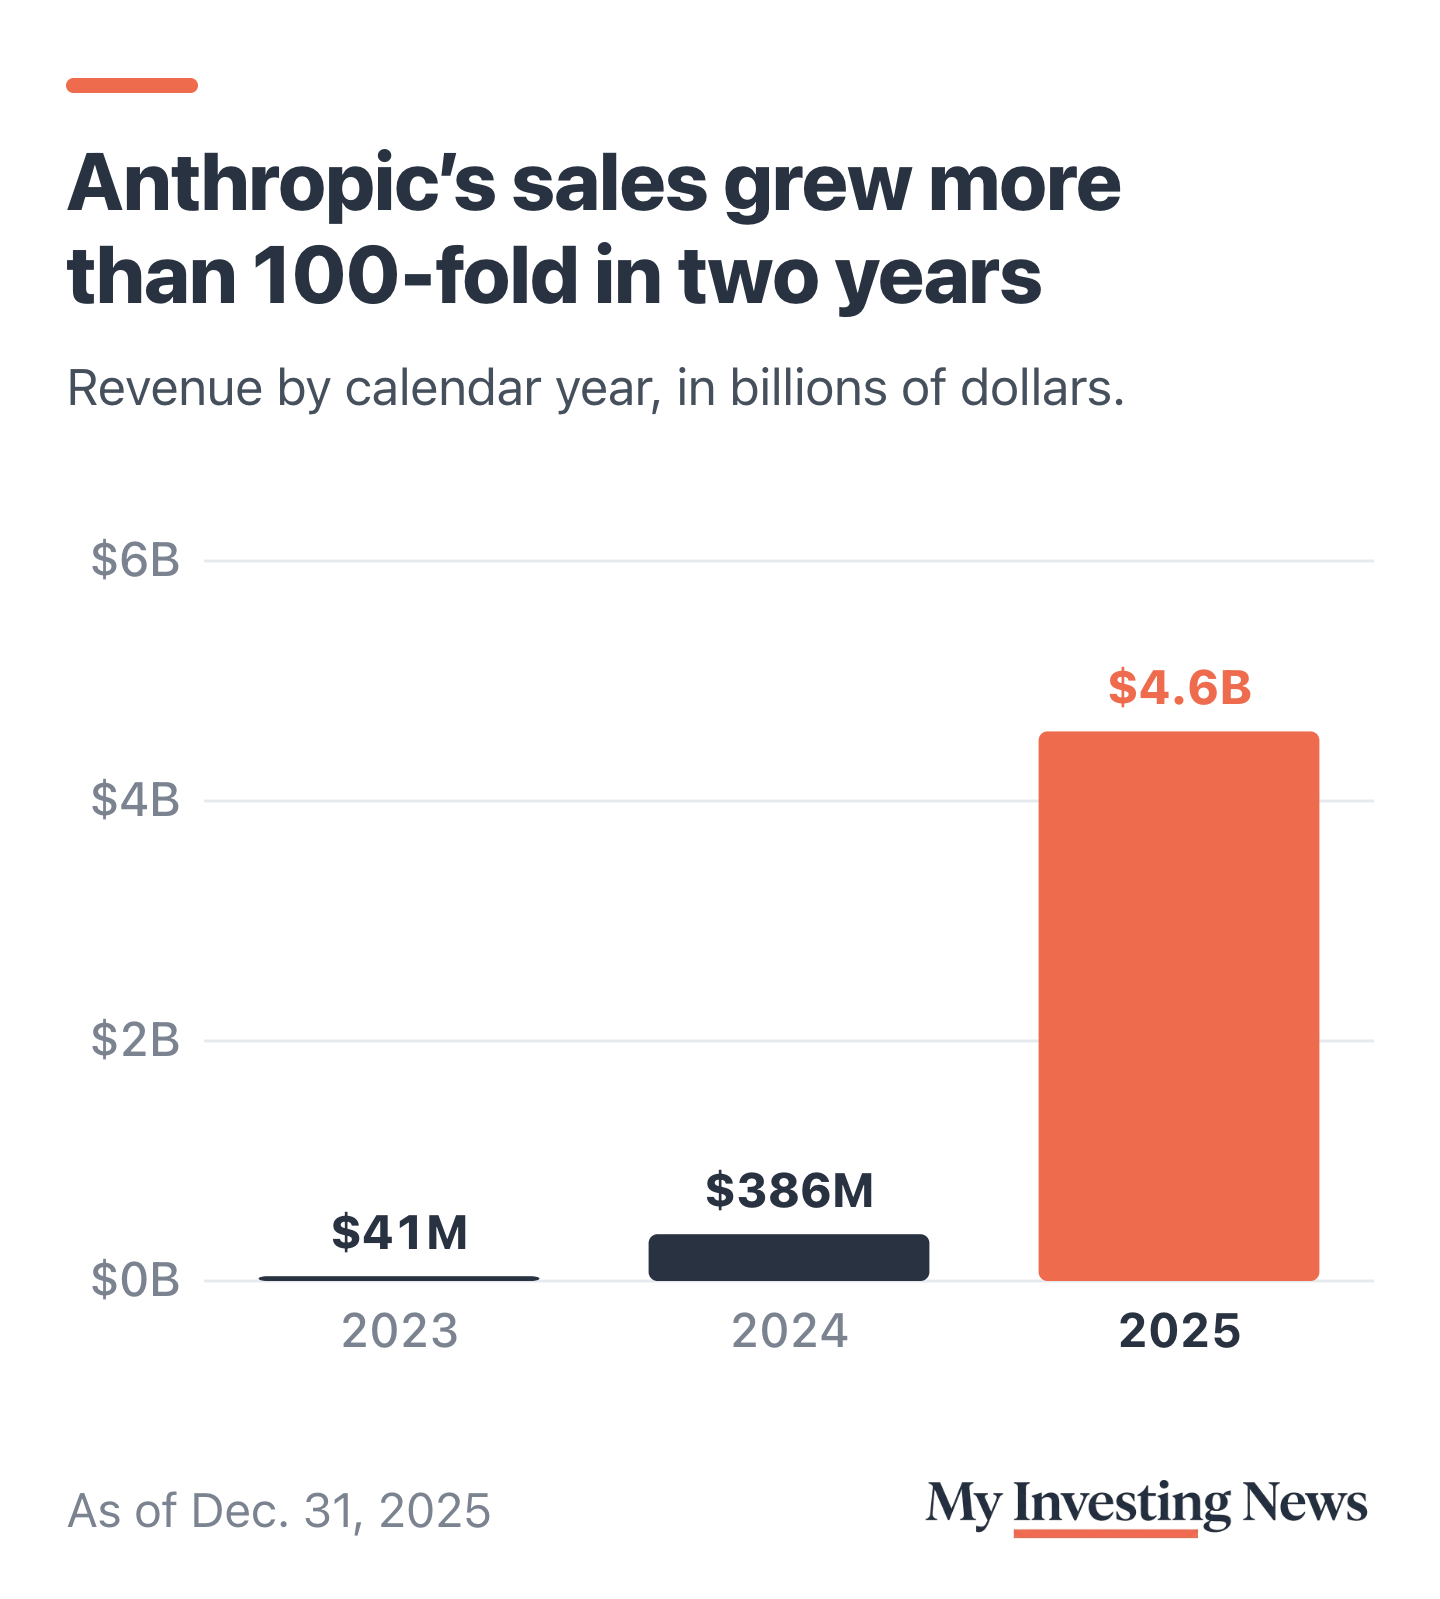
- 2025 revenue: $4.6 billion, up about 1,090%
- Net loss: $42 billion
- Portion of that loss from an accounting charge: around $34 billion
- Operating loss: around $8 billion
These are two different measures. A run rate takes a recent period, often a single month, and projects it across a full year. Reported revenue is what the company actually booked over the past year. Fertik’s figure is a forward projection. The prospectus figure is trailing and audited. Investors considering a $2 trillion valuation should keep the two separate. The labs don’t even count run rates the same way: a Bloomberg reporter has explained that Anthropic reports gross numbers and OpenAI reports net.
Heavy Compute Bills Leave the Leader Exposed
The prospectus shows Anthropic spent $7.3 billion on compute and infrastructure in 2025, out of total operating expenses of $12.65 billion. That puts compute at 58% of operating costs. All of that spending flows to the power, cooling, and networking suppliers behind the data centers.
Where Anthropic’s 2025 operating costs went
Fertik’s argument relies on that number: “Let’s say OpenAI was like the IBM supercomputer, first generation of AI model company, and Anthropic was like the internet, the cloud, the multi-agent architecture model. There are still three, four, and five more generations to come, and we’re already aware of them. Their costs are often a fraction of what the prior generations are.” If cheaper architectures keep showing up, the company carrying the largest compute bill has the most to lose when its pricing gets undercut.
Open-Weight Momentum Brings Meta Back Into the Race
A Squawk Box anchor pointed to a chart showing open-weight models’ share of token use going from 20% to 80% over 12 weeks, with closed-weight models moving the opposite way. No independent source was cited for those figures. The anchor also noted that Meta PlatformsMETA, counted out a month or two earlier, is back in the conversation. Fertik answered that the future “may not be as bright for Anthropic as it is for some of the people coming after them.” Reflection, a startup backed by Nvidia, is betting on the same shift with an open-weight model called Beam.
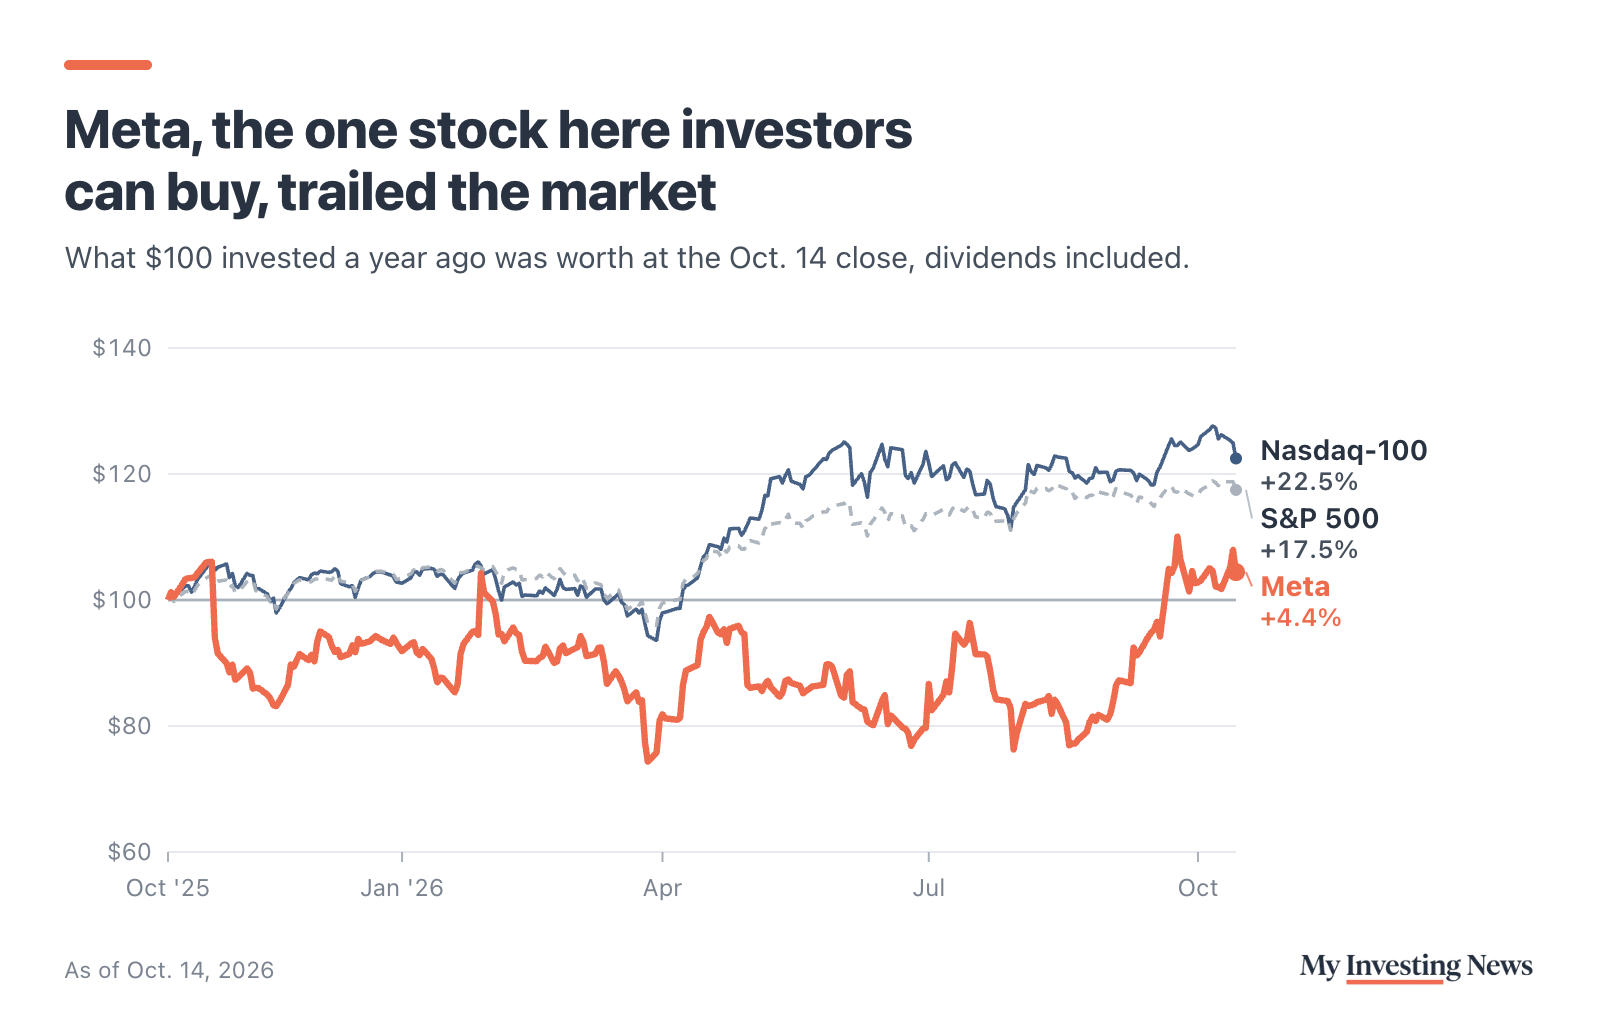
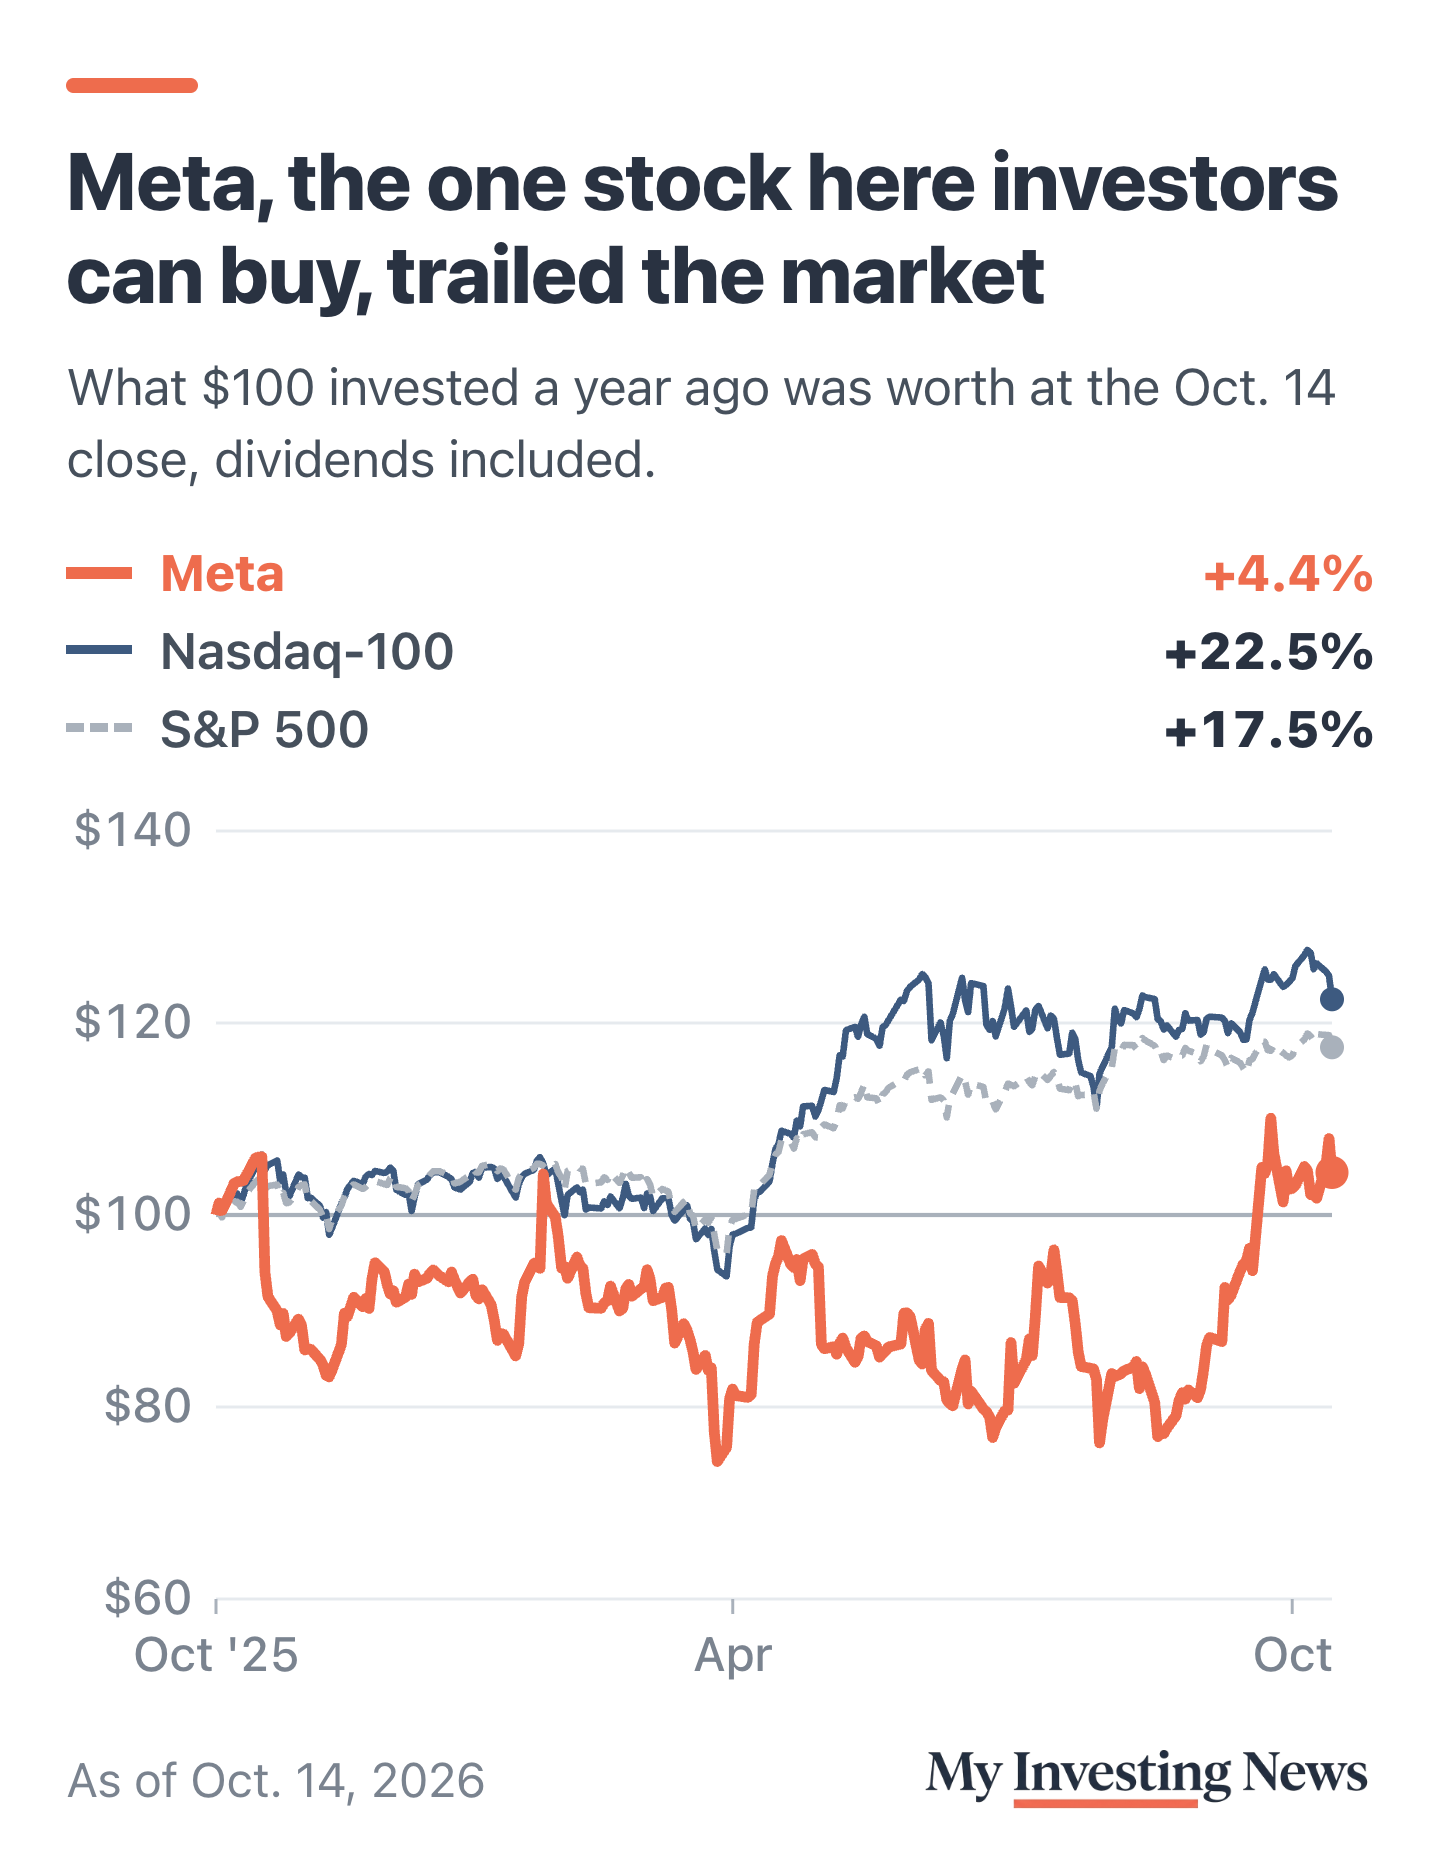
Meta is the one name in this story that investors can buy. Meta Platforms closed at $737.54 on October 14, down 3.3% that session. The stock was up 10.8% over the past month and 11.7% year to date. Meta’s Q2 2026 earnings release reported capital expenditures of $30.12B for the quarter, and the company expects $130 billion to $145 billion for full-year 2026. On the earnings call, Meta’s chief executive admitted the limits of open models: “Right now, the open source models are not as strong as the frontier models.”
The Capital Raise Versus the Price
On the show, the anchor argued that how much money the IPO brings in matters more than where it prices: “Look, these guys need to raise hundreds of millions of dollars in capital. That to me is the most critical piece of it.” Fertik didn’t pick a number: “It’s not really my business to know whether 1.5 versus 1.8 versus 2.2 trillion is the right price.” When compute makes up most of a company’s costs, new capital pays for the next generation of models. Being off by a few points on valuation matters less. The prospectus also warns of catastrophic or existential risks to humanity, which is an unusual disclosure for a company looking for a record valuation.
Our View: Fertik Has the Better Argument
The filing backs Fertik’s caution. Anthropic’s growth is real, but its leadership costs $7.3 billion a year in compute, and that kind of spending is what cheaper rivals can undercut. The clearest test will be Anthropic’s first quarterly report as a public company. If the operating loss is shrinking from around $8 billion while compute’s share of costs falls below 58%, the lead is holding. If neither happens, the first inning is still being played.
Fertik thinks Anthropic’s lead is real but far from locked, because newer generations of AI companies may do the work at a fraction of the cost. The risk shows in Anthropic’s own numbers: in 2025 it spent $7.3 billion on computing power against $4.6 billion of revenue.