Where we heard itCNBC’s Squawk Box, Oct. 14, 2026. Speaker: Michael Rubin, founder and CEO of Fanatics. Watch at CNBC
Fanatics founder and CEO Michael Rubin went on CNBC’s Squawk Box on October 14, 2026 to defend his company’s push into sports betting: “I fundamentally believe in the betting and gaming business long term. I think it’s very unpopular right now. The next couple of years are going to be very difficult with not only the betting companies, but also the prediction companies all kind of competing for the same customer.”
Fanatics is privately held. It has no ticker, and individual investors cannot buy its shares. Prediction market operators Kalshi and Polymarket are not listed either. Their markets reach beyond sports: in early October, Polymarket priced Republican control of the Senate at about 36%. That leaves public investors with the listed operators, and those stocks are falling hard.
At the Oct. 14 close, DraftKingsDKNG stood at $18.90, down 4.2% on the day, 23.9% over the past month and 45.2% this year. Flutter EntertainmentFLUT, parent of FanDuel, closed at $74.26, down 4.9% on the day, 26.2% over the month and 65.5% this year. Rubin is pricing the future return. The market is pricing the difficult stretch he admits comes first.
Spending War Is Already Hitting Income Statements
Fanatics is spending $350 million on sports betting marketing this year and plans up to $1 billion in 2027, figures CNBC’s Joe Kernen cited as he opened the interview. Rubin estimated that $7 billion will be spent on marketing across U.S. betting and gaming next year, up from about $3 billion last year.
A sportsbook keeps a thin slice of handle (total dollars customers put in play), then hands part of that slice back as sign-up bonuses and loyalty rewards. When more companies chase the same customers, those giveaways and ad rates climb, each new customer costs more and less margin is left over. One rival’s budget ends up as an expense for everyone.
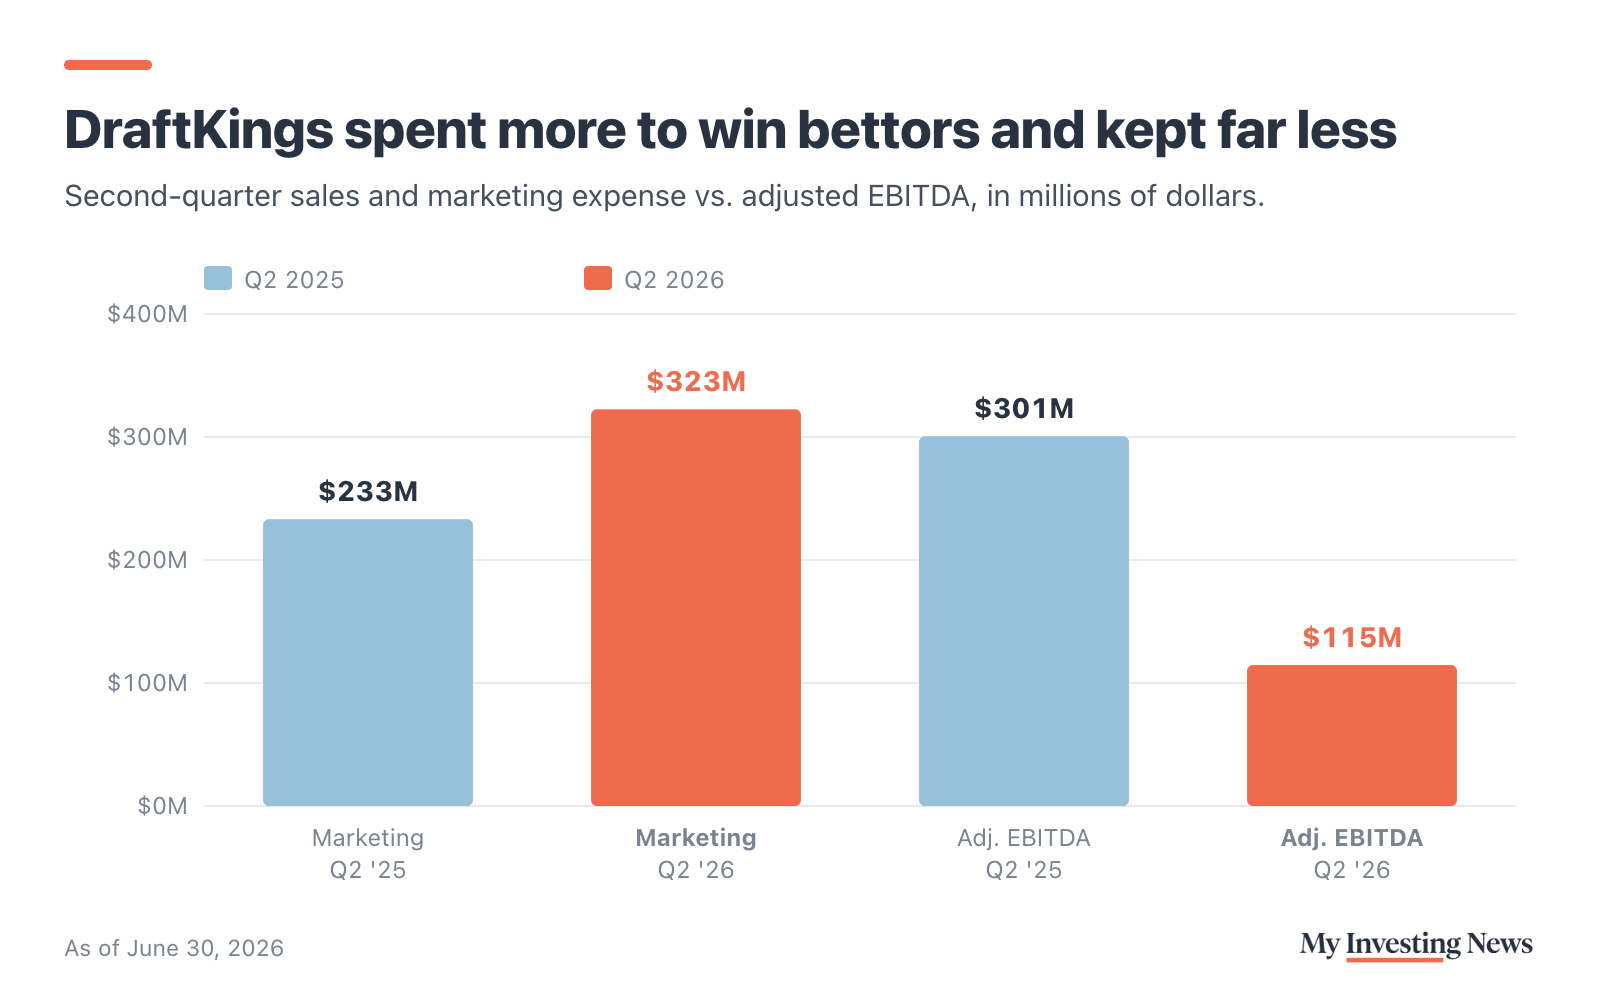
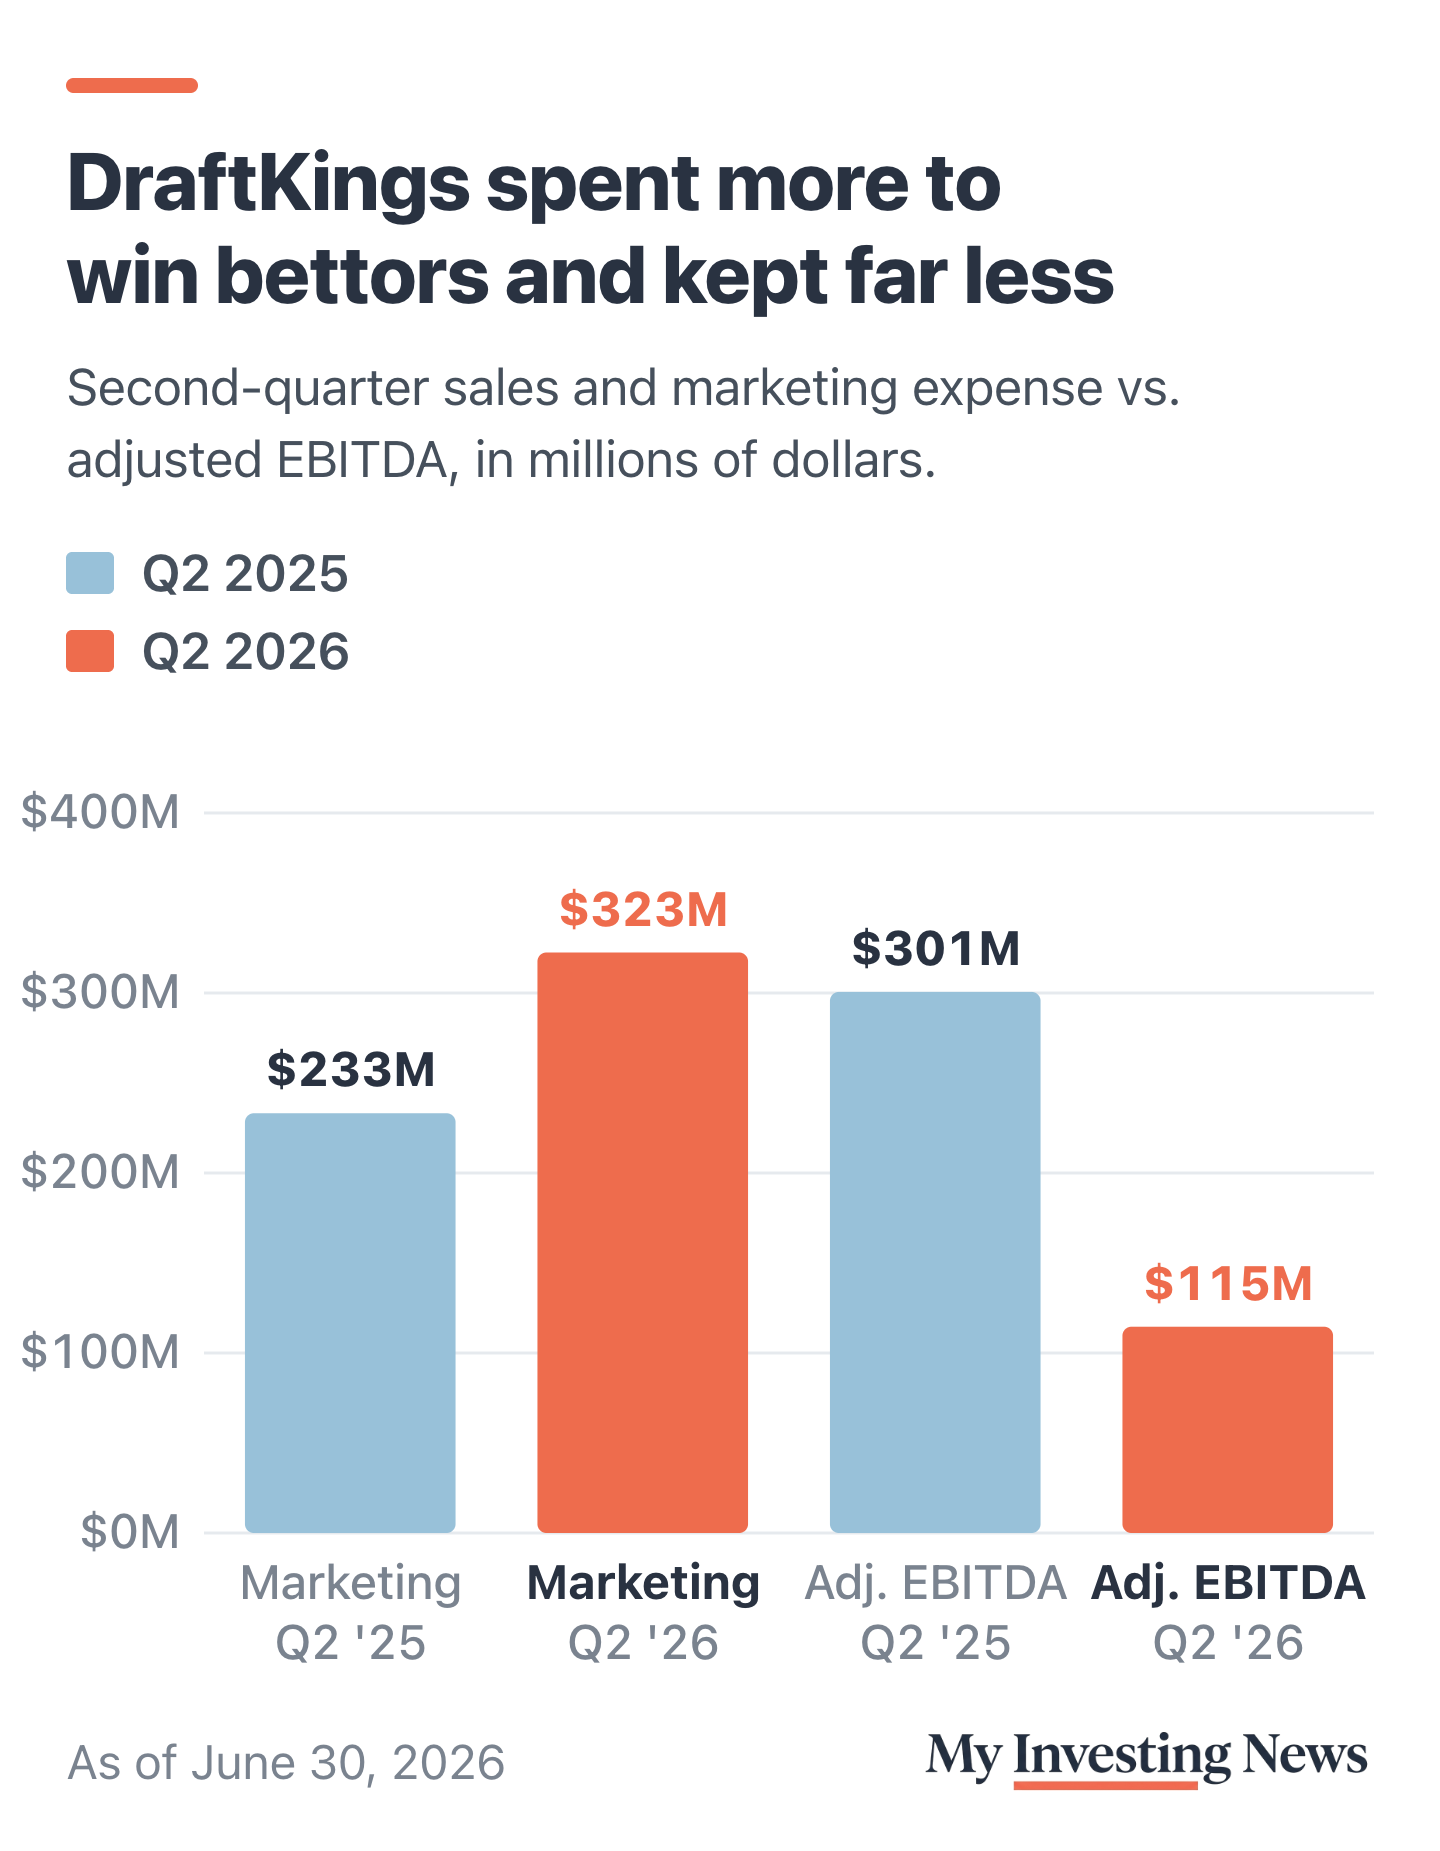
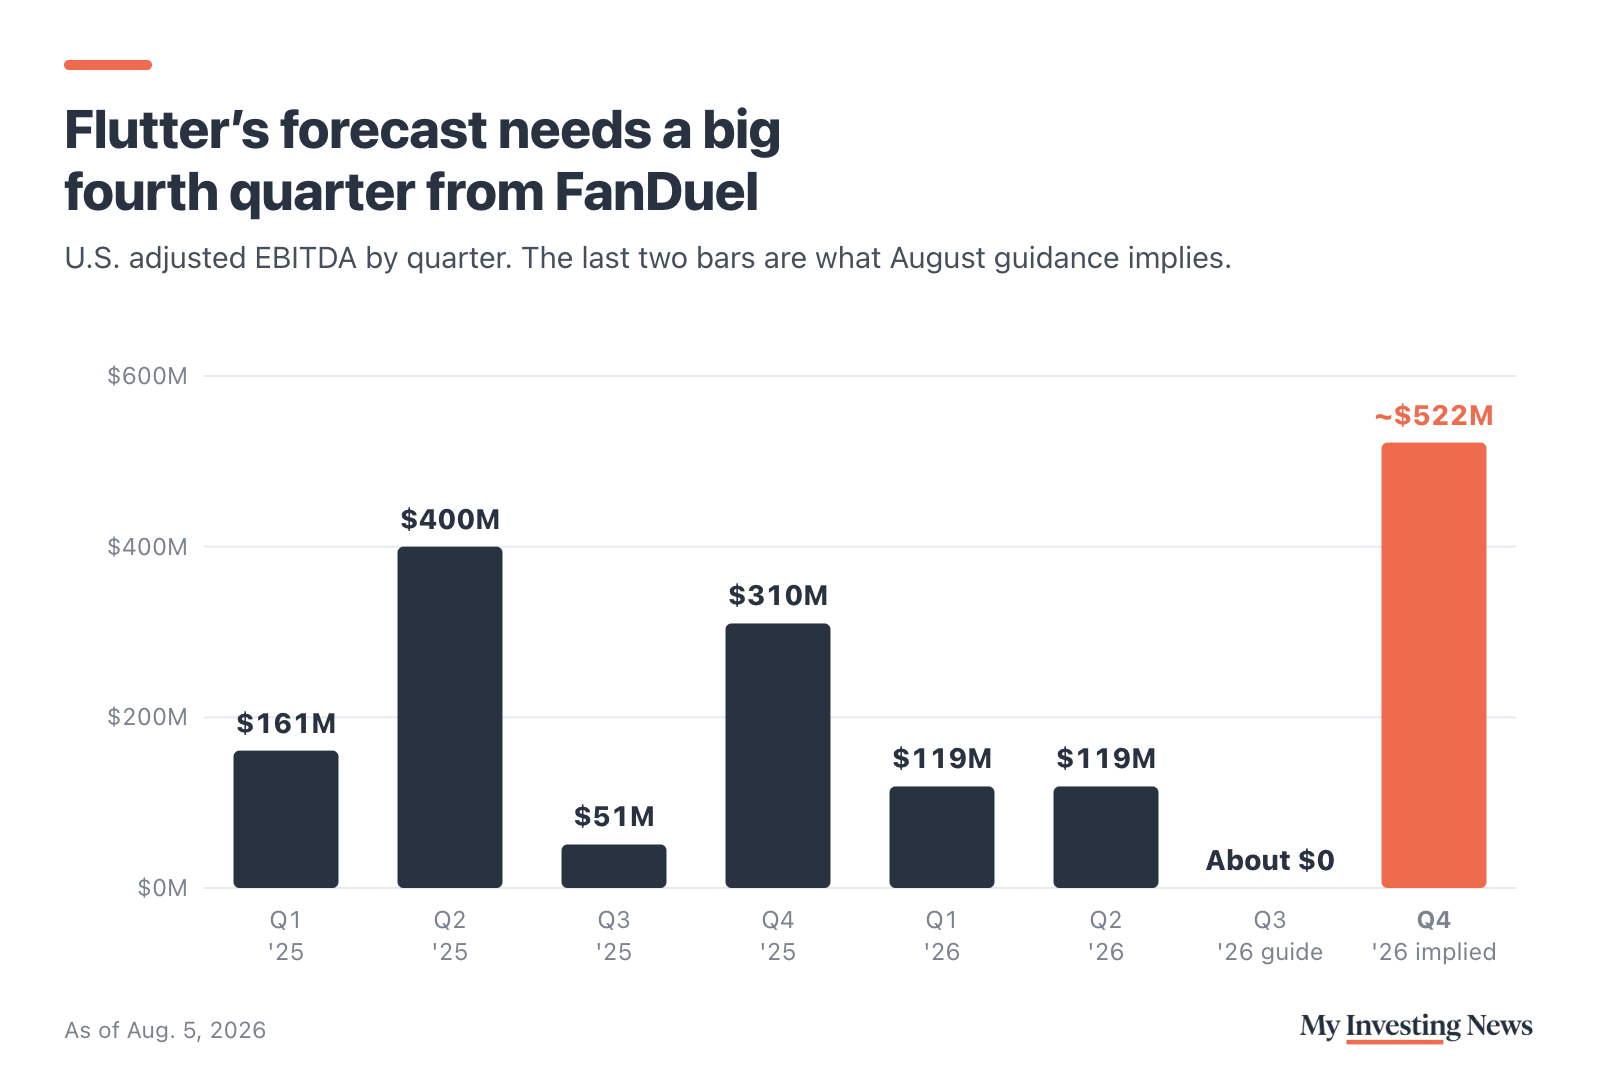
DraftKings already shows the strain. In its second-quarter results, Sports Net Revenue Margin contracted to 6.8% from 8.7%, sales and marketing rose to $322.5M from $233.2M and adjusted EBITDA fell to $114.6M from $300.6M. Adjusted EPS fell to $0.09 from $0.38 a year earlier. Flutter’s US adjusted EBITDA fell 70% to $119M, and the company set aside roughly $270m of adjusted EBITDA for investment to strengthen FanDuel’s sportsbook. Adjusted EBITDA is a figure management controls, and LightShed’s Rich Greenfield has warned that EBITDA can be manipulated in ways cash cannot.
Fanatics’ Ecosystem Pitch Comes With a Catch
Rubin’s case for Fanatics: “We’re the only company really building the digital sports platform. And these businesses really work as one ecosystem for the consumer.” Michael Rubin said Fanatics One has 45 million members, and Rubin said Fanatics will issue more than $2 billion of fan cash next year, with Rubin claiming a 97% to 98% redemption rate within 12 months. Rubin put the commerce business at over $7 billion this year, and Rubin cited $5.5 billion for collectibles. All of these are Rubin’s own claims. None are audited accounts. His funding logic: “So the profits in those businesses allow us to be more aggressive and invest more in the betting and gaming business, because we believe in it long term.”
Cross-subsidy only becomes a moat if the loyalty loop drives Fanatics’ acquisition costs below what pure plays pay. Until that shows up, product profits mainly give Fanatics more time to buy share. DraftKings has no product buffer. It is funding $200 to $300 million of extra Predictions spending out of a core business it expects to produce roughly $1 billion of adjusted EBITDA this year. Flutter has its international business, but leverage stands at 4.3x against a 2.0x to 2.5x target.
The listed leaders, second quarter of 2026
A Third-Place Rival With Deep Pockets Raises Costs for the Leaders
“We believe we need to be number one in whatever we do. So we’re number one in the commerce and fan gear business, we’re number one in the collectibles business. We’re a distant number three in the betting and gaming business. We don’t like that.”
Michael Rubin put Fanatics at approximately 10% of the market. FanDuel holds ~39% US sportsbook GGR share. A challenger paying for growth out of outside profits leaves the leaders two choices: match the promotions or give up customers. Flutter is spending more on customer generosity. DraftKings says it will stick to its strategy and count on promotional efficiency.
Our View and the Numbers to Track
The market has the next 12 months right. Michael Rubin committing up to $1 billion locks in margin pressure through 2027. Flutter’s full-year guidance implies roughly $520 million of US adjusted EBITDA in Q4, and DraftKings needs its Sports Net Revenue Margin to recover toward 8.7% this NFL season. If both happen and FanDuel keeps its share, the leaders are holding off Fanatics. If either one misses, the selloff has further to run.
Rubin believes sports betting is a good long-term business and that Fanatics’ merchandise and collectibles profits let it outspend rivals while it climbs from third place. The risk for investors in the listed leaders is that a richer rival keeps marketing costs high, and both DraftKings and Flutter are already earning far less than a year ago.