Where we heard itCNBC’s Squawk on the Street, 9 a.m. hour, Oct. 14, 2026. Speaker: co-host Jim Cramer. Michael Dell’s comments come from his interview with CNBC’s David Faber, replayed on the show.
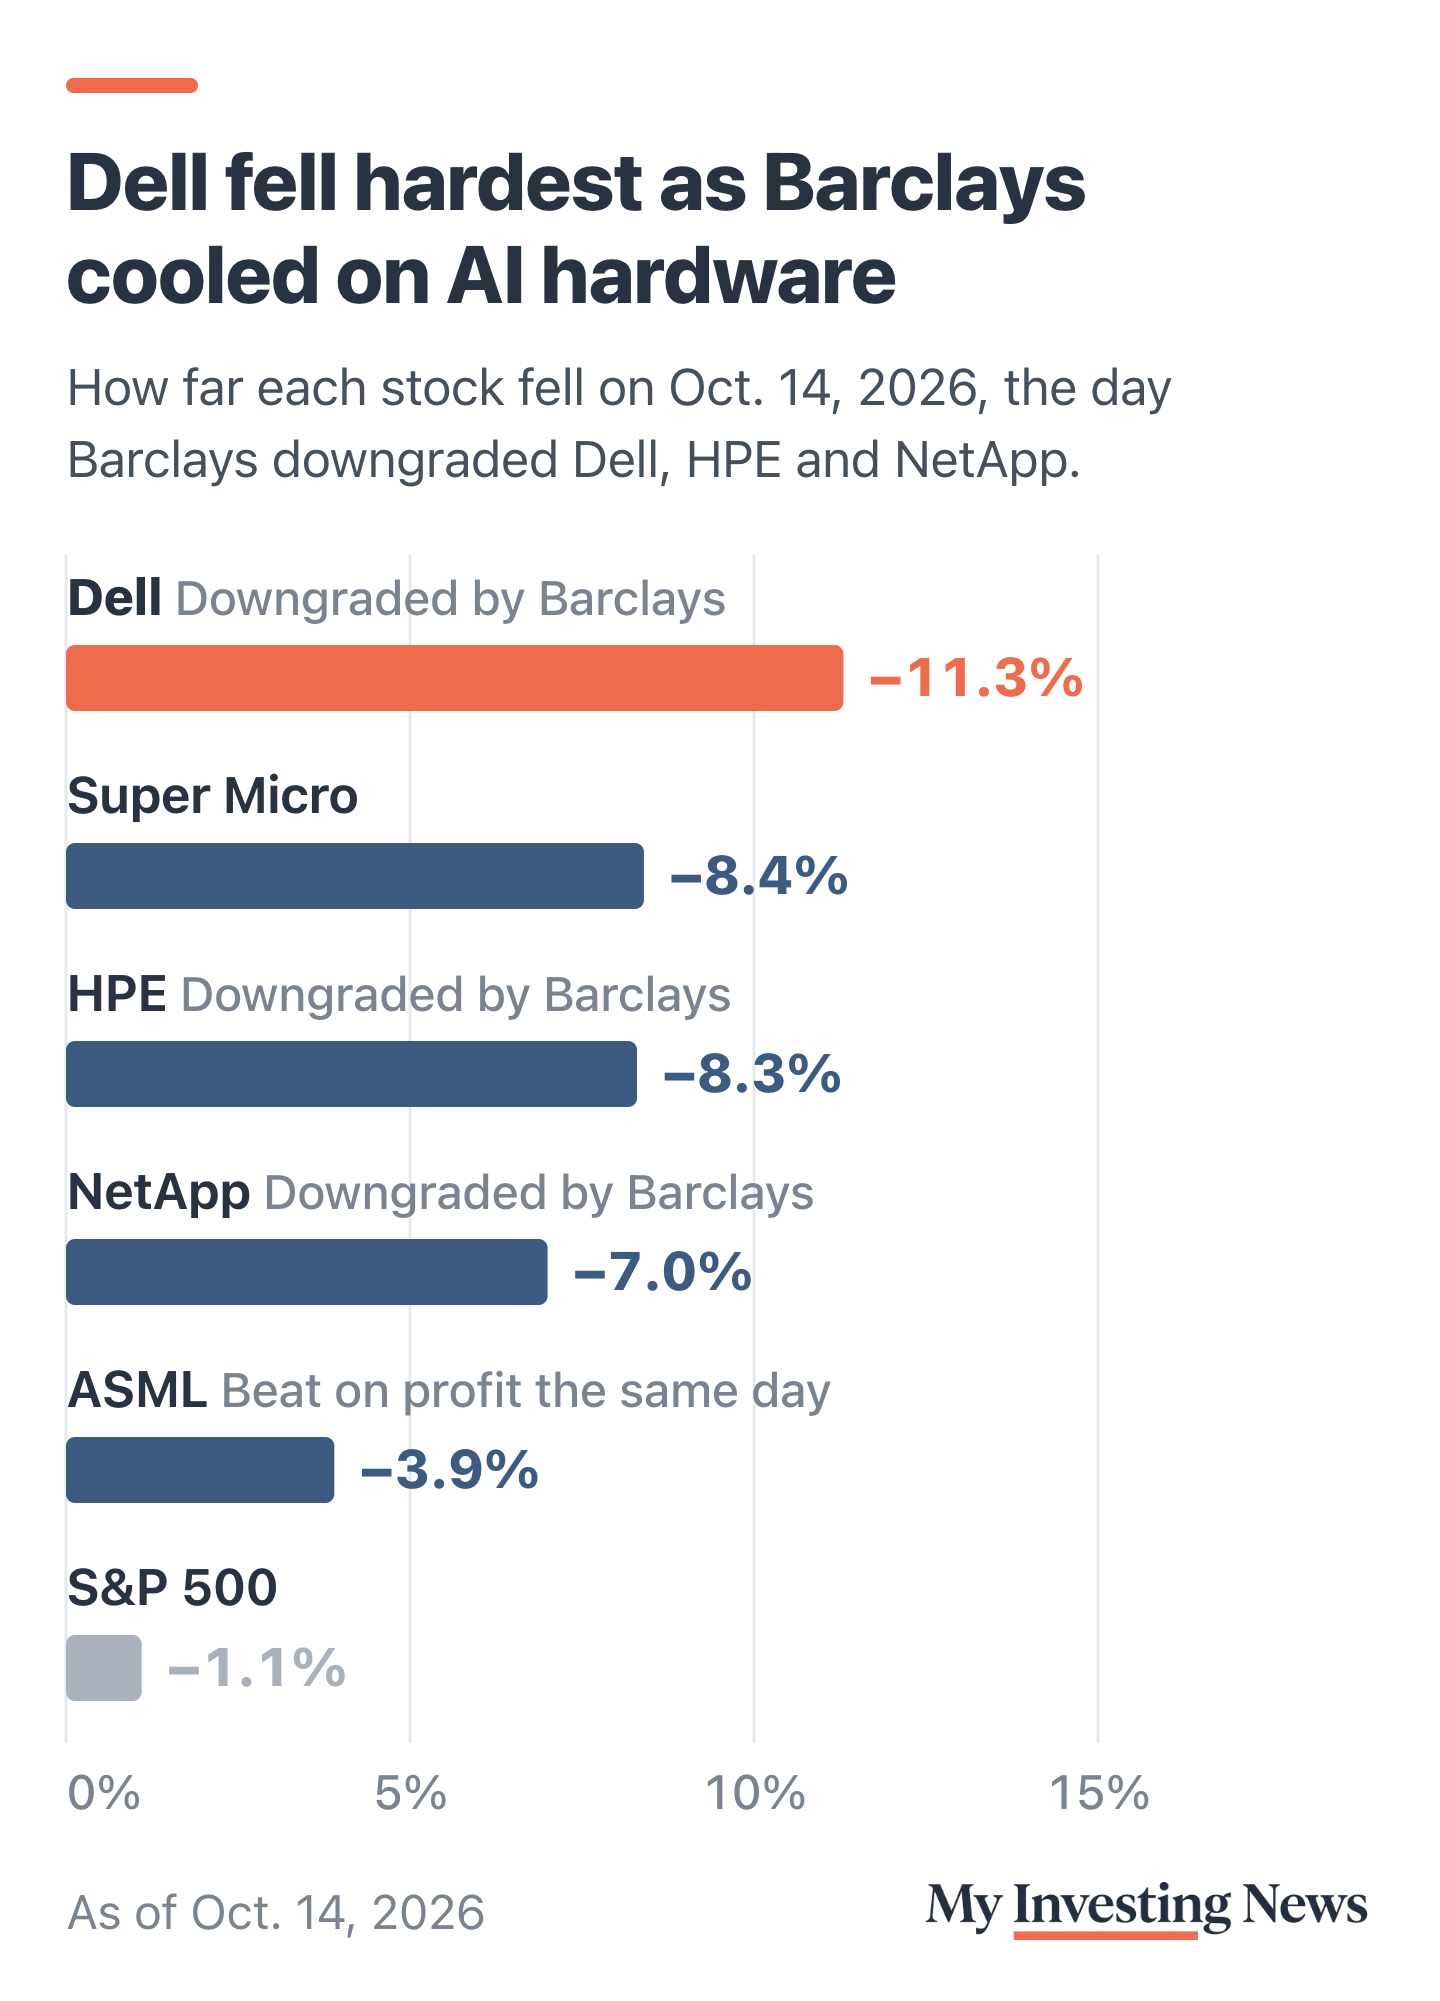
Jim Cramer was on CNBC’s Squawk on the Street on Wednesday, October 14, 2026. He looked at a sharply lower Dell TechnologiesDELL and saw an opening. “Maybe this is an opportunity,” he said, and a few minutes later: “Dell is more an opportunity than not.” Shares closed at $507.93 that day, down 11.3% in the session. Barron’s called it the stock’s worst day in more than a year.
Dell’s Selloff Follows an Enormous Run
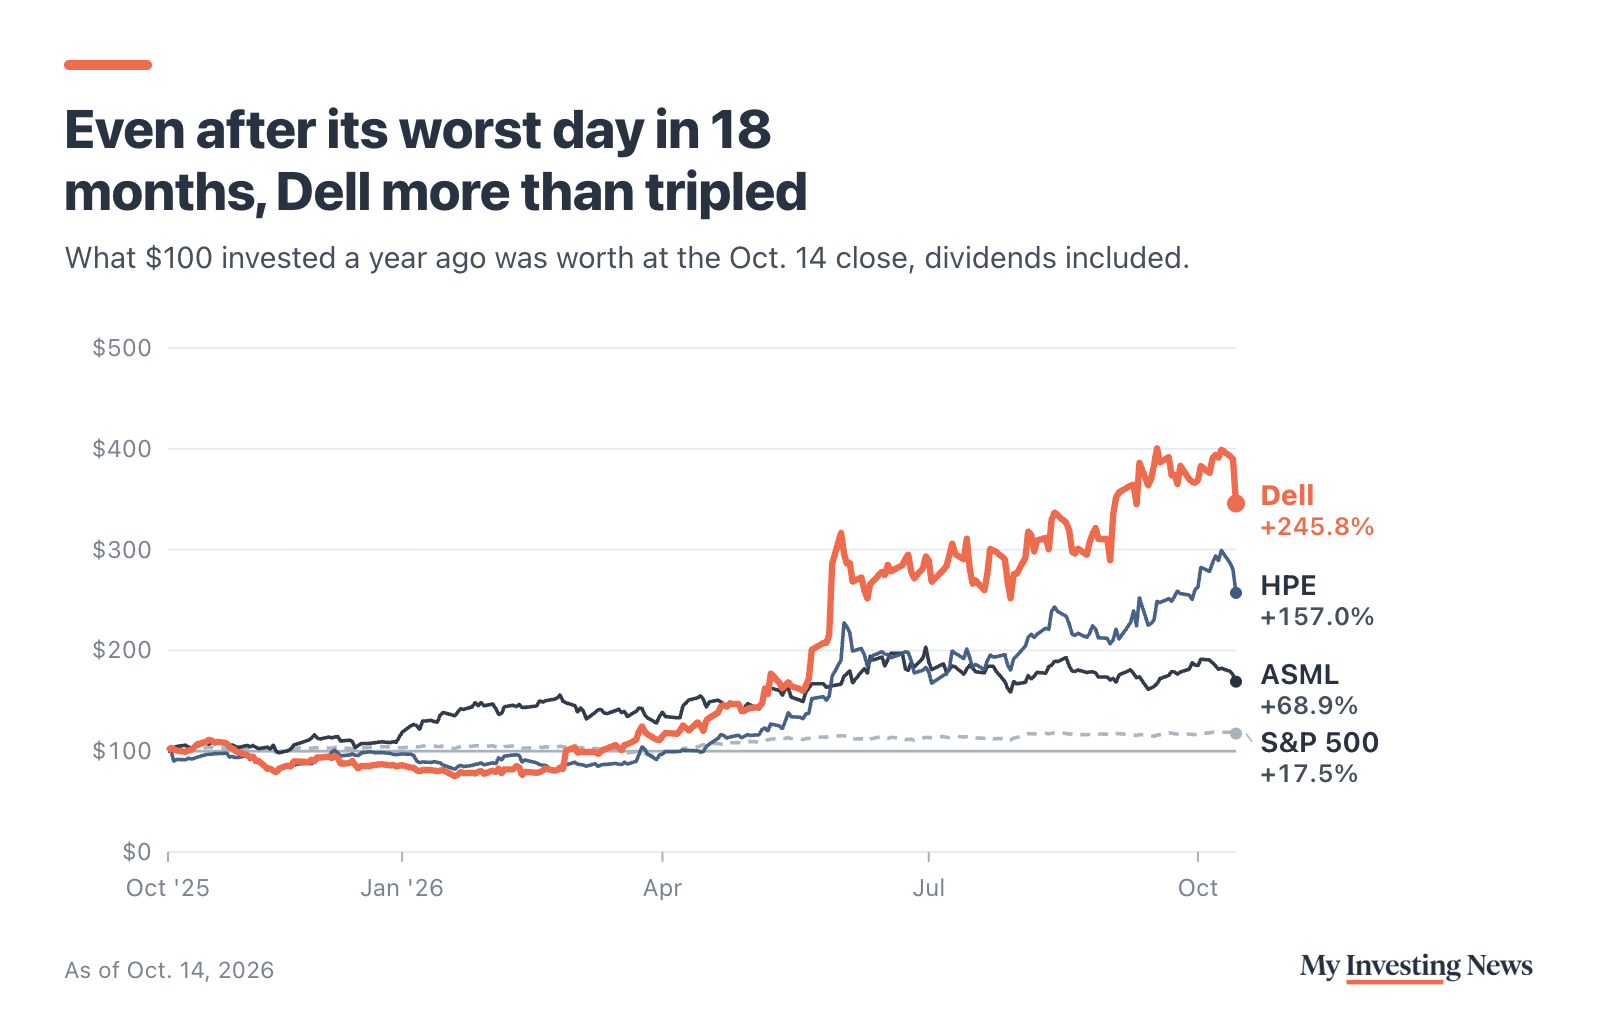
Dell fell 12.3% over the past week, and the stock was still up 303.5% this year at the Oct. 14 close. That context matters most here. Cramer is calling an opportunity in a name that has had a massive run and is now selling off hard, and his call should be considered that way, as a pullback in a leader.
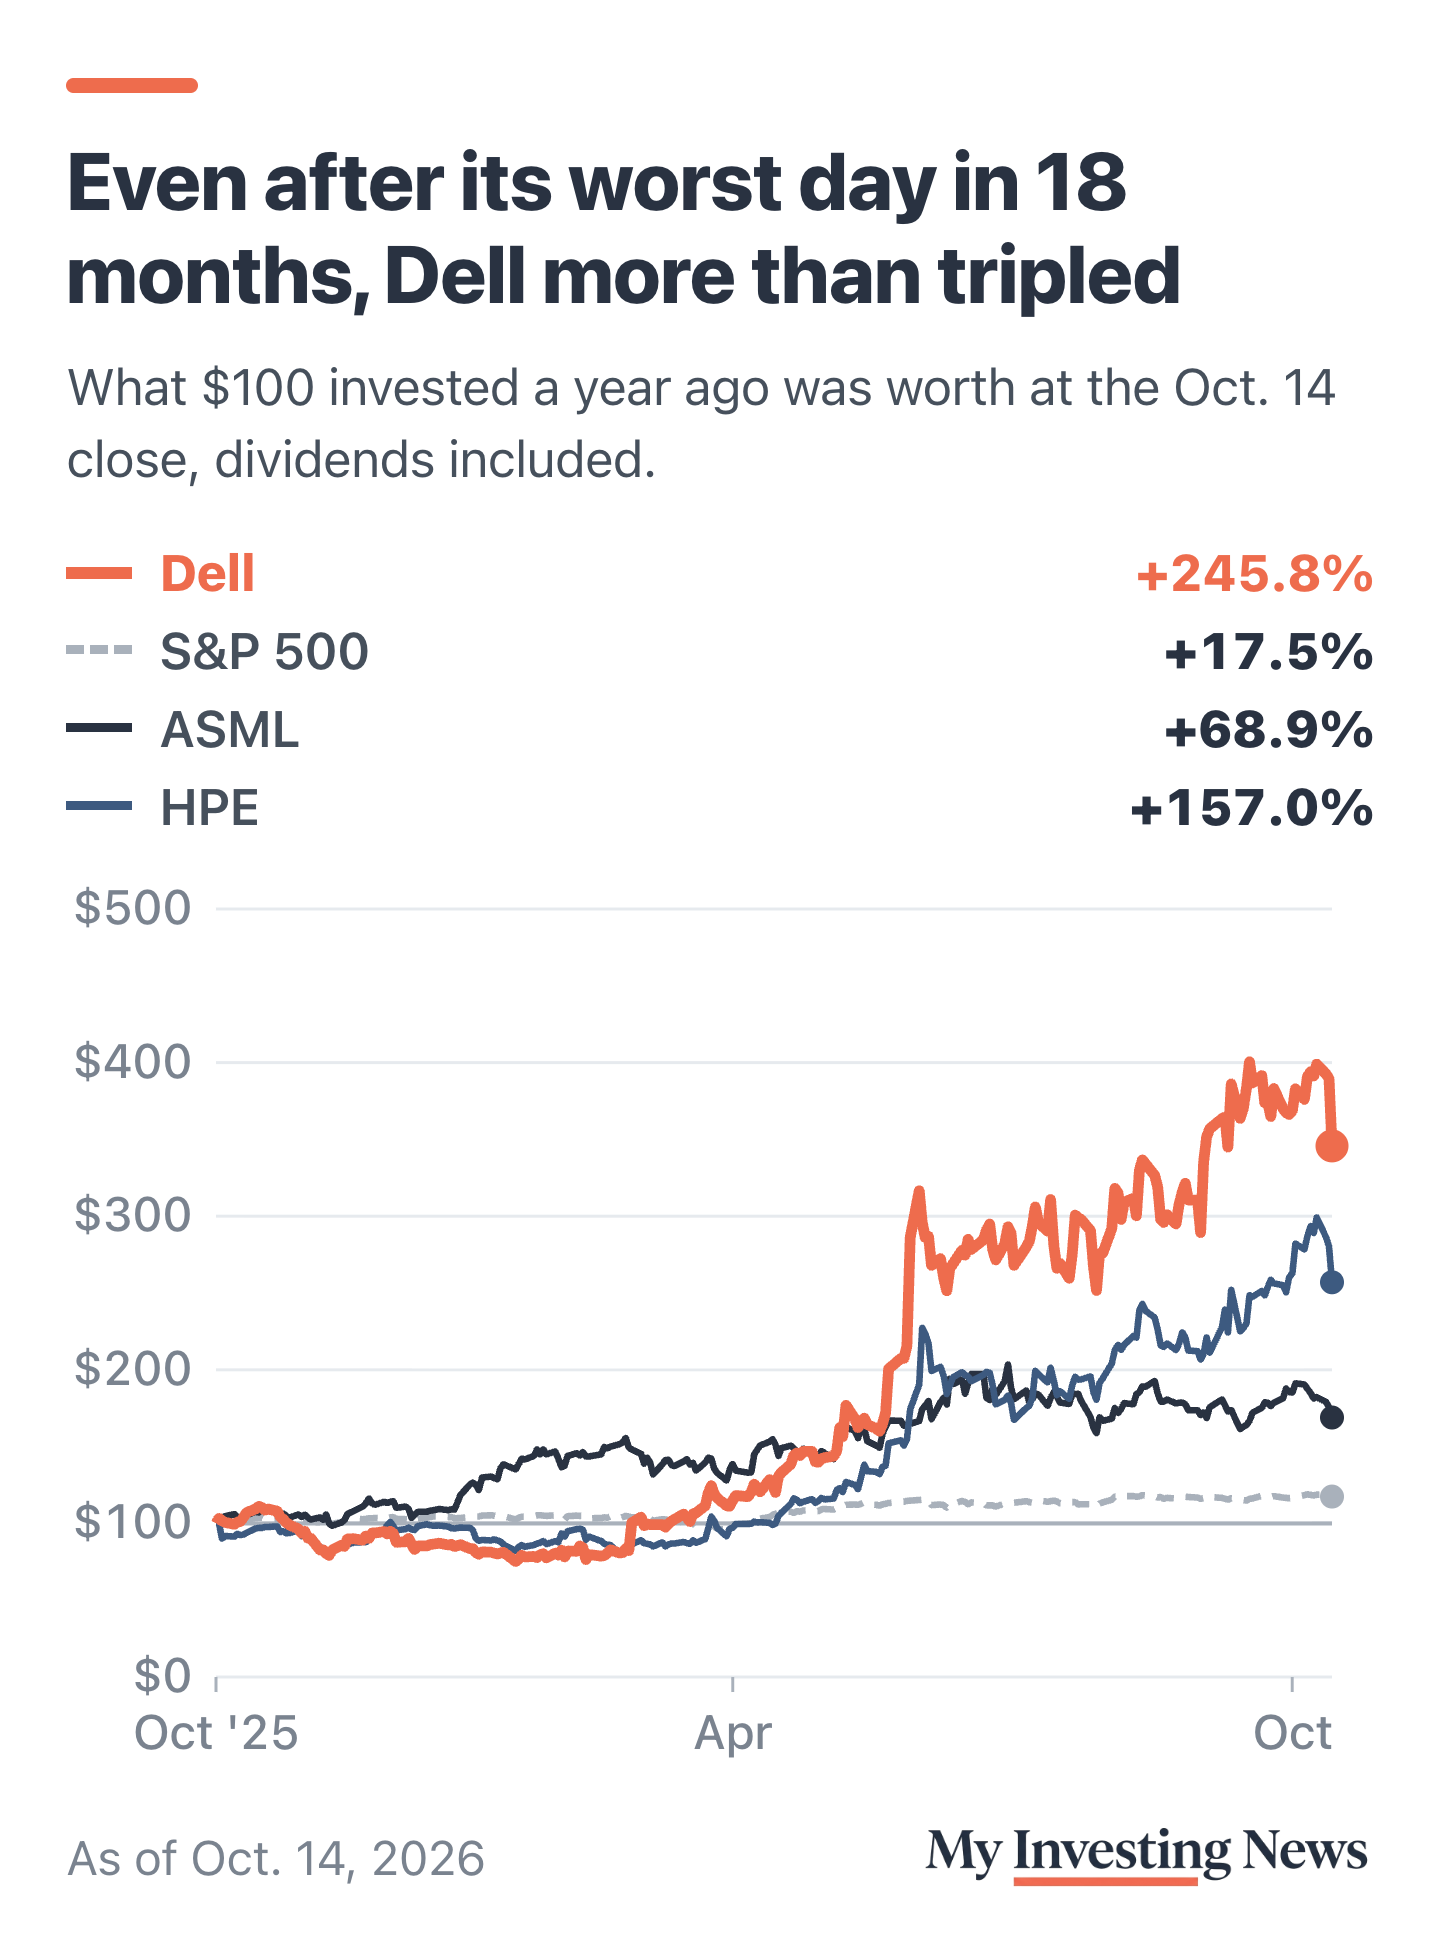
ASMLASML shows the same pattern. The lithography maker closed at $1,650.00, down 3.9% in the session and 8.6% over the week, while holding a 54.2% gain this year. The drop came hours after a third-quarter earnings release showing revenue of $13.06 billion, up 55.2% year over year. Net income of €4.96 billion beat the €4.1 billion analysts expected, according to LSEG estimates cited by CNBC, though it includes a gain of about $570 million (€510 million) on equity investments. ASML has raised its outlook three times this year. Cramer blamed Korean memory trading: “We are linked to SK Hynix. And as long as that’s the case and Hynix was down badly, then it didn’t matter what ASML did.” He called it “a great quarter.” Two days earlier, a JPMorgan strategist had called semiconductor stocks cheap.
ASML’s chief executive said planned supply for 2027 and 2028 “will not fully meet the demand of our customers,” and some customers want to place orders for 2029 and 2030.
Inflation Backdrop Cramer Blames on Tariffs
Bureau of Labor Statistics data show September headline CPI rose 3.7% from a year earlier. Core CPI, which leaves out food and energy, rose 2.6%, up from 2.4% in August. Cramer says tariffs and geopolitical disruption are driving the increase. He adds that the burden falls hardest on lower-income earners, which he calls a regressive tax. “If you want to mandate higher prices, you’re gonna have a hard time doing it better than this guy. I mean there’s so many of these things, right to gasoline, right to diesel. I mean food is right to diesel.” The tariff link is Cramer’s interpretation, and the CPI data do not assign causes.
Where Two-Year Treasury Yields Stand
The two-year Treasury yield closed at 4.82% on October 14, 2026, up from 4.79% the day before. The highest October reading was 4.84% on October 5. The 10-year yield had closed at a one-year high of 5.31% that same day.
Michael Dell’s Order Book Argument
Michael Dell, the company’s chairman and chief executive, told CNBC’s David Faber in an interview replayed on the show: “There’s incredible demand. And we’re still at the beginning of the S-curve of this.” He added, “I don’t think there’s enough supply for it to be a bubble.” Cramer asked whether “maybe we should be listening to Michael Dell.”
The filings back him up. Dell’s fiscal Q2 2027 results showed a record $60.9 billion in AI server orders and a $95 billion backlog. Full-year revenue guidance rose to $192 billion. Still, a chief executive describing his own order book is a real signal and also comes from an interested party.
Dell’s fiscal second quarter at a glance
Management said “We are supply constrained,” identifying “DRAM, DRAM, DRAM” as the main constraint. So Dell’s ability to turn backlog into revenue depends on the same memory market that Cramer says is driving trading. Q2 free cash flow also fell 47% to $986 million.
Michael Dell is describing a data-center expansion. It is the same wave lifting the suppliers around it: power, cooling, networking, and the server integrators Dell competes with.
What Would Prove Cramer Right
Barclays downgraded Dell, HPE and NetApp that morning, saying it had not seen a “meaningful AI inflection” in enterprise spending and that strong enterprise revenue reflected memory costs more than AI, CNBC reported. That leaves the bull case resting on management commentary and order visibility, and nothing in that day’s trading supported it.
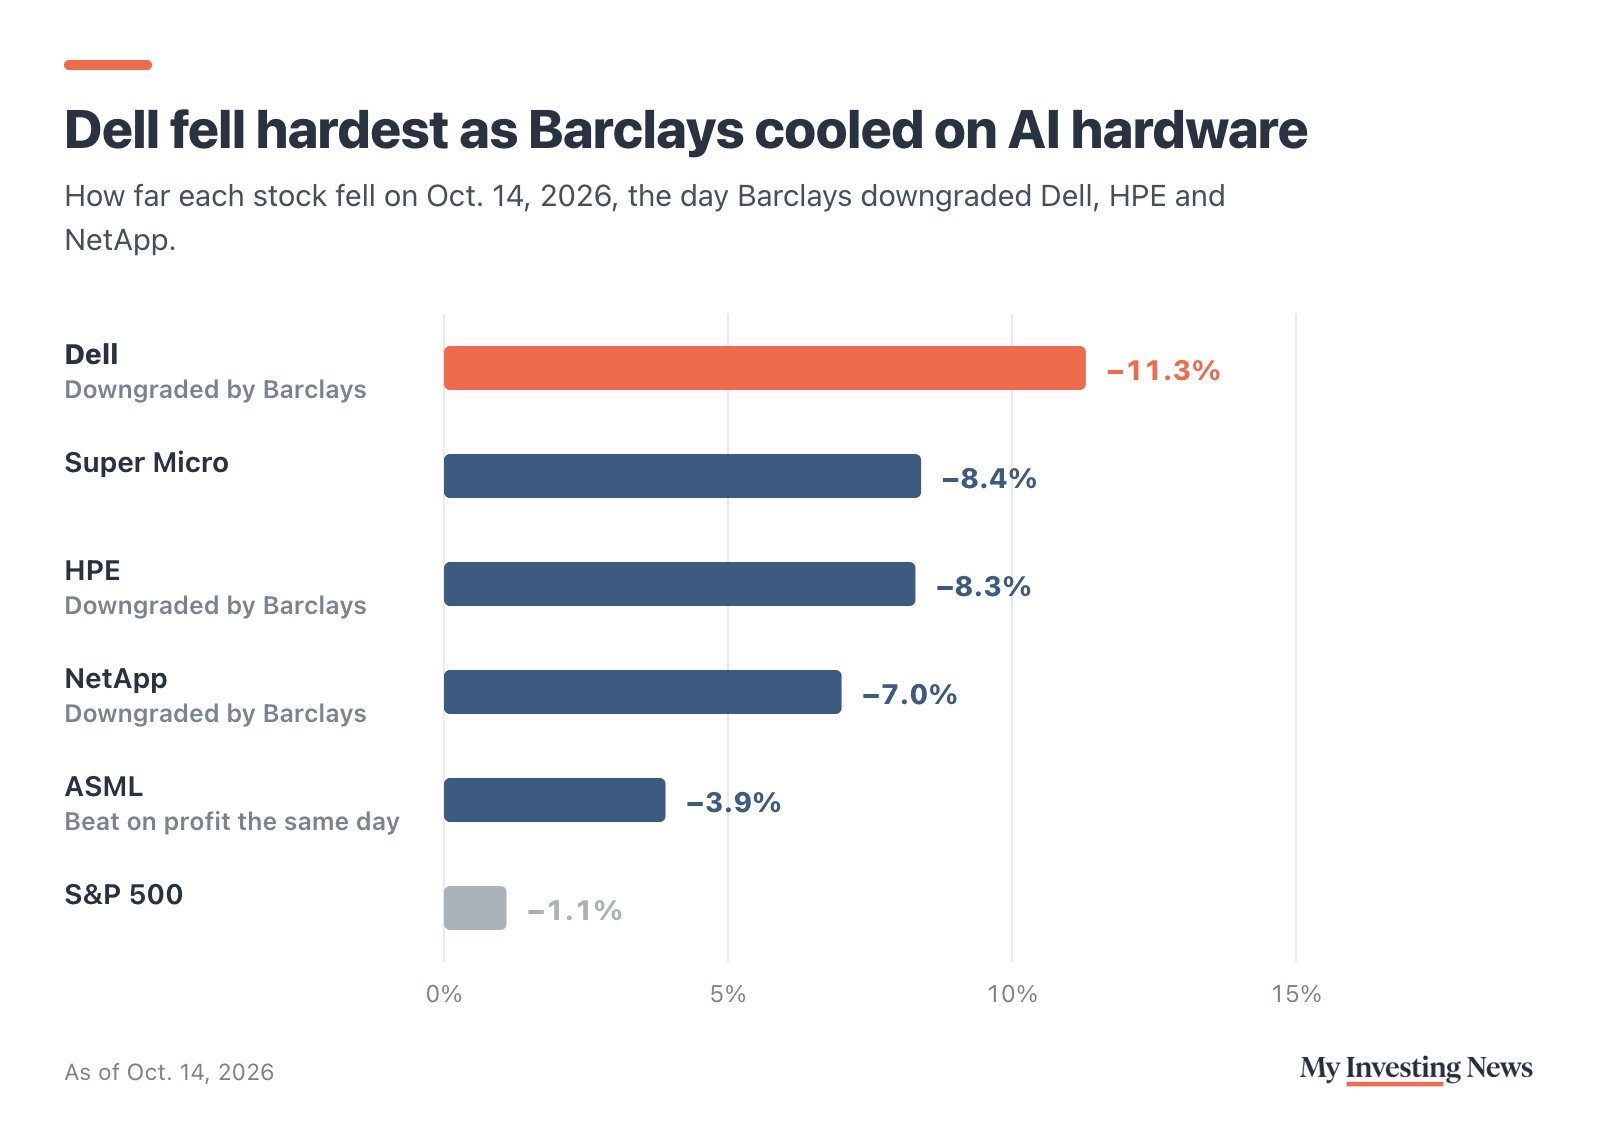
Cramer’s read on demand holds up based on the order books at both Dell and ASML, and the test is whether Dell and ASML hold their levels once Korean memory trading cools off. If hardware names keep falling after SK Hynix and the Kospi steady, the memory-linkage explanation fails. The next checkpoint is Dell’s fiscal Q3 earnings report, guided to $49.0 billion in revenue and $6.50 in non-GAAP EPS.
Cramer sees Dell’s drop as a chance to buy a leader that was still up more than 300% this year, backed by a $95 billion AI backlog and Michael Dell’s view that demand outruns supply. The risk is the one Barclays raised: if businesses are slow to spend on AI and memory prices ease, the revenue lift from pricier memory could fade.