Where we heard itCNBC’s Squawk on the Street, Oct. 14, 2026, the morning the September consumer price index came out. Speaker: Jim Cramer, CNBC host.
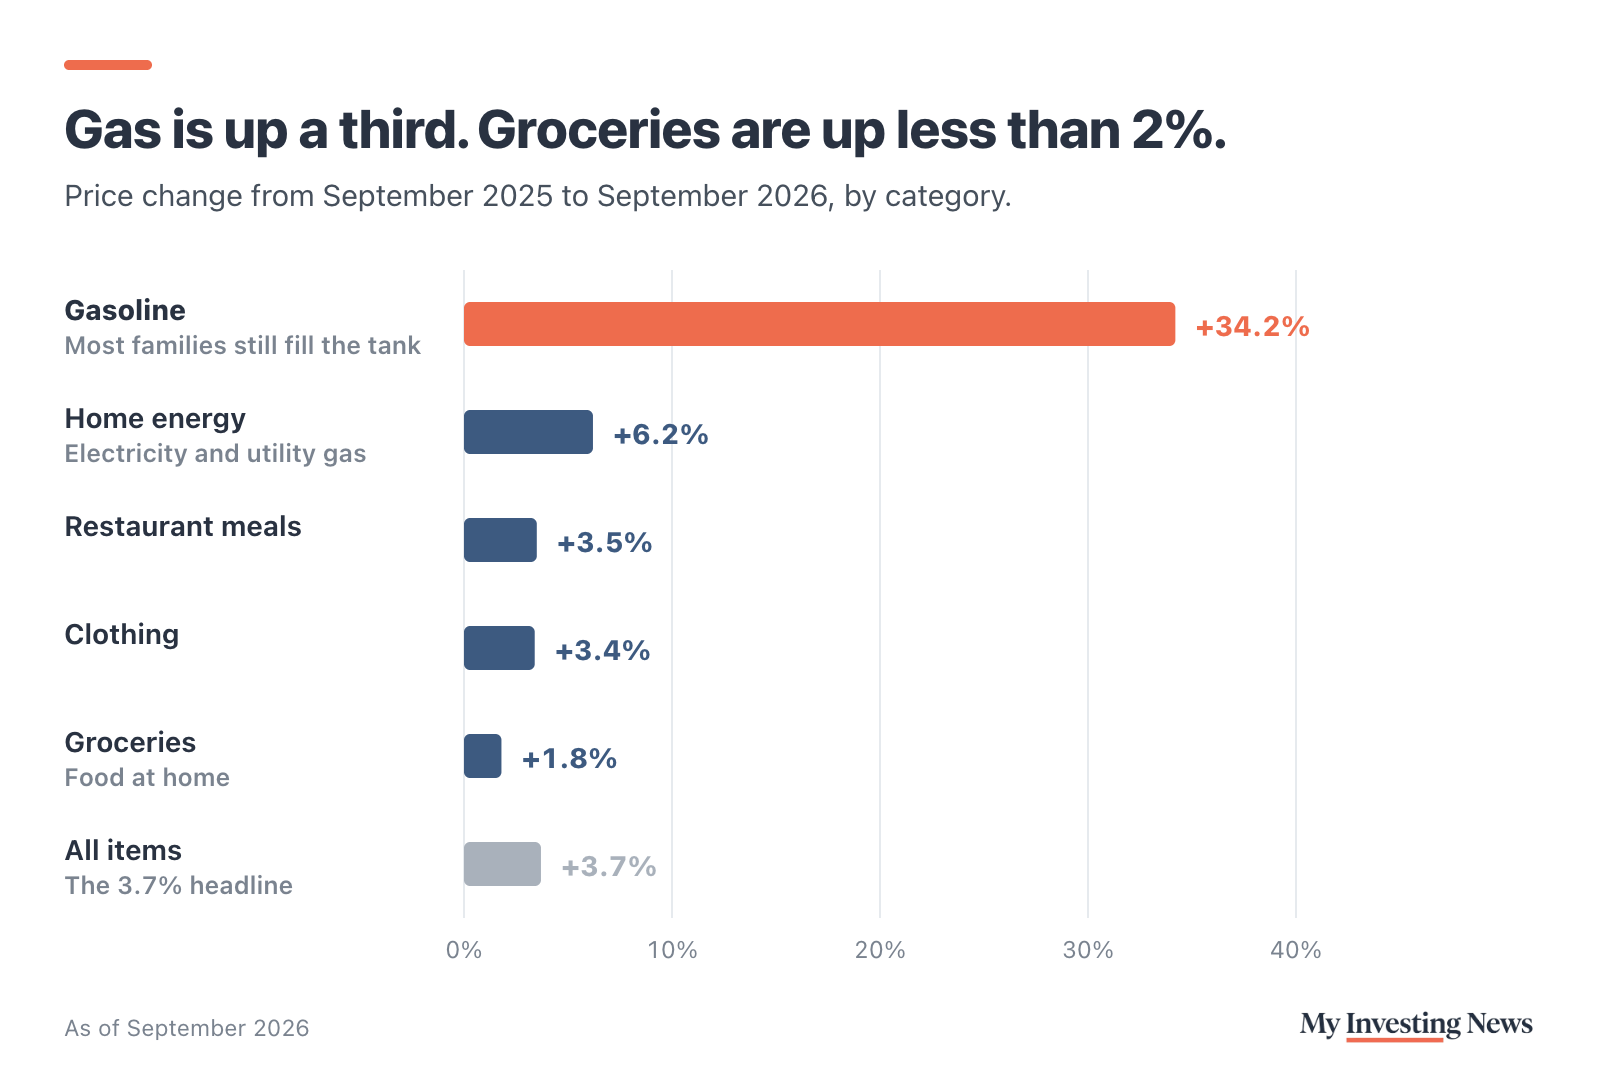
Jim Cramer reacted on CNBC to the September consumer price index with a pointed claim: price increases driven by tariffs are hitting hardest the families least able to absorb them. The report behind his reaction showed consumer prices up 3.7% from a year earlier.
Cramer named families making $30,000 to $60,000 as the group carrying the heaviest load. For anyone at or near retirement, the stakes are concrete. Any increase in categories you cannot skip comes straight out of a budget that gets one raise a year. Cramer is right about who can least afford it. Survey data adds a twist he left out.
Why a Price Increase Hits a Smaller Budget Harder
A regressive tax takes a bigger share of income from people who make less. Price increases work the same way. Say groceries cost an extra $50 a month (an example figure). That $50 is the same at every income level. On a modest retirement budget it forces a tradeoff somewhere else. On a large budget it barely shows up.
The category matters as much as the size of the increase. Groceries, fuel and clothing are close to non-negotiable. Regular gasoline averages $4.33 per gallon nationally, and most families still have to fill the tank. Higher prices on restaurant meals or travel let you cut back. When they rise on essentials, your options are much narrower.
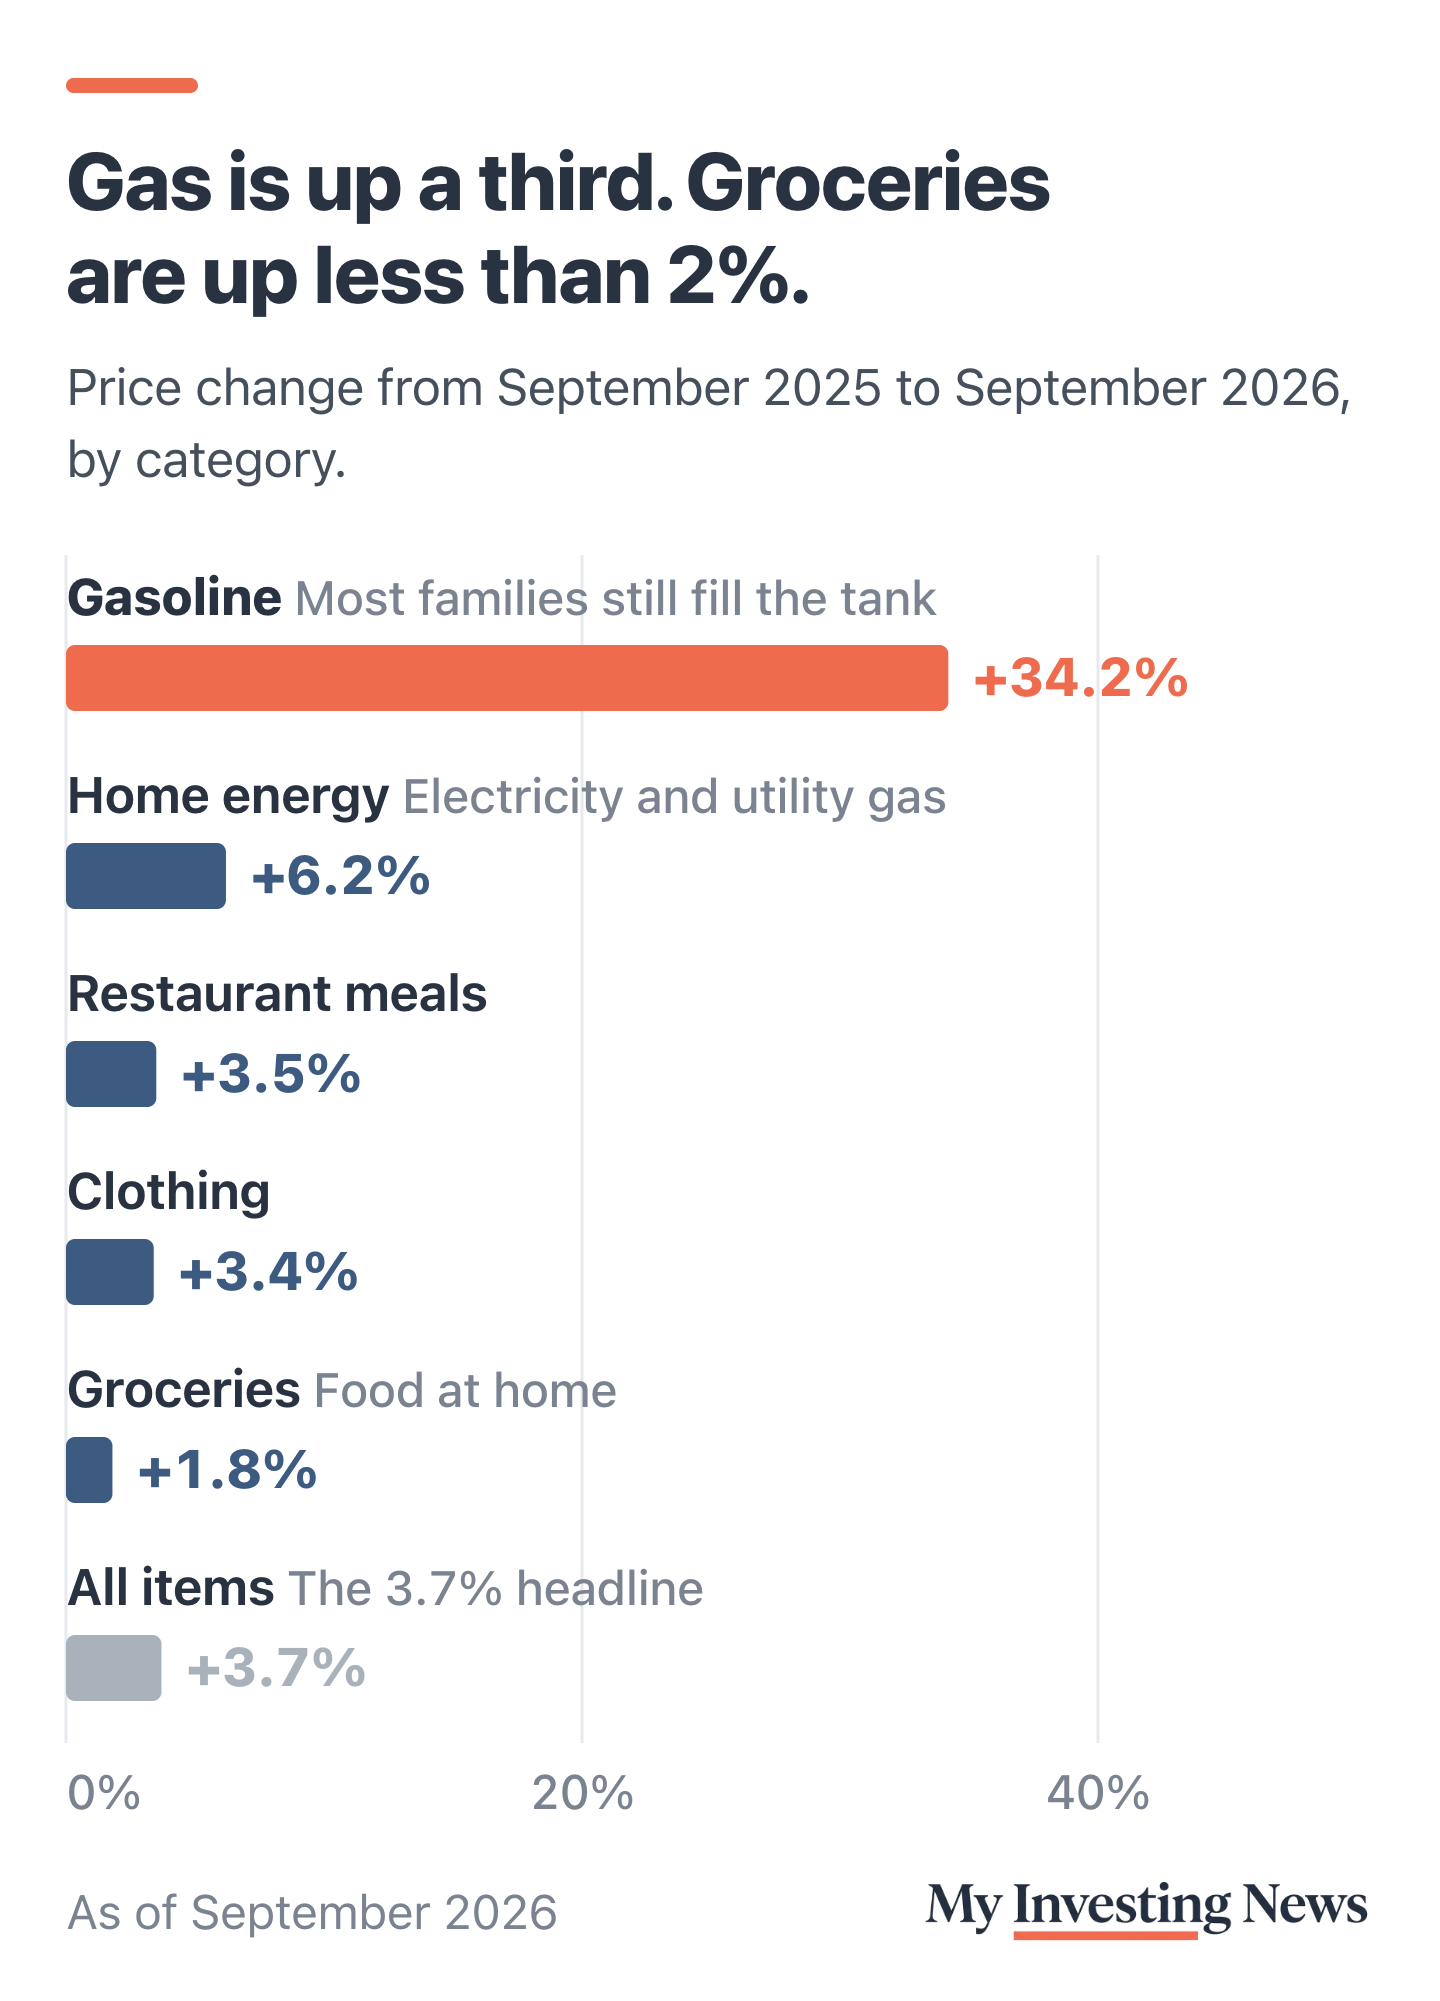
Cramer blames tariffs and geopolitical disruption for the pressure. That causal link is his reading of the report, and readers should treat it as his argument.
Lower Earners Started With the Least Room to Spare
The FINRA Foundation’s National Financial Capability Study shows who is most exposed. It is a large national survey, and its 2024 wave was published in 2025. These figures describe that survey period, not this month. They also measure general cost pressure and financial capability. They do not measure tariff effects.
In the 2024 wave, only 23% of adults in the lowest income group said covering monthly expenses was not at all difficult. In the highest income group, 63% said the same. The core of Cramer’s point is that gap. A price shock lands on people who were already struggling.
Saving shows the same split. Just 29% of the lowest earners spent less than they made, compared with 48% of the highest earners. Across all adults, 26% spent more than their income in 2024, a record for the study. That compares with 19% in 2021.
Middle and Upper Earners Lost the Most Ground
Since the 2021 wave, FINRA Foundation found the share of the lowest earners who reported no difficulty covering expenses fell by seven percentage points. Among higher-income adults, it fell by 11 to 14 percentage points.
No trouble paying the bills, 2021 to 2024
The lowest earners started in a far worse position, so they had less room to fall. The sharper erosion came among families that used to feel comfortable. The study’s authors call this a “struggle of the middle,” and it fits the income band Cramer named. It complicates a simple regressive story. His point about who has the least room to absorb a hit still holds.
Where the 2027 Social Security Raise Fits
The Social Security Administration set the 2027 cost-of-living adjustment at 3.6%, according to its 2027 fact sheet. The agency estimates the average monthly benefit for all retired workers will rise from $2,095 to $2,170. The maximum monthly benefit at full retirement age will be $4,188.
Keep these two figures separate from the September inflation number. The adjustment is based on a different index, the consumer price index for urban wage earners and clerical workers. It averages that index across the third quarter and compares the result with the same quarter a year earlier. The September headline compares one month of the broader all-urban index with the same month a year earlier. Because the baskets and time windows differ, the two numbers do not line up as a direct comparison.
Run your own numbers against inflation to see whether the raise keeps pace with the categories you actually spend on.
Food Bills and Thinner Cushions Show the Strain
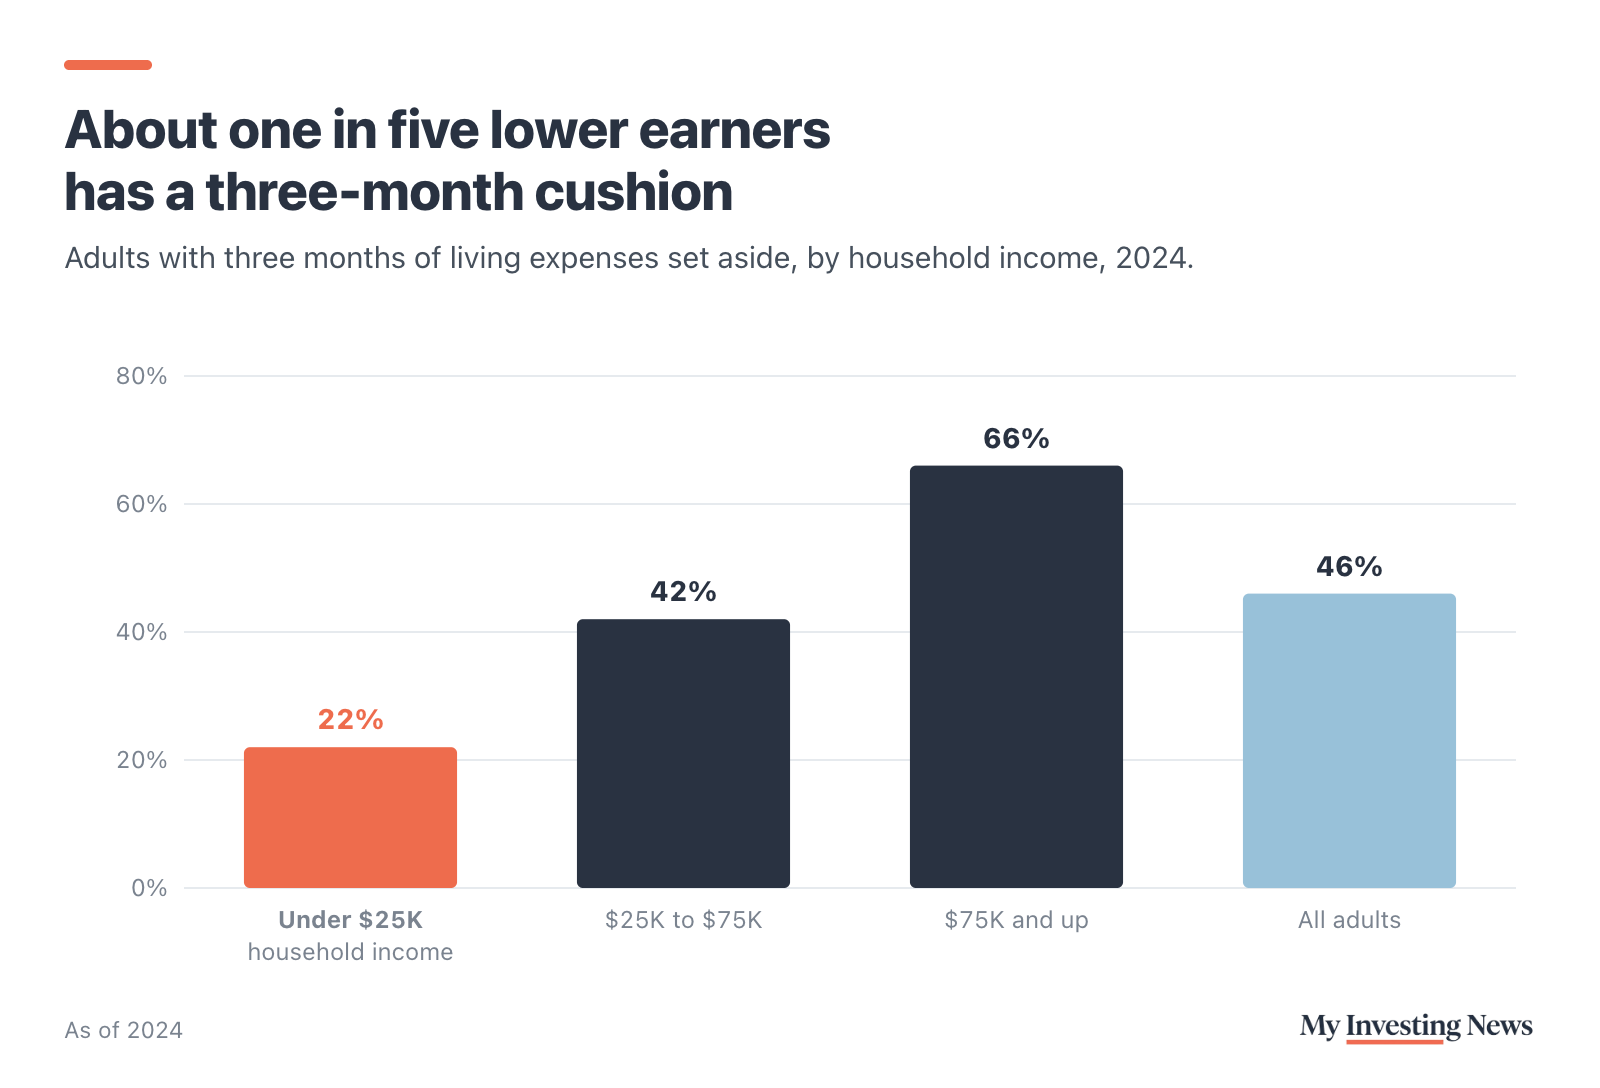
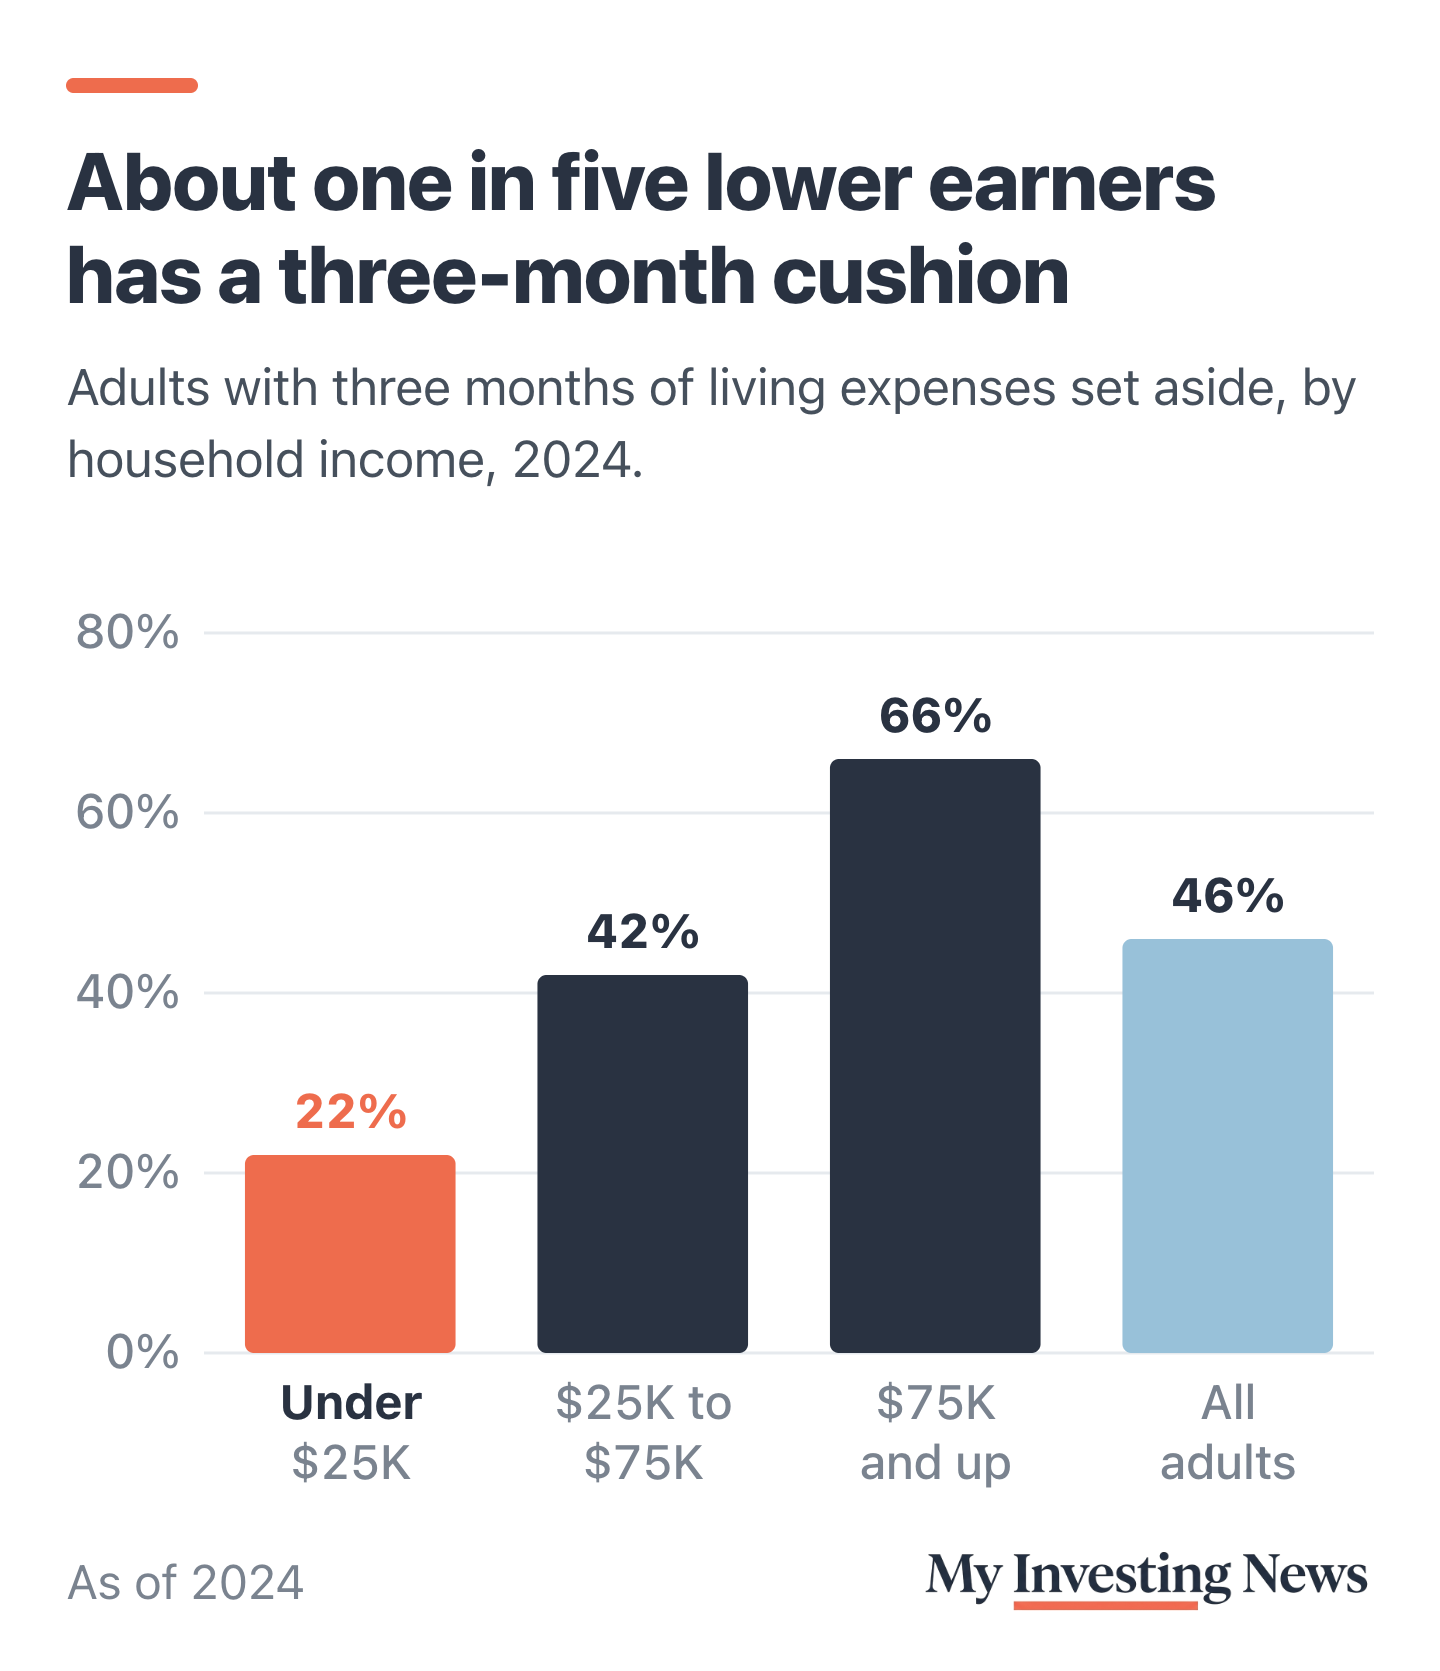
The same 2024 FINRA Foundation wave shows how families responded. About two-thirds of adults said higher food costs led them to cut back on other spending. Only 46% had set aside three months of living expenses, compared with 53% in 2021. Those families had less cash to fall back on even before September’s reading.
Where a Fixed-Income Household Has Real Leverage
Prices for eggs and gasoline are set for you. You can control which plans and brands you pay for. Medicare open enrollment runs from Oct. 15 to Dec. 7, so compare your Part D or Medicare Advantage plan against this year’s drug and premium costs (IRMAA surcharges and coverage gaps catch a lot of people off guard). Track three months of grocery and fuel spending to find your own inflation rate, then move to store brands and fuel rewards where your spending is highest. On a fixed income, the main place to make up ground is the recurring bills you can still renegotiate.
Cramer calls tariff-driven price increases a regressive tax on households earning $30,000 to $60,000, and survey data agrees that lower earners have the least room to absorb them. The twist is that middle and upper earners lost the most ground since 2021. For retirees, the risk is that a 3.6% raise falls behind on essentials like gasoline, which cost about a third more than a year ago.