Where we heard itFederal Reserve Board, “Changes in U.S. Family Finances from 2022 to 2025: Evidence from the Survey of Consumer Finances,” released Oct. 9, 2026. Read the report
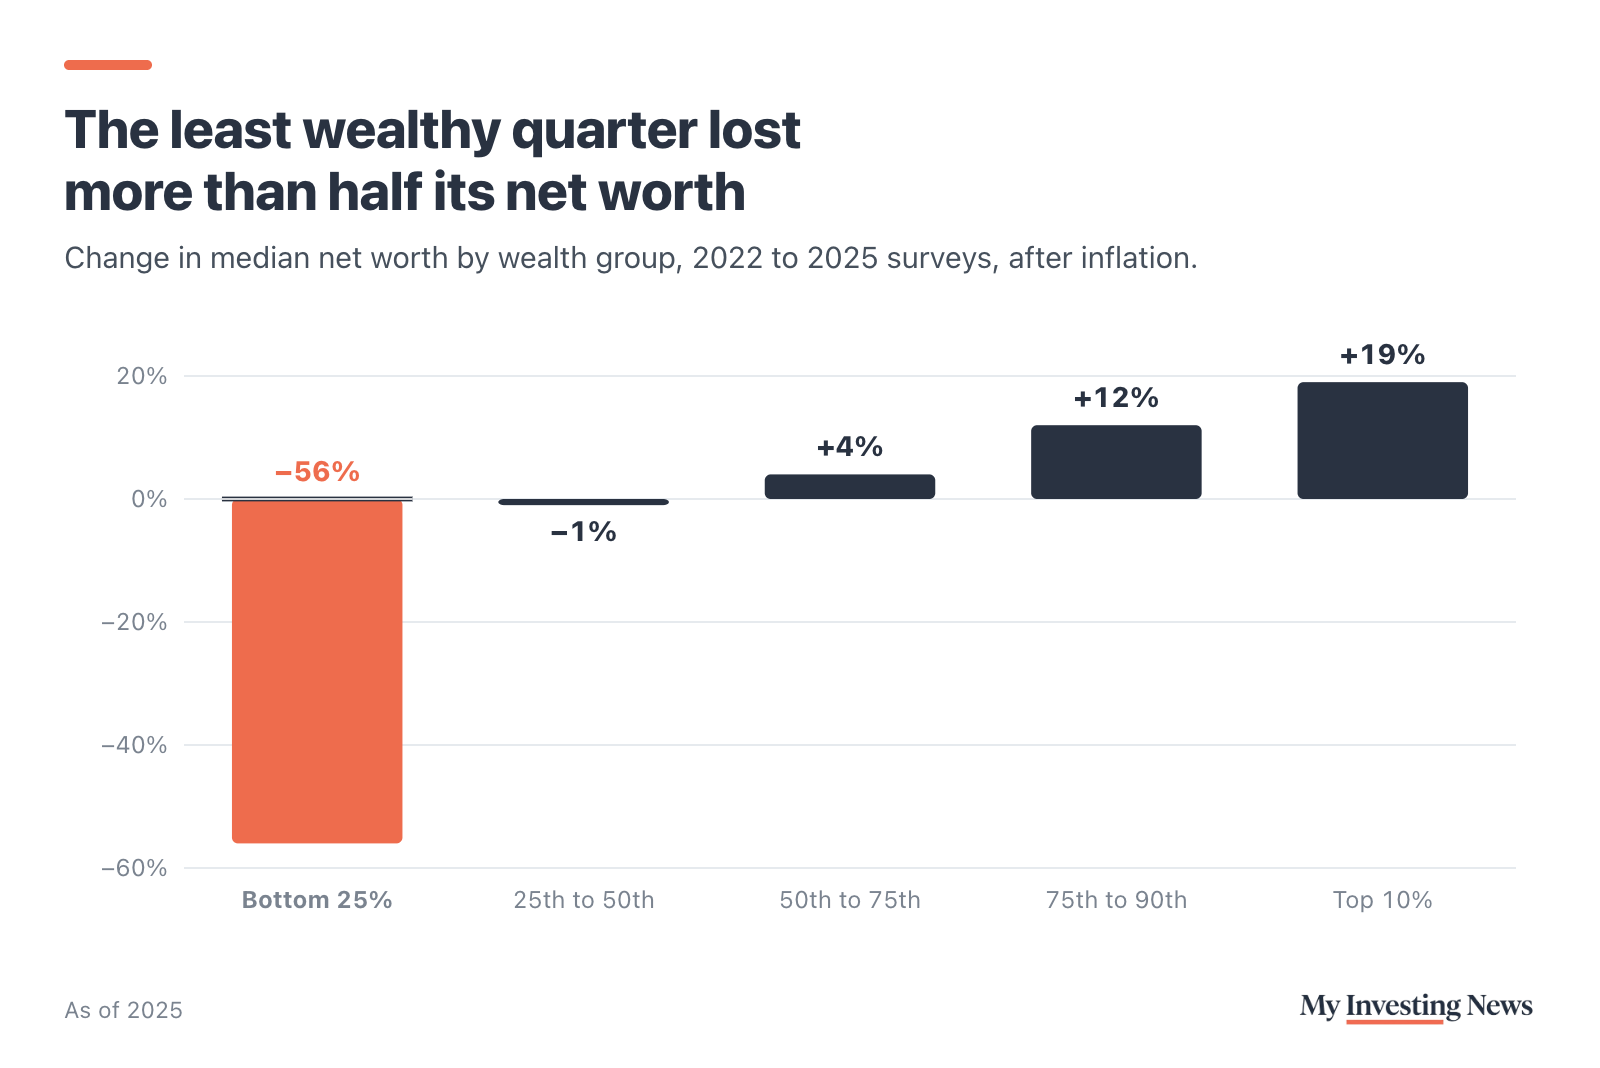
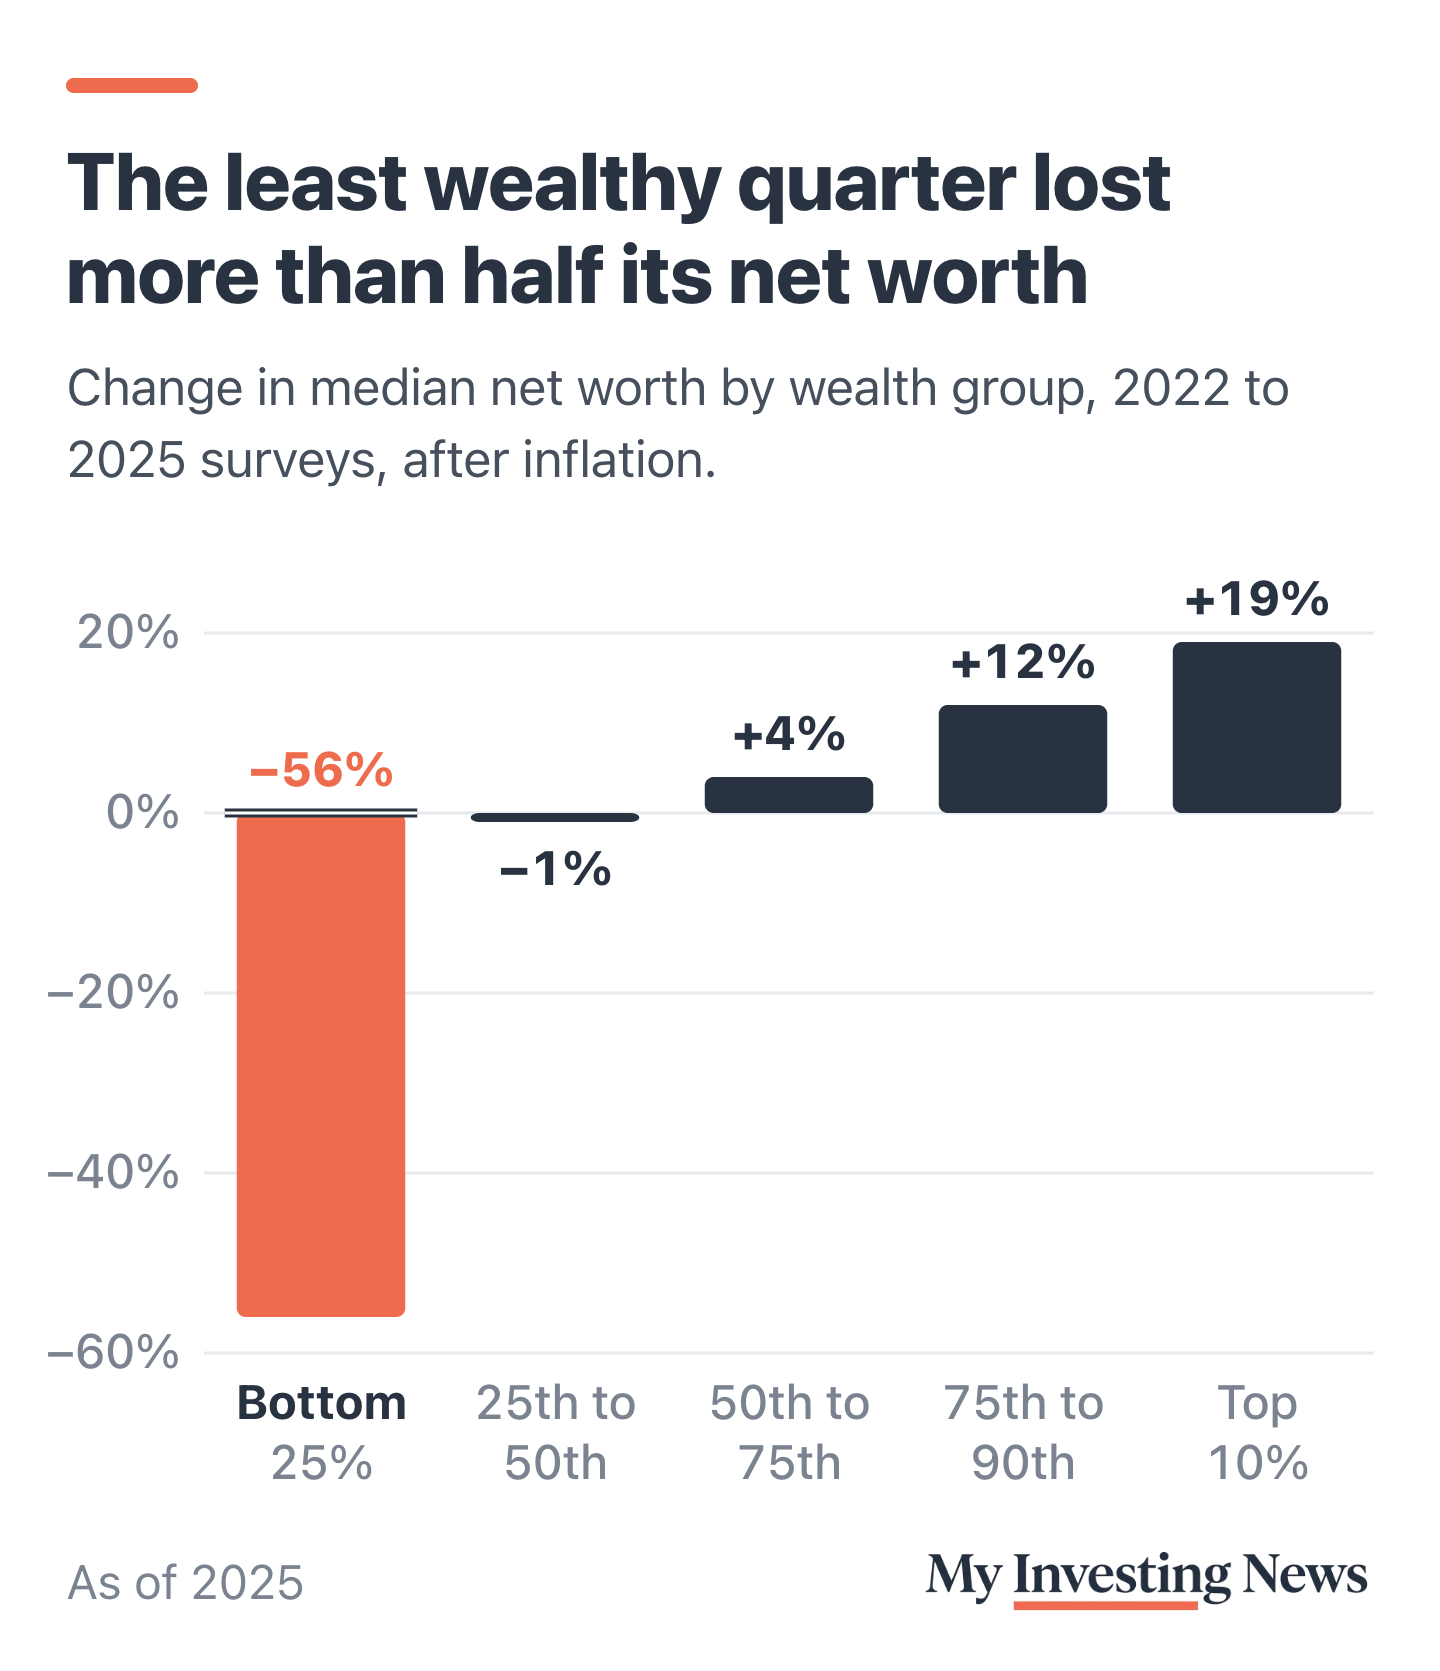
Between 2022 and 2025, real income rose 3% to 7% for the bottom 60% of American families, while the top 10% of earners saw real income fall 6%. Over the same period, the median net worth of the least wealthy fourth of households fell more than 50%, from $3,800 to $1,700. Those are findings from the Federal Reserve’s Survey of Consumer Finances, released October 9, 2026. The survey covers the 2022 to 2025 period and is conducted every three years; the 2025 edition interviewed 4,367 families.
Income Gains Flowed to the Bottom of the Ladder
The income data runs against the usual inequality story. According to the Fed’s tables, real median income for the bottom 60% of families rose between 3% and 7% over the survey period, while the top 10% of earners saw a real fall of 6% (see Reuters’ report on the release). “Real” means the figures are adjusted for inflation, so they measure actual purchasing power. Overall median family income rose 7% after inflation, reaching $82,200 by the 2025 survey. On paychecks alone, lower earners gained ground from 2022 to 2025. Jim Cramer has called tariff-driven price increases a regressive tax on families earning $30,000 to $60,000.
Wealth at the Bottom Still Fell by More Than Half
Net worth moved the other way for the least wealthy. The median family in the bottom fourth by wealth held $3,800 in the 2022 survey and $1,700 in the 2025 survey. Real median net worth across all families rose 2% to $215,900. The Fed also reported that median wealth for Black families fell 25% over the period, after rising 60% from 2019 to 2022.
Why Paychecks Lost to Portfolios
Stock market participation slipped from 58% of families in the 2022 survey to 56% in 2025. The homeownership rate held at about 66% throughout, leaving financial assets to explain most of the split.
A raise lifts the month. An owned asset lifts the decade. A household with no equity exposure shared in none of the portfolio growth the survey recorded, however much its paycheck grew.
CNBC’s Robert Frank, reporting on the data on October 14, said only 19% of Americans now own stocks directly, down from 21% in 2022. Robert Frank said median holdings for those who stayed in the market rose 36% to $77,400. Robert Frank also said the median stock portfolio of the wealthiest 10% of households grew by over a half million dollars to $1.7 million.
The 2025 survey in four numbers
Older Households Pulled Away From Younger Ones
The survey found wealth rose 37% for families whose main member was older than 75. Separately, Robert Frank spoke on CNBC. He said households over the age of 75 are now the wealthiest, with average net worth of $1.96 million. Robert Frank also cited a wealth fall of 23% for households under the age of 35. Older families entered the survey period with decades of compounding already in place, and younger families had the shortest holding periods and the smallest asset bases.
Debt Stress Absorbed the Raises
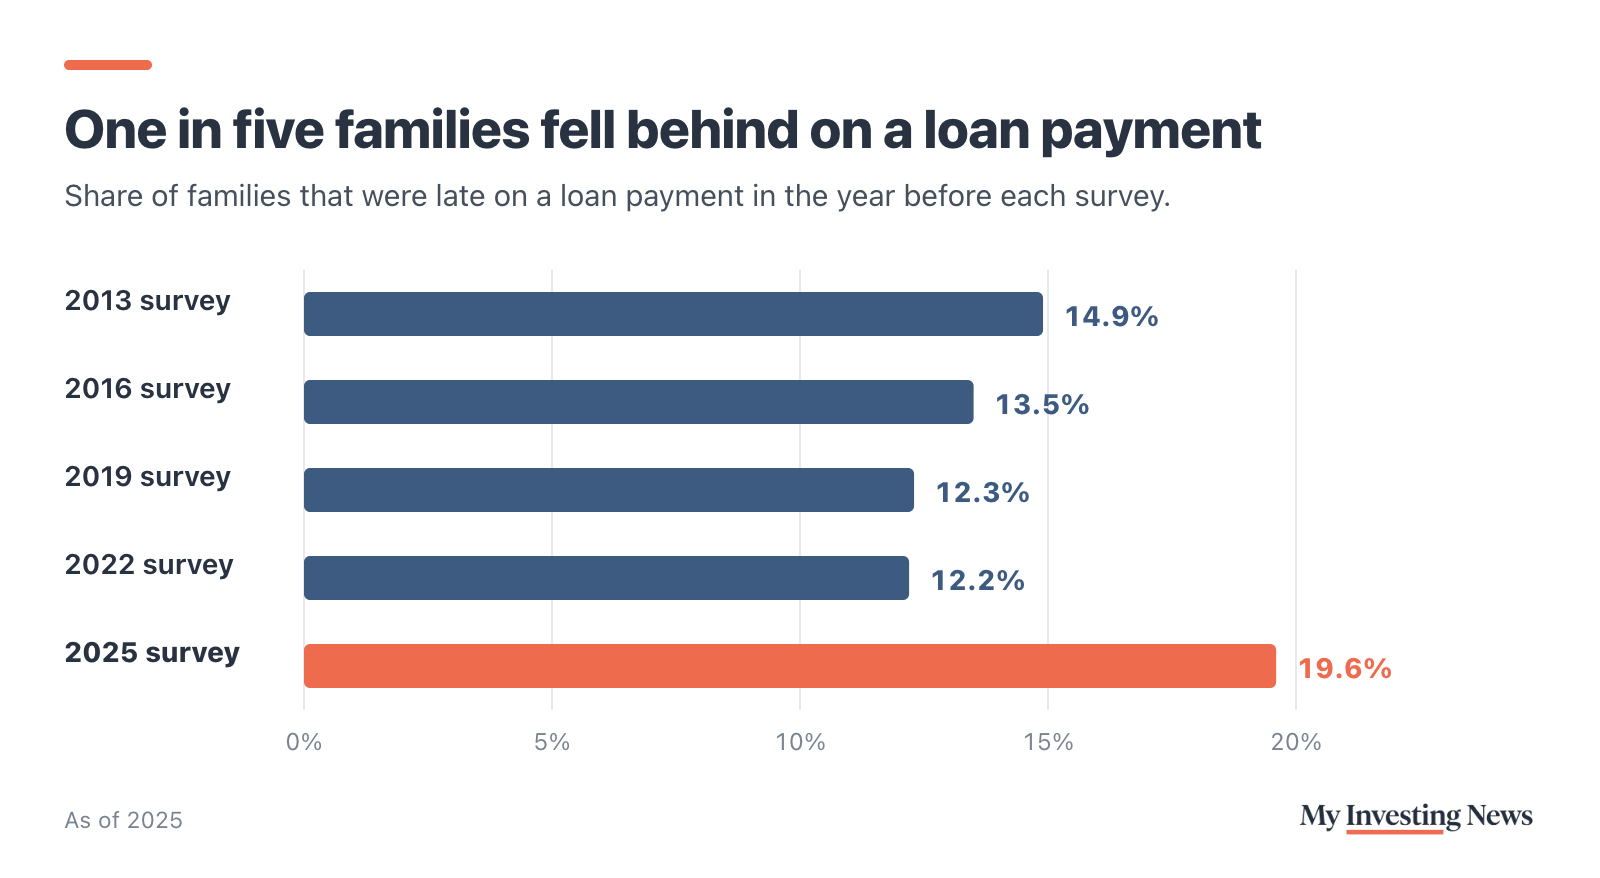
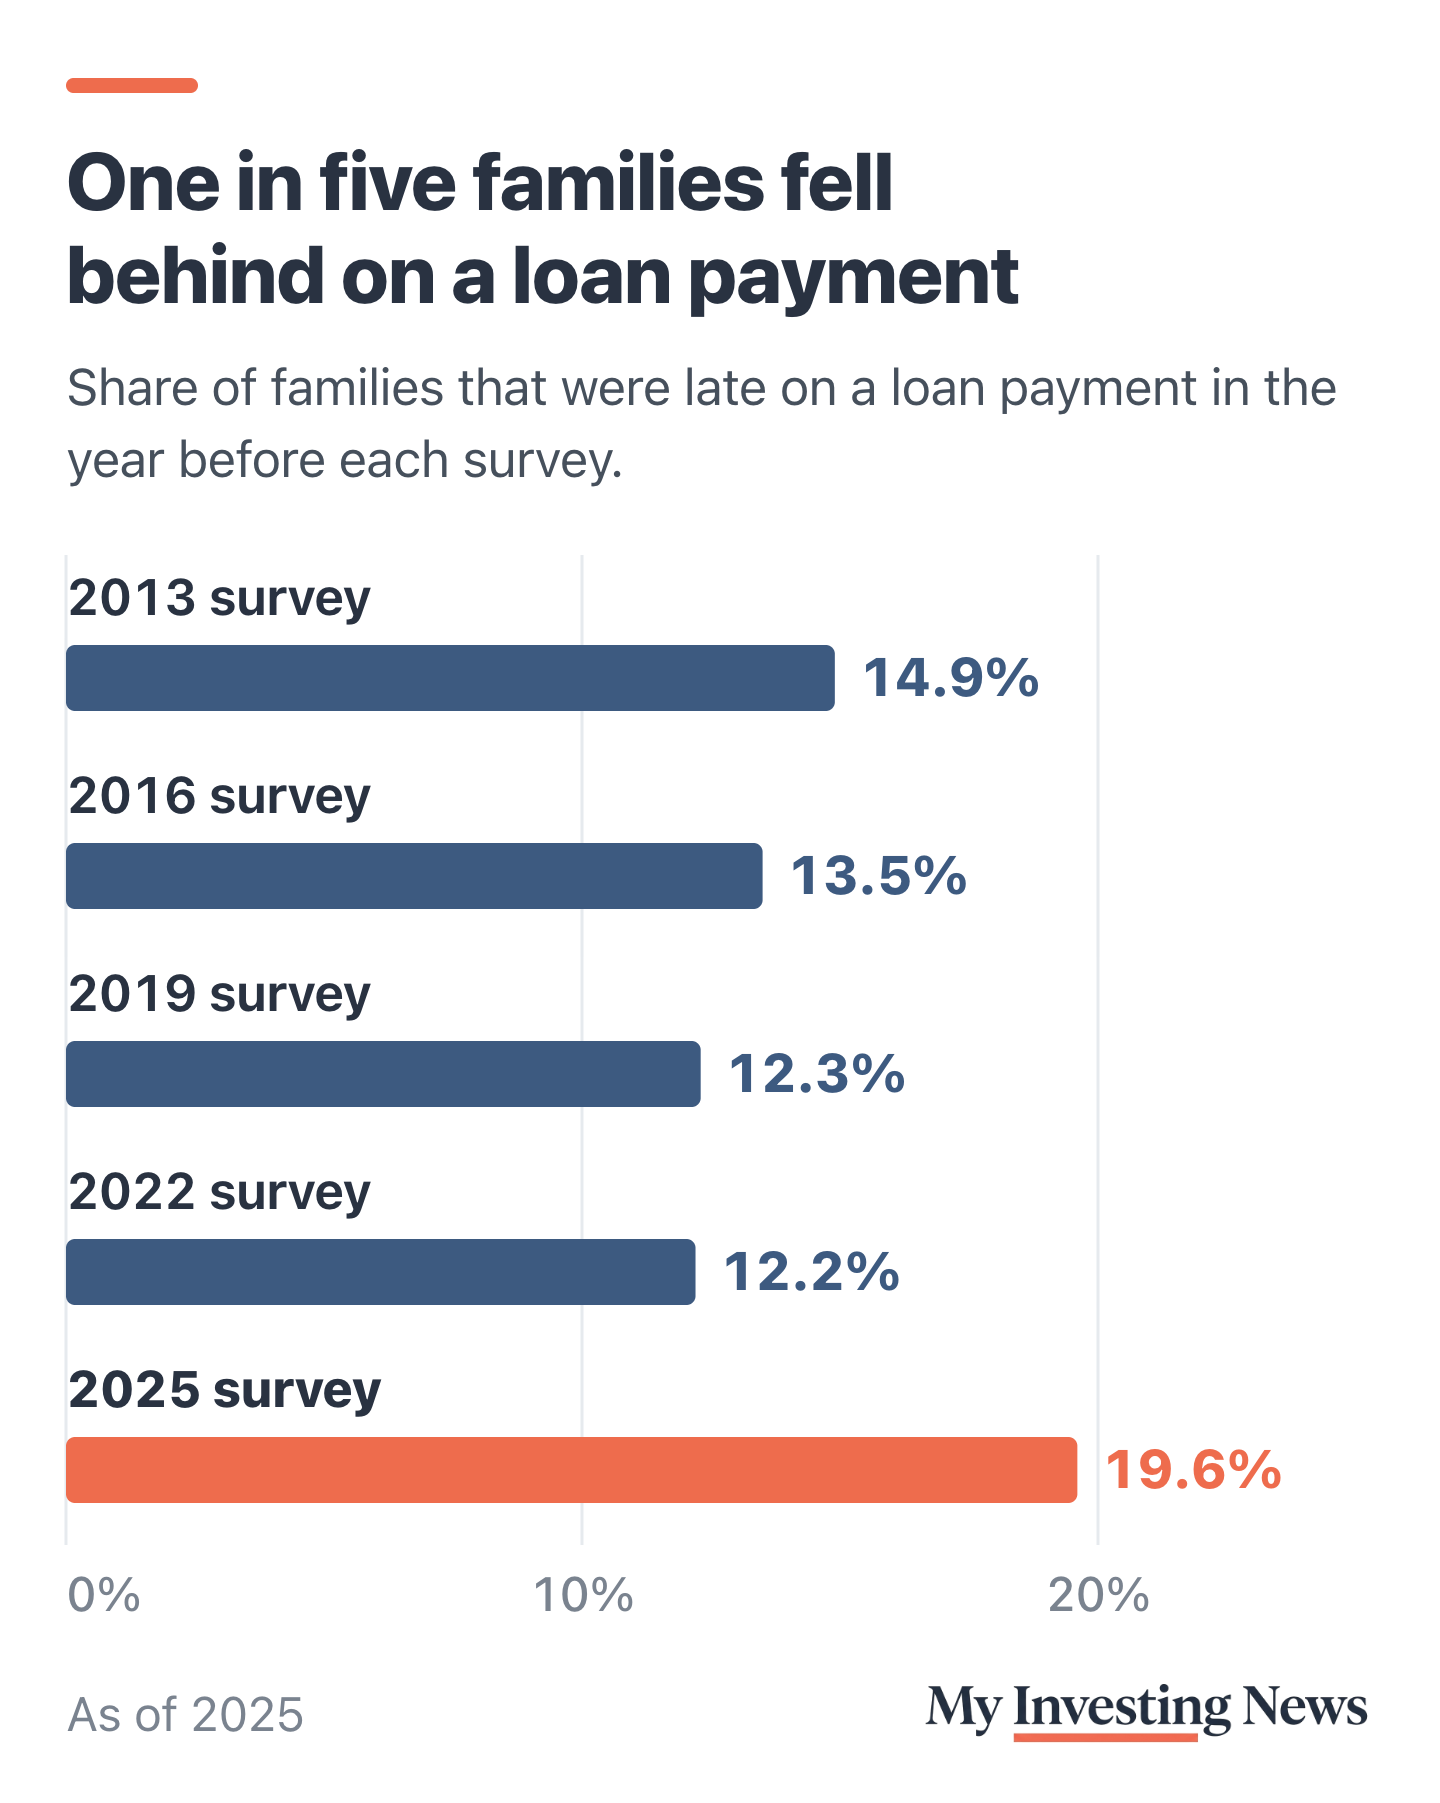
The share of families reporting being behind on loan payments rose from about 12% to almost 20% over the period. A separate FINRA Foundation survey found a record share of adults spending more than they earn. Use of buy now, pay later plans climbed from 7% to 12% of households. A March 2023 Consumer Financial Protection Bureau study examined BNPL borrowers. It found they were, on average, much more likely to be highly indebted and to carry delinquencies on traditional credit.
Bank data offers a different lens. The credit card delinquency rate at commercial banks was 2.85% in the second quarter of 2026, down from 3.22% two years earlier. That series tracks card balances, while the Fed survey counts families, which points to stress concentrated in households with thin cushions. Income spent catching up on payments never reaches a brokerage account.
What Investors Should Take From the 2025 Survey
The 2022 to 2025 survey rewards two behaviors: participation and duration. Families that stayed invested compounded, and families that stepped out or never stepped in missed the portfolio growth the survey recorded. The survey shows how wide the gap grew between households that converted income into ownership and those that did not. For anyone approaching retirement, years invested matter most. The asset that matters most is time already spent in the market, and the next edition of the survey will measure the same divide.
The Fed’s 2025 survey shows lower earners gained ground on pay and lost ground on wealth, because the past three years mostly rewarded families that already owned stocks and other assets. The risk sits in debt: almost one in five families fell behind on a loan payment, the highest share since the 2010 survey.